


EN
Casella Waste Systems (CWST) Faces Jana Pressure, Is The 12% Undervaluation Still There?
Jana Partners has stepped into Casella Waste Systems (CWST) with an activist campaign that targets higher profitability, tighter capital use, and a reset of executive pay toward shareholder outcomes.
Recent trading has been choppy for Casella Waste Systems, with the share price down 2.55% over the last day but recording a 13.95% 30 day share price return that suggests momentum has picked up after a weaker year to date. Activist headlines around Jana Partners’ campaign and anticipation of the upcoming third quarter 2026 results sit against that backdrop. Longer term total shareholder returns of 6.60% over one year and 24.20% over three years show a steadier, if uneven, compounding story.
Scan how activist pressure at Casella Waste Systems compares with other opportunities by reviewing our curated list of 30 resilient stocks with low risk scores that may appeal to investors focused on quality and resilience.
After a sharp 30 day rebound and fresh activist pressure, the question around Casella Waste Systems is simple. Has most of the easy upside already played out, or is the valuation still leaving meaningful room ahead?
Most Popular Narrative: 12% Undervalued
Casella Waste Systems closed at $93.71 against a widely followed fair value estimate of $106.50, which frames Jana Partners’ campaign squarely around execution and capital efficiency rather than a broken business model.
The main requirement for the strategy to work is that investments in automation, technology, and efficiency, including cost reduction programs and Mid-Atlantic synergies, translate into sustained EBITDA margin expansion despite higher operating costs and integration work.
The current valuation and high P/E multiples imply that the share price already reflects strong ongoing growth and improving returns, so any renewed margin pressure or weaker EPS delivery could limit upside and increase the risk of a derating.
See why 3 investors see Casella Waste Systems as 12% undervalued.
Result: Fair Value of $106.50 (UNDERVALUED)
Still, the thesis around Casella Waste Systems can be knocked off course if acquisition integration drags on margins or if higher diesel and cost pressures squeeze earnings.
Find out about the key risks to this Casella Waste Systems narrative.
Another View: Casella Waste Systems On Sales-Based Valuation
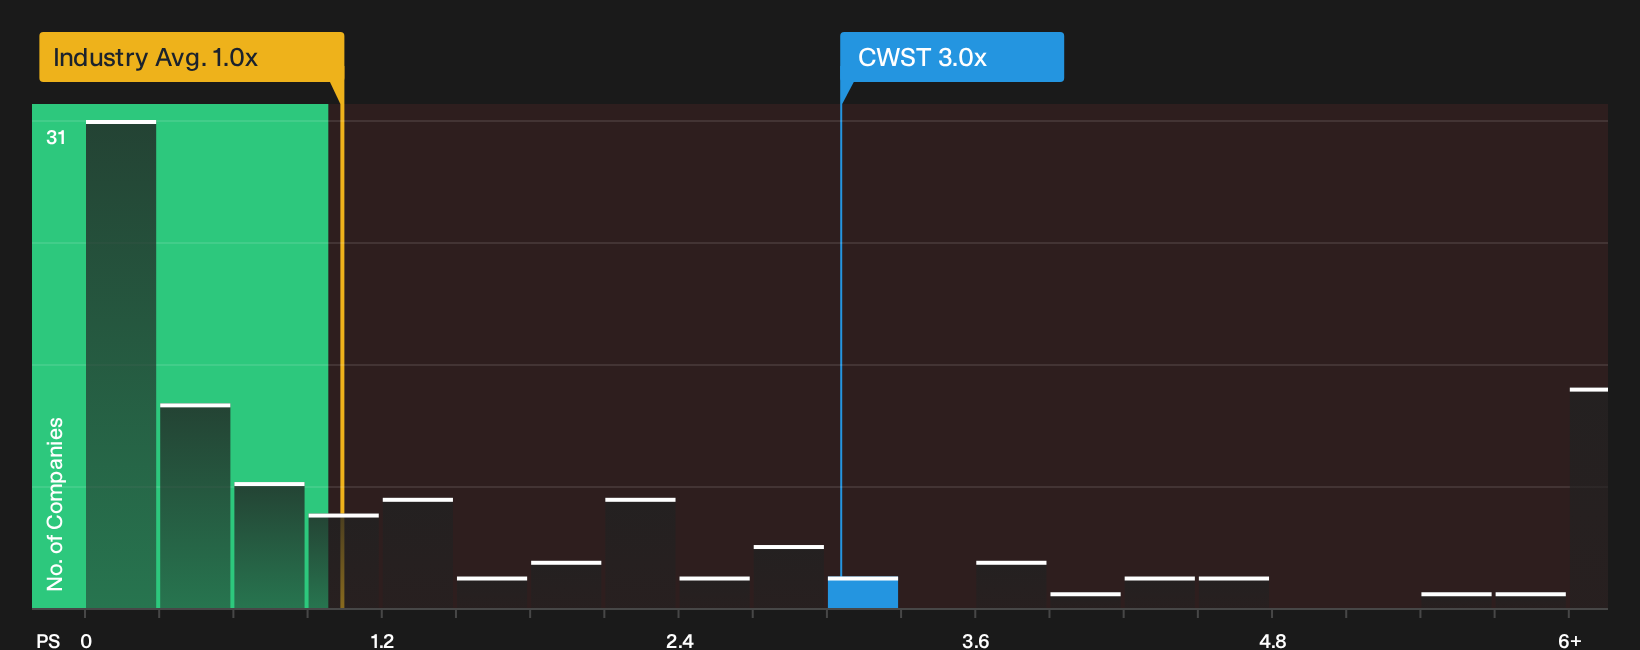
The DCF workup points to Casella Waste Systems trading below an estimated future cash flow value of $159.61, yet the P/S picture is far less generous. At roughly 3x sales versus a fair ratio of 1.6x, and 1x for the wider US Commercial Services group and 2.3x for peers, the stock carries clear multiple risk if sentiment cools. Which lens do you trust more when both activism and execution risk are in play?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Casella Waste Systems often draw sharp opinions on both sides. Move quickly, work through the numbers, and pressure test the narrative yourself using 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Casella Waste Systems?
Round out your watchlist with a few extra angles that can complement Casella Waste Systems, so you are not relying on a single type of opportunity.
Use the Simply Wall Street Screener to scan other stocks that fit your own criteria and avoid leaving potential ideas on the table.
- Target potential mispricing by reviewing our curated set of 29 high quality undervalued stocks that pair quality fundamentals with discounted market expectations.
- Build a sturdier core to your portfolio by focusing on companies with stronger financial footing through the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known opportunities with robust metrics and growth stories using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com