


EN
3 Oil And Gas Stocks To Watch As Crude Prices Stay Elevated
When missiles start flying near critical facilities like Ras Tanura and Brent trades above $115, every move in integrated oil and gas producers suddenly feels more consequential. Price spikes can reward some businesses and squeeze others, and that gap creates opportunity for investors who pay attention before the crowd. This article walks through 3 stocks from our Global Integrated Oil & Gas Producers screener that are closely tied to these headlines.
The three integrated producers highlighted below are only a first pass. The full screen surfaced 13 more large caps with equally compelling narratives that do not fit into one short article. If you want to move beyond headlines and actually identify which diversified operators align with your own crude price view, head straight to the Global Integrated Oil & Gas Producers screener.
Vallourec (ENXTPA:VK)
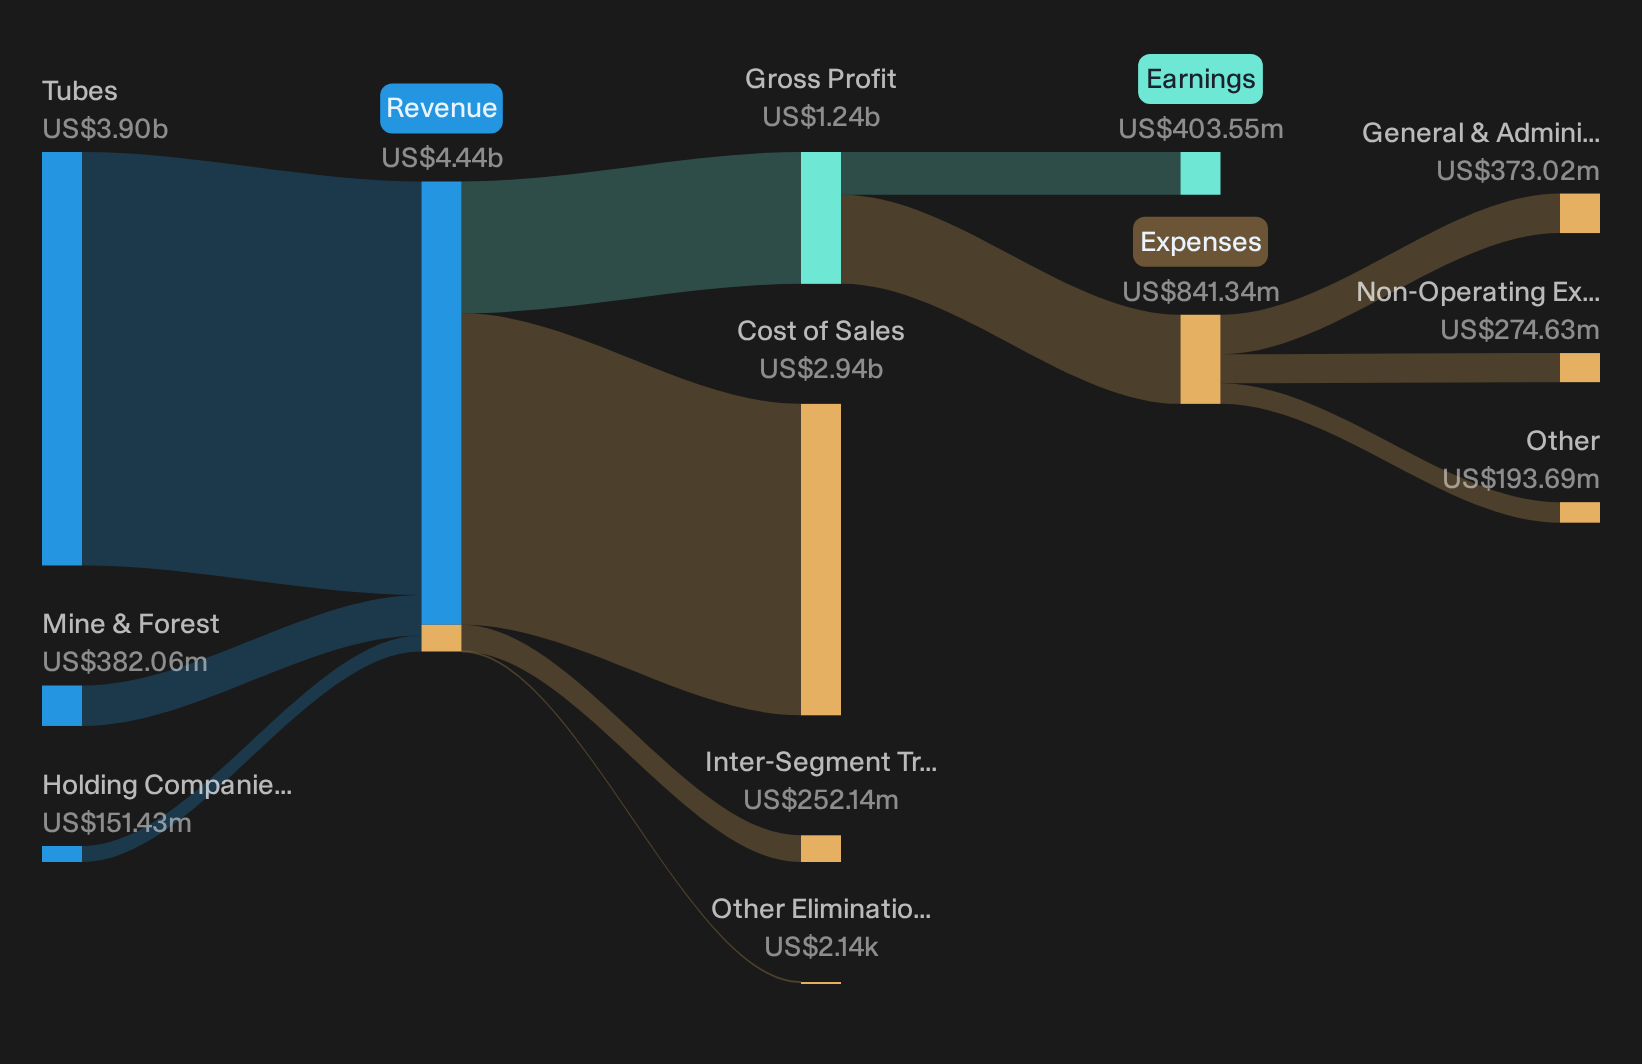
Overview: Vallourec supplies premium steel tubes and related services for oil and gas wells, pipelines and energy infrastructure, giving it leveraged exposure to global drilling and development cycles.
Operations: Vallourec generates about $3.9b from Tubes and $382 million from Mine & Forest, with additional contributions and eliminations bringing reported revenue to roughly $4.2b.
Market Cap: €4.38b
Vallourec matters in this integrated producers screen because its tubular solutions plug directly into the upstream and midstream projects that get greenlit when crude stays expensive and national oil companies push to secure supply.
"Record offshore line pipe awards, including the large ExxonMobil Guyana contract using Proxxima and Goldilocks insulation technology and other projects in Angola and Brazil, position Vallourec to benefit as offshore project approvals from 2026 to 2028 feed into higher thermal insulation demand. This may lift segment revenues and margins when invoicing ramps from late 2026."
The real swing factor is how one less visible cost and pricing pressure shapes Vallourec’s ability to turn that backlog into durable margin strength.
That margin story is only half the picture, and the full narrative for Vallourec explains how pricing power, capital discipline and contract mix could reshape Vallourec’s risk reward profile.
CES Energy Solutions (TSX:CEU)
Overview: CES Energy Solutions supplies specialized drilling fluids, completion chemicals and production additives that oil and gas producers rely on to keep wells flowing efficiently when activity scales up.
Operations: CES Energy Solutions generates about CA$2.7b from oil and gas contract drilling related fluids and chemicals, with revenue split between Canada and the United States.
Market Cap: CA$4.3b
CES Energy Solutions plugs into the Global Integrated Oil & Gas Producers theme as the chemistry behind higher drilling and completion activity when producers respond to stronger crude prices and supply risk headlines.
"The company's ongoing bids for large production chemical contracts, primarily representing new customers, could significantly expand market share and provide higher-margin, recurring revenues. This would enhance both top-line growth and EBITDA margins if awarded."
The real swing factor is how one concentrated shift in customer contract wins or losses eventually filters through to pricing power and margin stability.
That contract swing is exactly where the story starts to accelerate, and the full narrative for CES Energy Solutions explains how CES Energy Solutions’ chemistry, capital choices and customer mix could reshape its risk profile.

Patterson-UTI Energy (PTEN)
Overview: Patterson-UTI Energy runs rigs, frac fleets and drilling tools that sit on the front line of upstream spending when oil prices stay firm.
Operations: Patterson-UTI Energy generates about US$1.5b from Drilling Services, US$2.8b from Completion Services, US$341 million from Drilling Products and US$25 million from Other Operations.
Market Cap: US$4.7b
Patterson-UTI Energy is the pure upstream torque in this integrated producers screen, since its rigs and frac fleets respond directly when exploration and production budgets rise on the back of higher crude and wider risk premia.
"The shift of Patterson-UTI Energy’s frac fleet toward natural gas fueled horsepower, with an expectation that about 90% of active horsepower will be substantially gas powered and more than 15% fully gas powered by the end of 2026, positions the company to operate in a market with tight supply of gas capable fleets and potentially stronger Completion Services pricing and earnings."
What happens to Patterson-UTI Energy’s earnings power depends on how one less visible constraint in that tight frac market finally resolves.
That tight supply story is only half the picture, and the full narrative for Patterson-UTI Energy shows how Patterson-UTI Energy’s earnings power could accelerate if pricing and utilization decouple from past cycles.

Curious To Explore Stronger Alternatives?
New ideas tend to move first. Stocks with real momentum can start advancing before the broader market takes notice. Scan curated themes while the data is still timely and consider positioning early.
- Target reliable cash flows and payout strength with a curated group of income plays using the 224 dividend fortresses.
- Search for potentially mispriced quality in a hand-picked pool of fundamentally strong opportunities via the 195 high quality undervalued stocks.
- Review a focused basket of enablers and suppliers connected to AI infrastructure demand through the 55 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com