


EN
What Investors Overlooked Before Celcomdigi Berhad Slid
If you backed Celcomdigi Berhad on the promise of digital acceleration and 5G-driven gains, the result over the next twelve months was painful. For Celcomdigi Berhad shareholders, the loss over the past year was 28.9%, including dividends. If you made that call based on expectations of rising margins, the latest Q2 2026 numbers tell a different story with a lower net margin. What did the original bullish case miss about how quickly integration, 5G costs, and ARPU pressure might affect the business?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Celcomdigi Berhad. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On Celcomdigi Berhad
The shares cost MYR3.64 at the start, and Celcomdigi Berhad sat between two sharply different stories about what came next.
On the optimistic side, the bullish narrative put fair value at MYR5.6, assuming deep integration and modernization would drive cost efficiency and sustained margin expansion as Malaysia's most modern network.
The bearish view pointed to a MYR3.03 fair value, focusing on over the top platforms eating into voice and SMS revenue and elevated debt constraining financial flexibility.
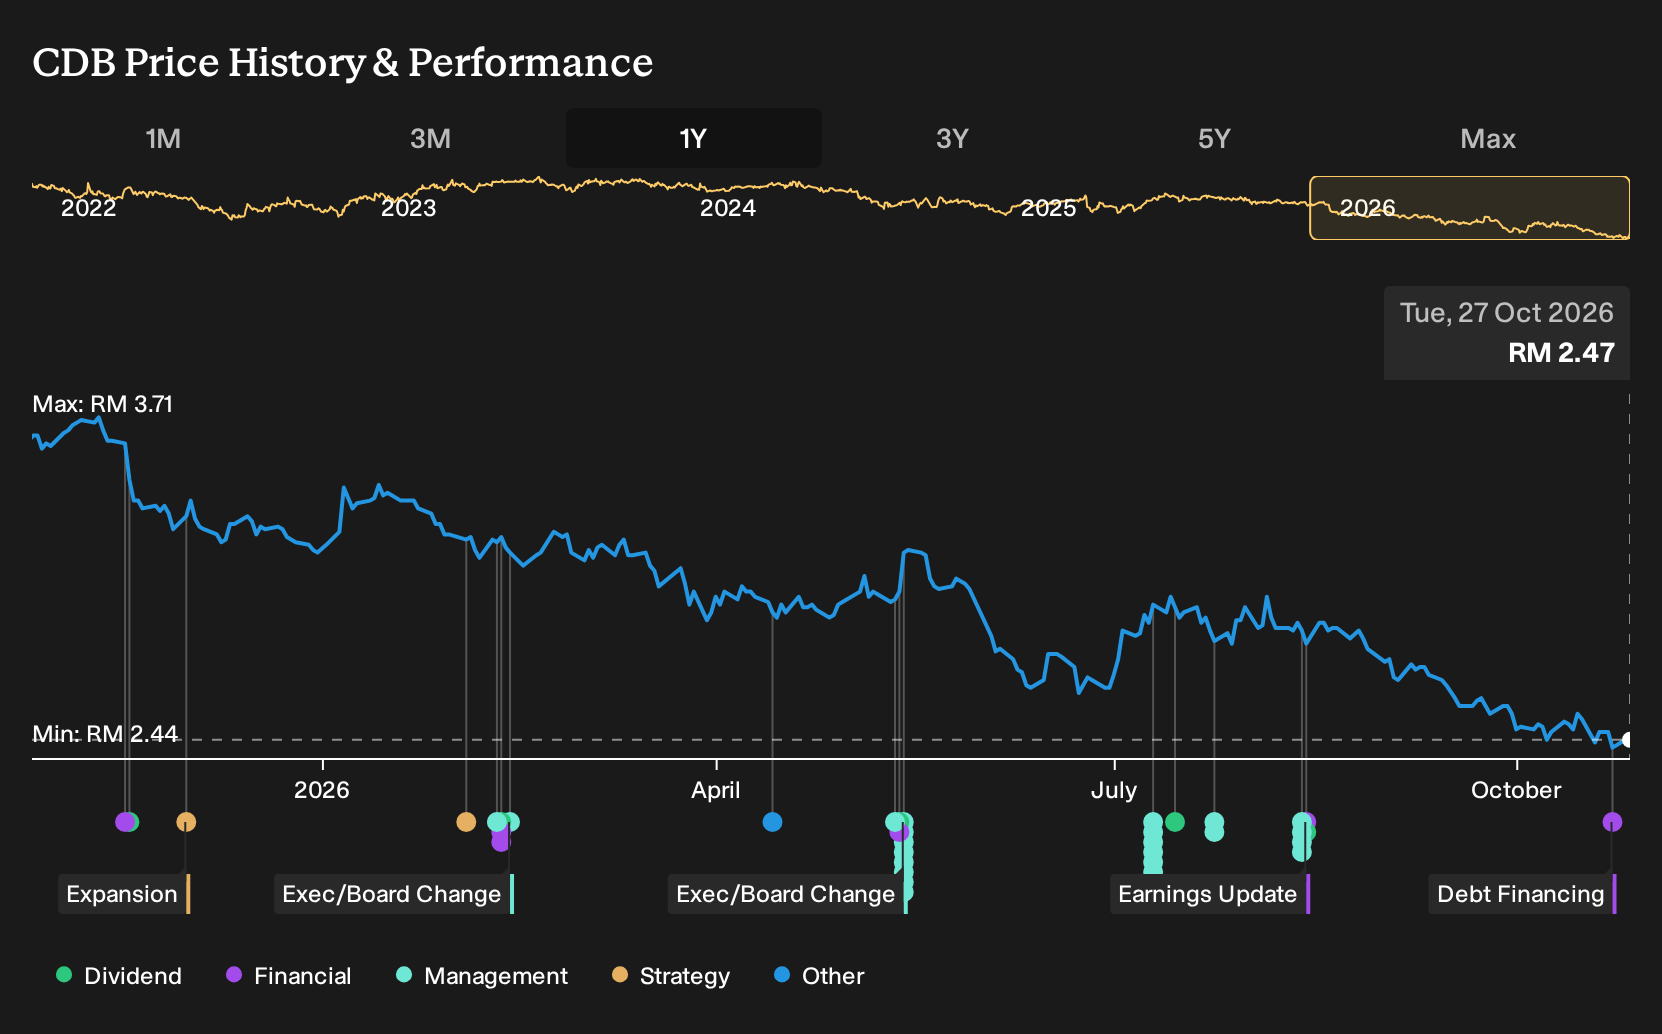
What The Results Changed For Celcomdigi Berhad
The clearest datapoint is Q2 2026. Celcomdigi Berhad reported revenue of MYR3,217m versus MYR3,197m a year earlier, while net income slipped from MYR439m to MYR398m and net margin moved from 13.7% to 12.4%. That mix of slightly higher sales and softer profitability challenged the more optimistic case built on sustained margin expansion.
The episode turned on one simple assumption. Expected efficiency gains needed to show up in a rising margin. When you look at another telecom stock, track whether margin trends confirm any cost-saving story or simply leave you paying up for flat profitability.
What You Would Be Paying For In Celcomdigi Berhad Today
With Celcomdigi Berhad now at MYR2.47 after a 28.9% share price decline over the past year, the selected Narrative's Fair Value sits above the current price based on its own framework. That view leans heavily on network integration, modernization and cost synergies supporting the investment case.
The distinctive pitch is that efficiency gains, value added services and future earnings resilience could matter more than the recent setback. For the fall to look like an opening rather than a warning, a buyer would need to believe integration risks ease and monetization of new services supports the long term thesis.
"Key Takeaways: Network integration and modernization enhance efficiency and service quality, driving revenue growth and improved margins. Cost synergies and value-added services boost profitability and sustain future earnings growth."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Celcomdigi’s Story Connects Sideways
Celcomdigi’s setback leaves you asking where the telecom story still runs hot.
One step away from Malaysia, another operator is leaning into broadband and 5G capacity. It is wiring homes and offices with fixed wireless access and fiber connections.
That same business is also chasing long term enterprise links. Think private networks and AI focused connectivity contracts that need reliable bandwidth, not headline subscriber wins.
If those customers keep demanding heavier data and lower churn, another telecom balance sheet may be doing the heavy lifting you wanted from Celcomdigi.
That argument has a Narrative and a number behind it. → See the company one Narrative values 17% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com