


EN
Revenue And Profit Decline Altering The Investment Case For China Mobile (SEHK:941)?
- China Mobile reported earnings for the nine months to September 30, 2026, with sales of CNY 780,295 million and net income of CNY 106,198 million, both lower than the same period a year earlier, alongside reduced basic and diluted earnings per share from continuing operations.
- The simultaneous decline in revenue and profit points to pressure on China Mobile's core telecom operations and raises questions about how effectively newer digital and AI services are offsetting softness in traditional connectivity lines.
- We will now look at how China Mobile's softer nine month earnings performance could reshape the investment narrative that investors have been using.
Compare China Mobile's earnings pressure with other large telecom and infrastructure plays by scanning our hand picked 42 power grid technology and infrastructure stocks that may be facing similar revenue and profit questions.
China Mobile Investment Narrative Recap
To own China Mobile, you need to be comfortable with a mature telecom engine that is trying to grow newer digital, cloud and AI services fast enough to offset softer traditional connectivity. The latest nine month results, with revenue and net income both lower than a year ago, reinforce how tight that balance is.
In the near term, the key swing factor is whether digital transformation and AI products can contribute enough higher margin business to stabilise earnings while investment stays heavy. The biggest risk is that saturated demand, pricing pressure and ongoing capex keep squeezing margins, which could limit flexibility around future spending and dividends.
The earnings announcement for the nine months to September 30, 2026 is the clearest reference point for that risk reward trade off right now. China Mobile reported CNY 780,295 million in sales and CNY 106,198 million in net income, with both figures below the prior period, and earnings per share also lower on both a basic and diluted basis.
For you as a shareholder, that creates a very practical checklist. Monitor how quickly cloud, data center and AI services scale relative to the pressure in legacy telecom. Track whether net profit trends start to stabilise, and keep an eye on dividend coverage given earlier commentary that the 6.75% yield is not well covered by earnings.
China Mobile is currently modeled by analysts to reach revenue of CNY 1,087.8b and earnings of CNY 142.1b by 2029, based on expectations for about 1.4% yearly top line growth and an increase in profit from CNY 131.8b today. This implies an earnings increase of roughly CNY 10.3b over that period.
Uncover why China Mobile's fair value indicates a 21% potential upside to its current price that could narrow quickly.
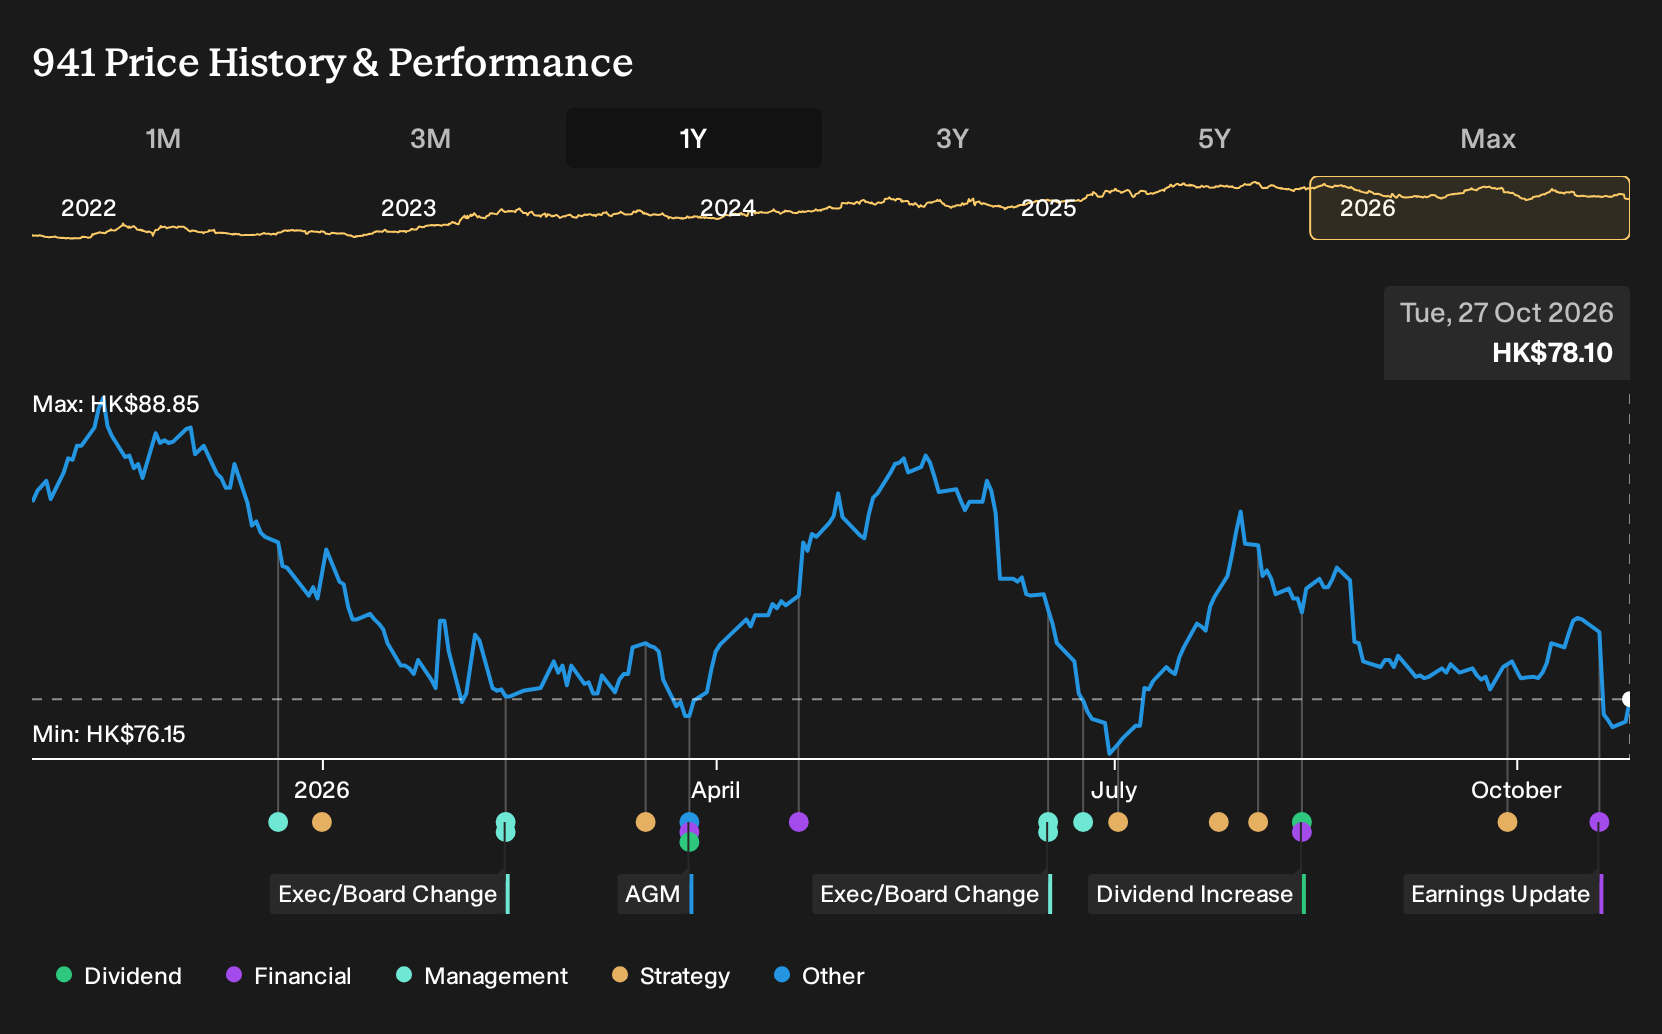
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly CNY 94.53 to CNY 207.20, so some retail investors see China Mobile as close to fully priced while others expect much richer pricing. Set that against earnings pressure, heavy capex and rising digital bets, and you get sharply different conclusions. Explore those viewpoints before deciding where you stand.
Explore 3 other China Mobile fair value estimates, including one that suggests it could be worth just HK$94.53!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your China Mobile research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for China Mobile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate China Mobile's overall financial health at a glance.
Looking For More Investment Ideas Beyond China Mobile?
If China Mobile's mixed earnings picture has you rethinking concentration risk, it can help to widen the search and compare it with other businesses that fit different profiles on value, balance sheet strength and income potential.
- For investors who want potential upside with a valuation cushion, scan a curated 195 high quality undervalued stocks that combine quality fundamentals with pricing that still looks conservative.
- If capital preservation and financial resilience sit at the top of your list, filter for companies on our 223 resilient stocks with low risk scores that show stronger risk scores and sturdier fundamentals.
- Income focused investors can broaden beyond China Mobile's yield by checking out a hand picked set of 224 dividend fortresses that aim to pair higher payouts with business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com