


EN
What ABB Holders Bought Into
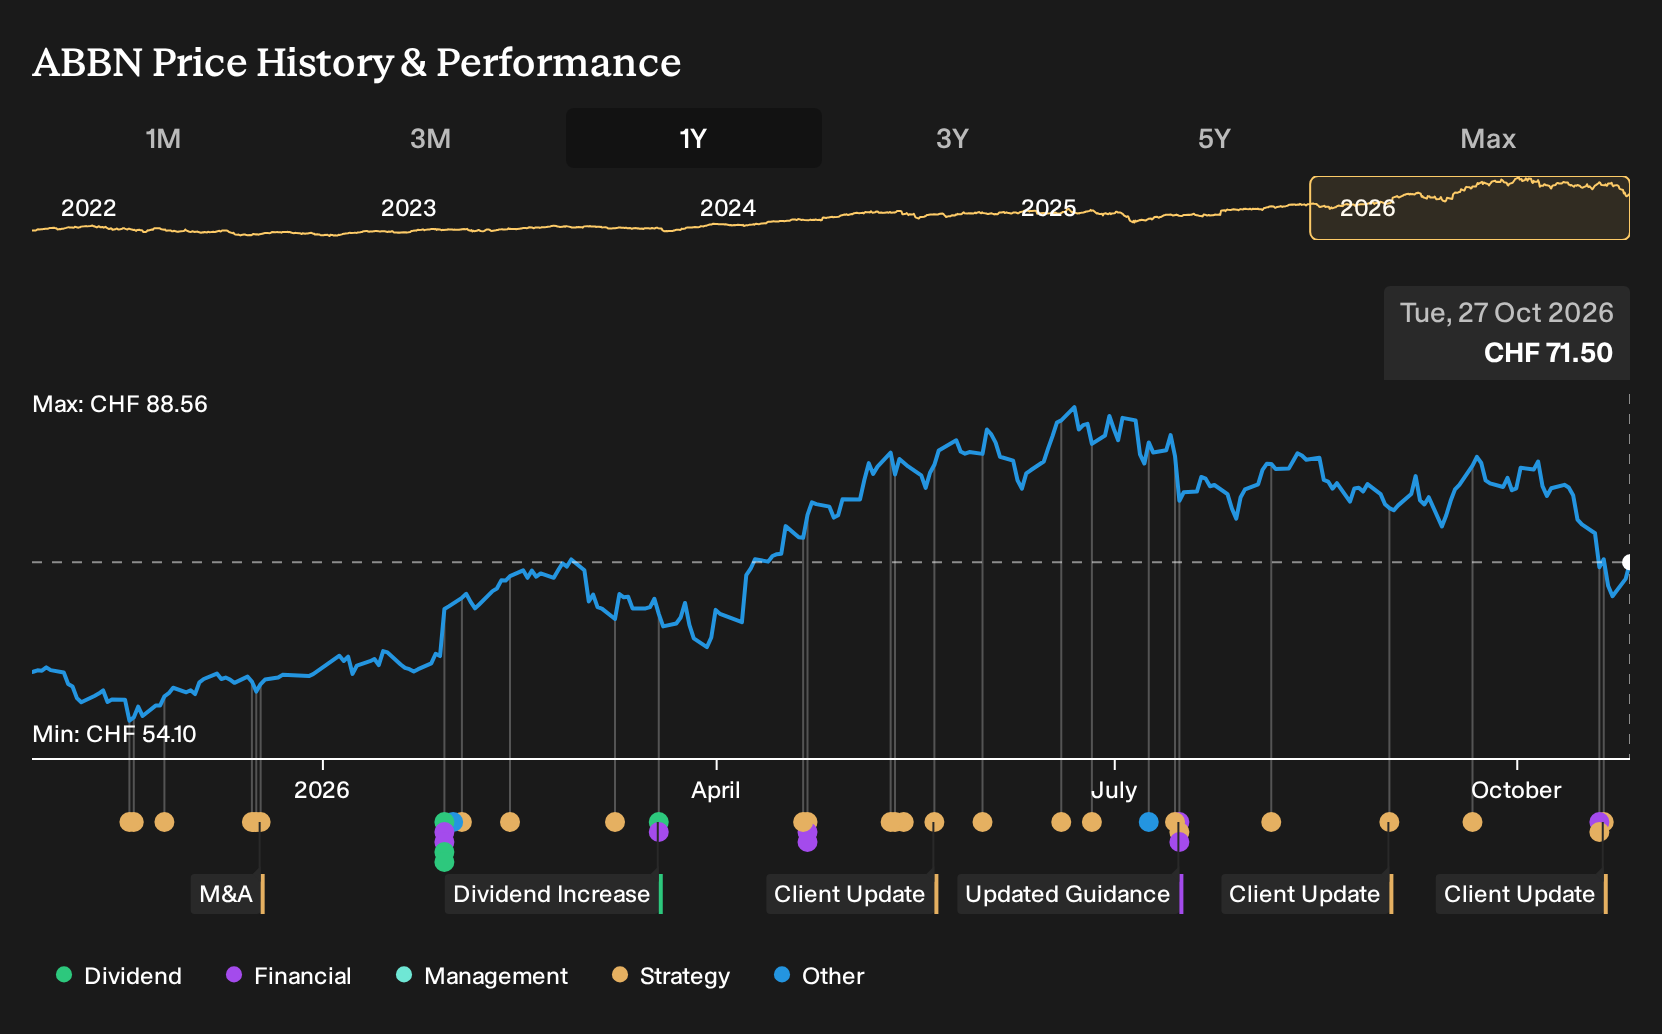
ABB’s year was packed with concrete moves, from the agreed Rotork takeover to fresh AI data center products and a joint venture with Mitsubishi Electric in Asia. For ABB shareholders, the return over the past year was 21.7%, including dividends. If you were deciding whether to buy on 27 October 2025, you had to judge those early electrification, automation and spin-off stories and then ask whether the later surge in orders and acquisitions was already implied or still a stretch.
ABB is not the only name tied to this theme. Zero in on 42 power grid technology and infrastructure stocks and compare how each one is priced.
The Argument ABB Investors Were Really Weighing
The shares cost CHF59.48 at the start of the period, and anyone looking at ABB then had to decide which story about its future sounded more realistic.
The bullish narrative saw Electrification and Robotics as a launchpad, with a Fair Value of CHF62.63. This represented a price level implied by expectations for faster electrification orders and a richer mix of digital services boosting net margins.
The more cautious view put Fair Value at CHF51.11 and treated ABB's exposure to weaker automotive, Chinese construction, and industrial markets as a real threat to future earnings stability.
What The ABB Evidence Actually Showed
ABB’s Q3 2026 report gave investors harder numbers than any narrative. Revenue reached US$9,701m compared with US$8,491m a year earlier and net income also rose, while net margin slipped from 13.8% to 12.6%. That mix, higher sales and profit but a thinner margin, gave partial backing to the optimistic growth story and still left the stronger margin assumptions in both cases unproven.
The episode hinged on one question: Could ABB grow and keep profitability moving the way both camps expected? When you judge another industrial stock, test that same claim directly against reported revenue, absolute earnings, and the trend in net margin, not just management commentary or headlines.
What ABB’s Up 22% Run Now Prices In
ABB shares now trade at CHF71.5, with the selected cautious Narrative arguing that its Fair Value sits below that level despite the strong one-year gain.
The Narrative leans on ABB’s long shift toward software-rich electrification and automation, so a buyer today effectively assumes that this architecture keeps earning its way into more facilities worldwide. The question is how that assumption lines up with the specific execution risks and valuation stretch flagged in the Narrative.
"Across these decades, ABB’s recurring strategic question has been: Which businesses strengthen its ability to make customers’ industrial assets operate better together? The answer has changed with technology, markets and management. Some acquisitions expanded that capability; some disposals released capital or reduced complexity; others corrected earlier mistakes."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
ABB And The Digital Plumbing Question
ABB’s hardware and automation ambitions depend on something simpler. All that data still needs to move reliably.
Across factories, grids and data centers, performance now hinges on fast, predictable connectivity. You can think of it as digital plumbing.
Another business focuses on that plumbing, building chips and software that help move, manage and secure information inside big computing systems.
It is not tied to one AI model or data center owner. Its role is keeping traffic flowing regardless of who wins on top.
If you are tracking ABB’s world, this other layer may quietly shape where value pools form next.
The case is written up, with the assumptions it depends on. → Discover the AI infrastructure company one Narrative values 90% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com