


EN
Higher Earnings Could Be A Game Changer For Trelleborg Stock (OM:TREL B)
- Trelleborg reported past third quarter 2026 sales of SEK 9,232 million and net income of SEK 1,094 million, with basic earnings per share from continuing operations of SEK 4.92.
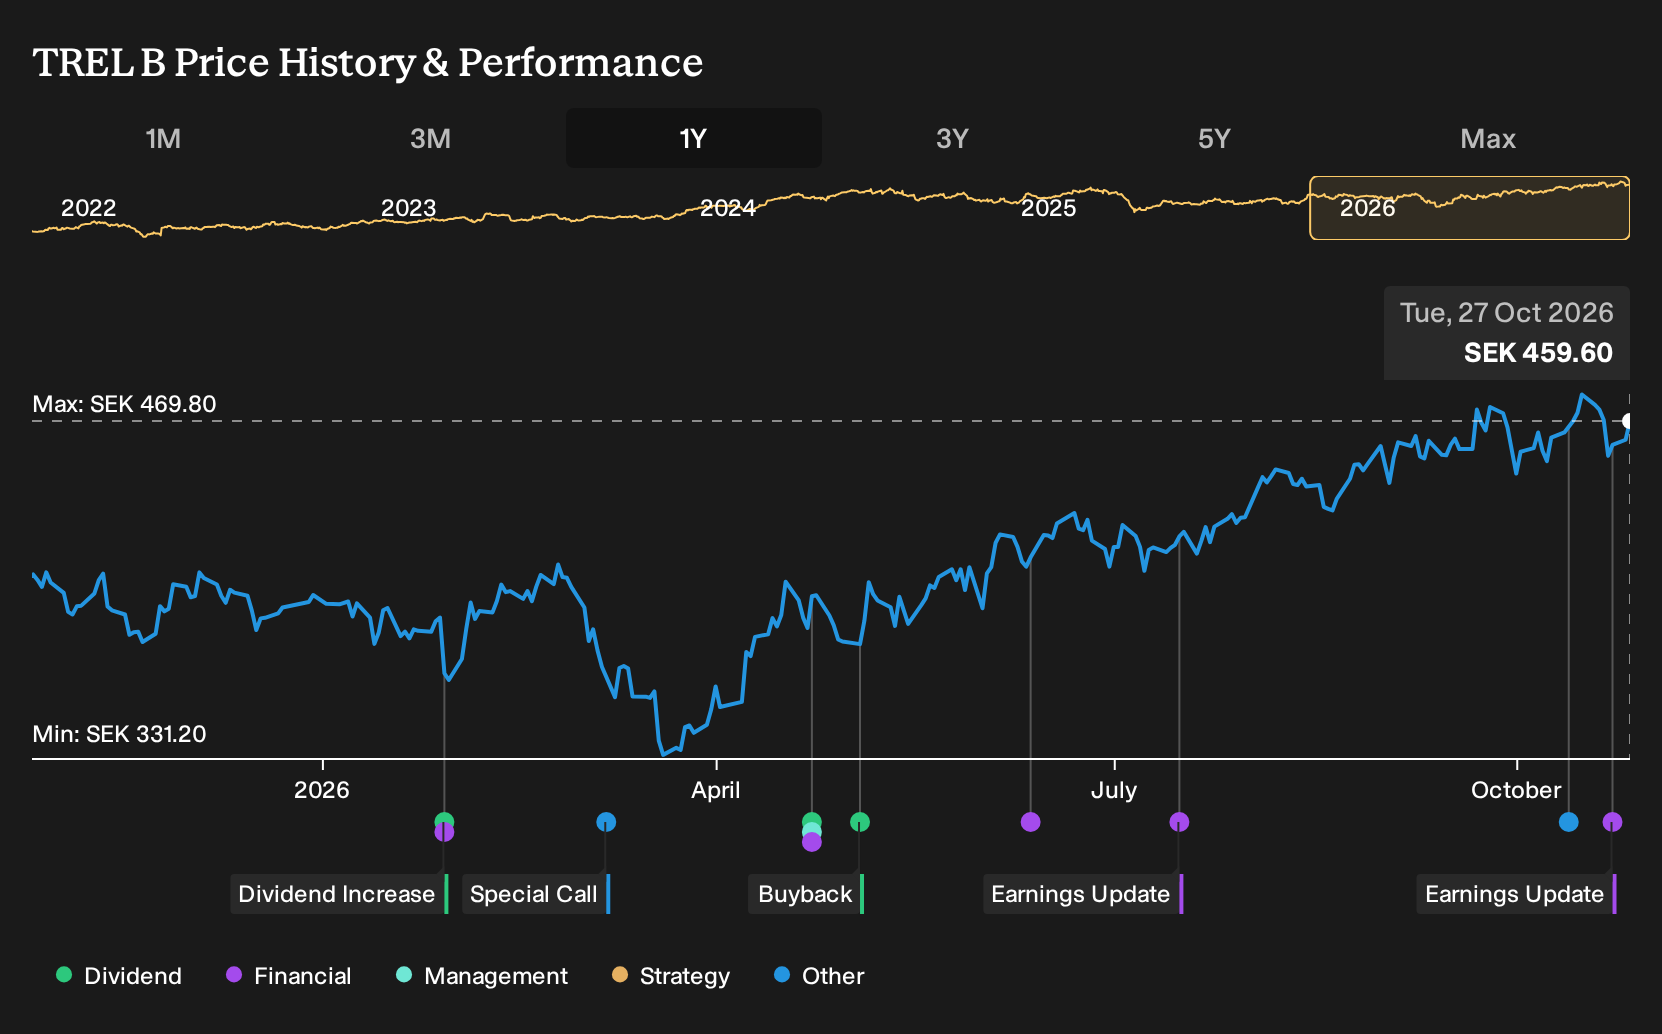
- Alongside these results, Trelleborg completed a buyback of 2,144,272 shares for SEK 895.87 million, which reduces the share count and concentrates earnings per share among remaining holders.
- We will now look at how Trelleborg's stronger earnings per share profile may influence the investment narrative investors rely on.
Scan how Trelleborg's latest buyback and earnings story compares with other companies by reviewing a curated mix of 195 high quality undervalued stocks that also pair solid balance sheets with proven cash generation.
Trelleborg Investment Narrative Recap
Trelleborg stock asks investors to have confidence in a polymer specialist that can keep shifting its mix toward higher specification sealing, medical and infrastructure work while still managing weak spots such as autos and project timing. The latest quarter shows the business generating higher sales and earnings, which supports that case but does not remove execution risk in Medical Solutions or acquired units.
The most important near term swing factor is whether higher margin segments can offset pressure in more cyclical end markets. The biggest risk remains that integration drag and softer automotive volumes could limit further margin progress, so the third quarter strength helps sentiment without fundamentally changing the key questions around resilience and order volatility.
The fresh third quarter 2026 results are the announcement that matters most. Sales reached SEK 9,232 million and net income was SEK 1,094 million, with basic earnings per share from continuing operations at SEK 4.92. For the first nine months, earnings per share from continuing operations were SEK 14.12, giving investors more data on how Trelleborg is converting revenue into profit.
Those figures feed directly into the catalyst debate around mix improvement and margin consistency. Solid earnings provide support for ongoing investment in aerospace, semiconductor and medical applications and for funding acquisitions, but they also raise the bar for sustaining progress if auto related demand remains soft or integration in Sealing Solutions and Medical Solutions takes longer than investors currently assume.
Trelleborg's narrative references forecasts for SEK 44.1b in revenue and SEK 6.0b in earnings by 2029. This implies 8.3% yearly revenue growth and an earnings increase of about SEK 2.2b from SEK 3.8b today.
Uncover why Trelleborg's fair value points to a valuation that is consistent with its current price.
Exploring Other Perspectives
You see the buyback as a signal of confidence. The most pessimistic Trelleborg analysts focus on a different point. They worry higher CapEx in 2026 could drag on returns, even though they were still pencilling in about SEK 42.7b of revenue and roughly SEK 5.8b of earnings by 2029 before this news.
Explore 2 other Trelleborg fair value estimates, including one that suggests it could be worth just SEK467.64.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis.
- A great starting point for your Trelleborg research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Trelleborg. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Trelleborg's overall financial profile at a glance.
Looking for more Trelleborg sized investment ideas?
If the Trelleborg story has sharpened your thinking, use that same framework on a broader watchlist by running a few focused screens on the Simply Wall St Screener.
- For investors who want potential upside with tighter risk controls, review a group of 223 resilient stocks with low risk scores that pair more resilient business profiles with measured volatility.
- If balance sheet strength is your first filter, scan a list of solid balance sheet and fundamentals (207 results) where debt levels and liquidity help support longer holding periods.
- If you prefer to fish where fewer people are looking and still care about fundamentals, then check a set of 610 high quality undiscovered gems that combine quality metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com