


EN
Learn Why The Bull Case For SoftBank Group Stock Could Change Following Anthropic IPO Filing
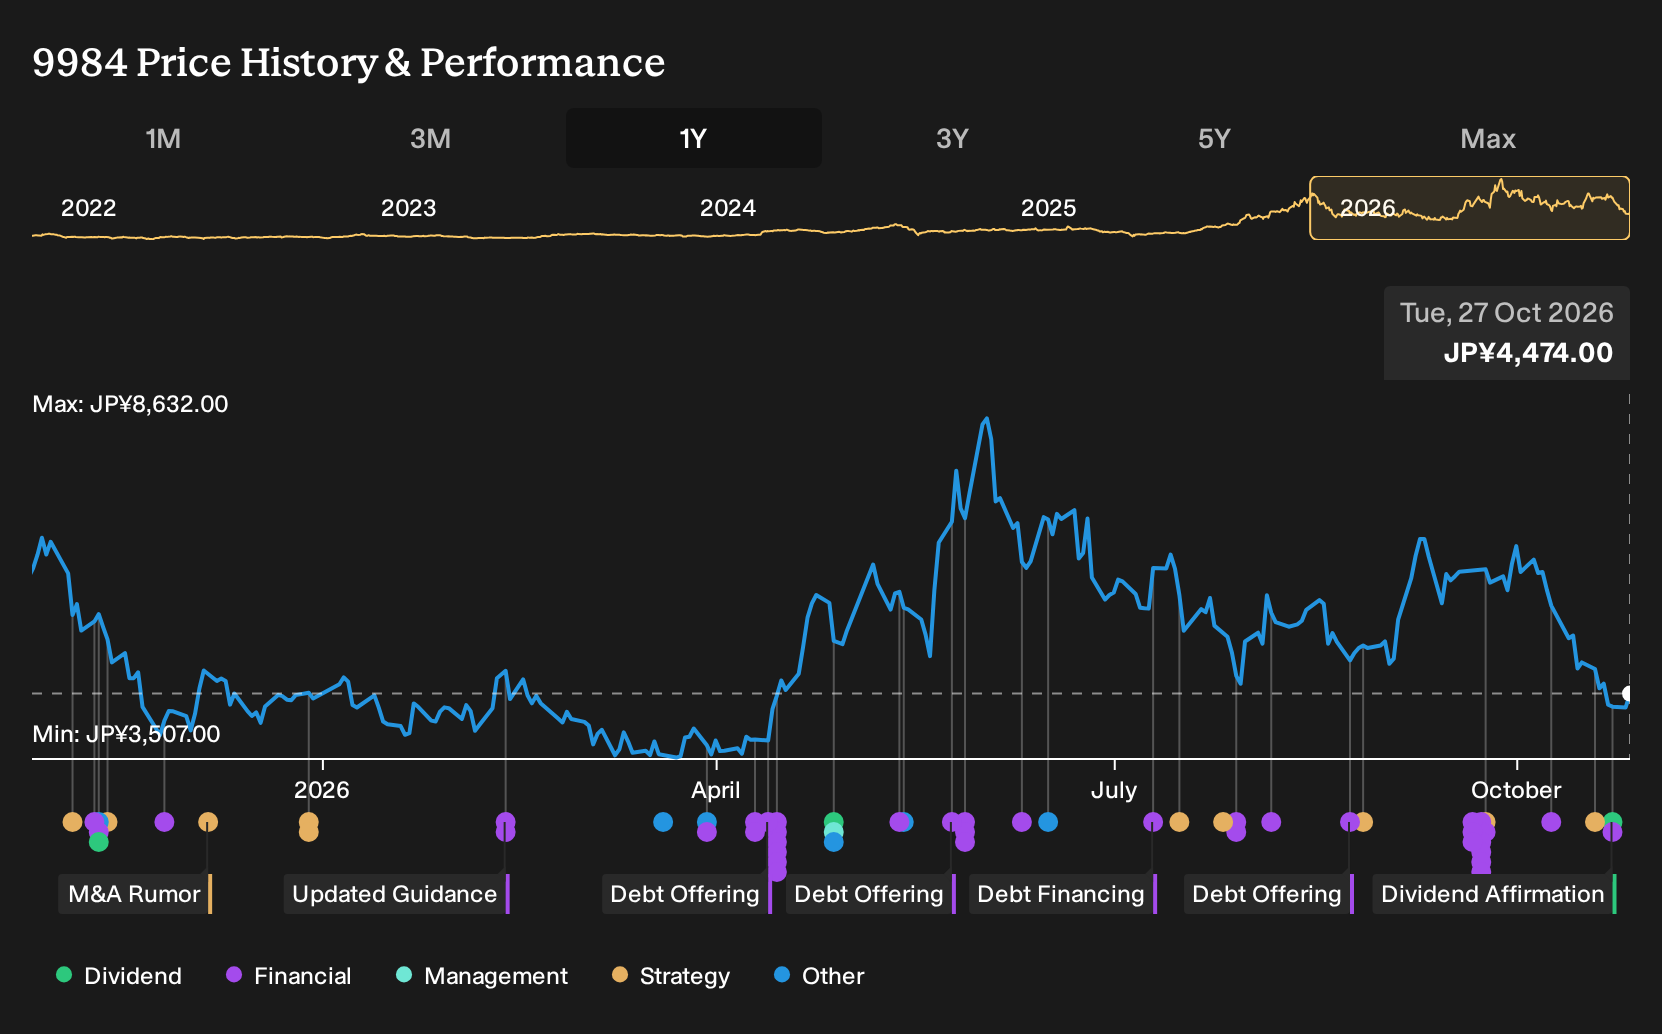
- SoftBank Group confirmed an interim dividend of ¥5.50 per share from retained earnings and fully redeemed its euro-denominated 2.875% senior notes due 2027, while reports suggest it is in early talks to acquire Allied Universal for up to US$18 billion and is exploring a US$50 billion AI and data center plan in Malaysia.
- The mix of lower interim dividends after a prior share split, debt redemption, large potential M&A and sizeable AI infrastructure ambitions shows SoftBank Group actively reallocating capital between income to shareholders, balance sheet flexibility and long-term AI-related operating exposure.
- We will look at how SoftBank Group's investment narrative is shaped by the Anthropic IPO link and the Malaysia AI expansion plan.
SoftBank Group Investment Narrative Recap
Owning SoftBank Group means buying into an investment holding company that is leaning hard into AI infrastructure while carrying sizeable debt and relatively volatile earnings. The big short term swing factor is whether key AI exposed assets and projects keep moving toward commercialization without significant delays. The largest current risk is funding, given that debt is not well covered by operating cash flow.
The latest dividend affirmation at ¥5.50 per share, alongside early redemption of euro senior notes, slightly clarifies the near term cash out profile but does not fundamentally change that core risk reward equation. Potential Anthropic IPO proceeds and planned data center projects remain the important operational levers investors will watch.
The early redemption of the euro denominated 2.875% senior notes due 2027 is the announcement that ties most closely to the current story. Retiring this debt removes a future maturity and interest line and provides a slightly clearer view of how SoftBank Group is aligning its balance sheet with approximately US$65b of AI oriented commitments.
This move matters because the funding side is the pressure point for many of the major AI catalysts, from SB Energy’s planned Nasdaq listing to the large data center build out in France and the discussed US$50b Malaysia plan. Execution now depends less on single bonds and more on access to new credit and equity events, including Anthropic’s IPO filing.
SoftBank Group's current analyst storyline points to revenues of ¥10,084.0 billion and earnings of ¥757.4 billion by 2029, based on forecasts that assume revenue grows by 8.0% a year and earnings move down from ¥4,908.4 billion today, a decline of roughly ¥4,151.0 billion over that period.
Uncover how SoftBank Group's fair value indicates a 74% potential upside to its current price that could narrow quickly if sentiment around SoftBank Group shifts.
Exploring Other Perspectives
One alternate angle on SoftBank Group focuses less on dividend cuts and debt redemption and more on the bullish AI story. The most optimistic analysts were already assuming revenue of about ¥11,610.7 billion and earnings near ¥739.6 billion by 2029. That view is far more upbeat, and the latest dividend and financing news could eventually shift both narratives.
Explore 4 other SoftBank Group fair value estimates, including one that suggests up to 148% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SoftBank Group research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SoftBank Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SoftBank Group's overall financial health at a glance.
Looking for more investment ideas beyond SoftBank Group?
If the SoftBank Group story has sharpened your thinking about risk, income and AI exposure, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who care about both value and quality, compare SoftBank Group with a curated list of 16 high quality undervalued stocks that pair stronger fundamentals with attractive pricing.
- If capital protection matters as much as upside, weigh SoftBank Group against 22 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
- For readers hunting for fresher stories, set SoftBank Group alongside 72 high quality undiscovered gems that combine solid metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com