


EN
Is Bumitama Agri (SGX:P8Z) Fully Valued As Haze Act Scrutiny Clouds The Outlook?
Bumitama Agri (SGX:P8Z) told investors it received a request from Singapore’s National Environment Agency on 23 October 2026 for documents under the Transboundary Haze Pollution Act, bringing regulatory compliance into sharper focus.
Short term, Bumitama Agri’s share price has been under pressure, with the 30 day share price return down 24.07% and the 7 day move also lower, even though the year to date share price return of 21.48% and 1 year total shareholder return of 25.40% still point to stronger longer term momentum.
Spot other agriculture and commodity players facing similar regulatory or sentiment shifts by scanning our curated list of 223 resilient stocks with low risk scores.Bulls see Bumitama Agri’s past returns and current discount as an opening, while bears focus on regulatory risk and the recent sell off. Which side does the valuation actually support next?
Preferred P/E of 12x for Bumitama Agri: Is it justified?
Bumitama Agri trades on a P/E of 12x, which looks expensive next to its own fair P/E estimate but cheaper than the wider Asian food peer group.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors are paying for each dollar of profit. For a palm oil producer with a clear profit track record and exposure to commodity and regulatory swings, that yardstick can matter more than pure revenue multiples.
Here, the market is paying 12x earnings while the estimated fair P/E sits lower at 9.7x. That gap suggests investors are attaching a higher price to Bumitama Agri’s earnings stream than the fair ratio implies, even though the group is trading below the Asian food industry average of 14.4x. The fair ratio points to a level the valuation could migrate toward if sentiment around earnings quality, regulatory risk and growth expectations stabilises.
Explore the SWS fair ratio for Bumitama Agri.
Result: Price-to-earnings of 12x (OVERVALUED)
Still, the Transboundary Haze Pollution Act document request and any shift in investor confidence around Bumitama Agri’s regulatory profile could quickly challenge today’s richer P/E story.
Find out about the key risks to this Bumitama Agri narrative.
Another View: SWS DCF says Bumitama Agri looks cheap
The P/E lens flags Bumitama Agri as rich, yet the SWS DCF model paints a different picture. With the share price at SGD1.64 and the estimated future cash flow value at SGD3.96, the stock comes through as undervalued on this framework. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
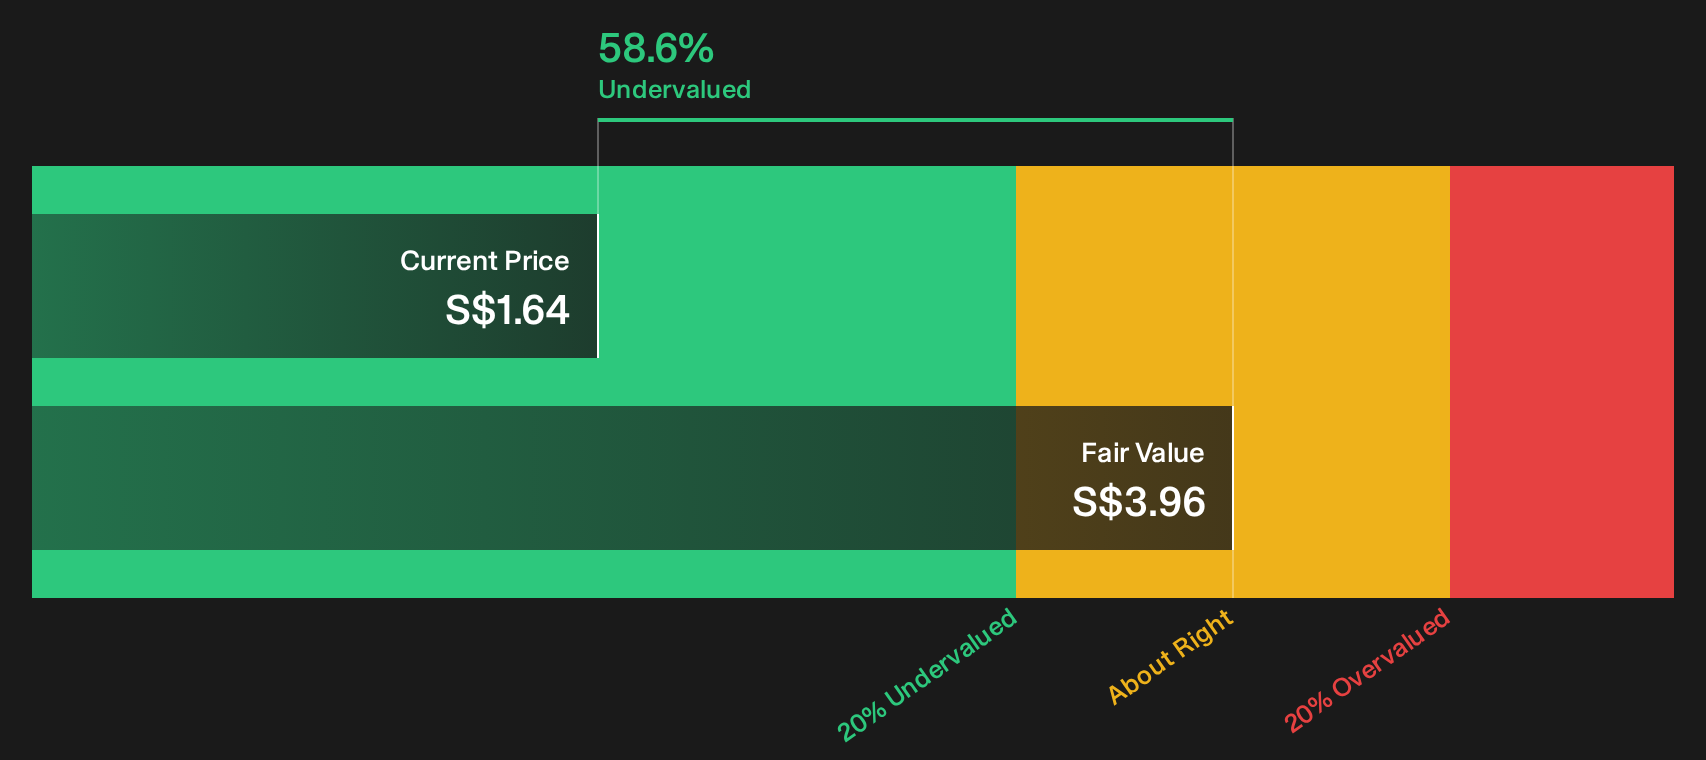
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bumitama Agri for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these tend to split opinion, so if Bumitama Agri is on your radar, move quickly, pull up the full data set, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bumitama Agri?
If Bumitama Agri has your attention, do not stop here. Cast a wider net and let a focused stock list surface ideas you might otherwise overlook.
- Target potential bargains before the crowd by scanning the 195 high quality undervalued stocks that combine quality fundamentals with pricing that still looks out of sync.
- Strengthen your income plan by reviewing the 224 dividend fortresses that offer higher yields with frameworks built to highlight staying power.
- Protect your downside first by filtering for the list of solid balance sheet and fundamentals (207 results) so you can focus on businesses with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com