


EN
Return To Profit Might Change The Case For Investing In BXP (BXP)
- BXP, Inc. reported third quarter 2026 revenue of US$911.43 million and net income of US$114.48 million, compared with a loss in the same period last year.
- Across the first nine months of 2026, BXP moved from US$28.45 million in net income a year ago to US$284.61 million, indicating an earnings turnaround.
- The focus now is on how BXP's return to profitability could influence its existing investment narrative and investor expectations.
Compare BXP's earnings rebound with hand-picked real estate peers by scanning our list of solid balance sheet and fundamentals (24 results).
BXP Investment Narrative Recap
BXP shareholders effectively need to believe that demand for premier workplaces in its key cities holds up, and that occupancy and rents can support the current development pipeline. The latest quarter, with US$911.43 million in revenue and US$114.48 million in net income, reinforces that the business is operating profitably again, which supports the near term story.
The more immediate swing factor remains how income trends compare with rising interest expense and any dilutive asset sales. Higher debt costs and interest coverage that is not strong are still the key operational risk. The earnings rebound is helpful, but does not remove that financing pressure.
The most relevant update is the nine month earnings picture. BXP reported US$2.68 billion in revenue and US$284.61 million in net income for that period, compared with US$28.45 million in profit a year earlier. That scale of improvement, even with one off items in the past, underpins the idea that the turnaround is showing up in the income statement.
For catalysts, that stronger profit base gives BXP more room to progress capital recycling, fund its development projects and work through upcoming refinancings. The risk side is that interest payments are still not comfortably covered by earnings, so any slowdown in leasing or cash flow, or further dilutive dispositions, would matter more than usual over the next couple of years.
What The BXP Forecasts Assume
BXP's narrative projects US$3.8b revenue and US$345.9 million earnings by 2029. This is consistent with analyst assumptions of 6.2% yearly revenue growth and about a US$49 million earnings increase from the US$296.8 million of earnings today.
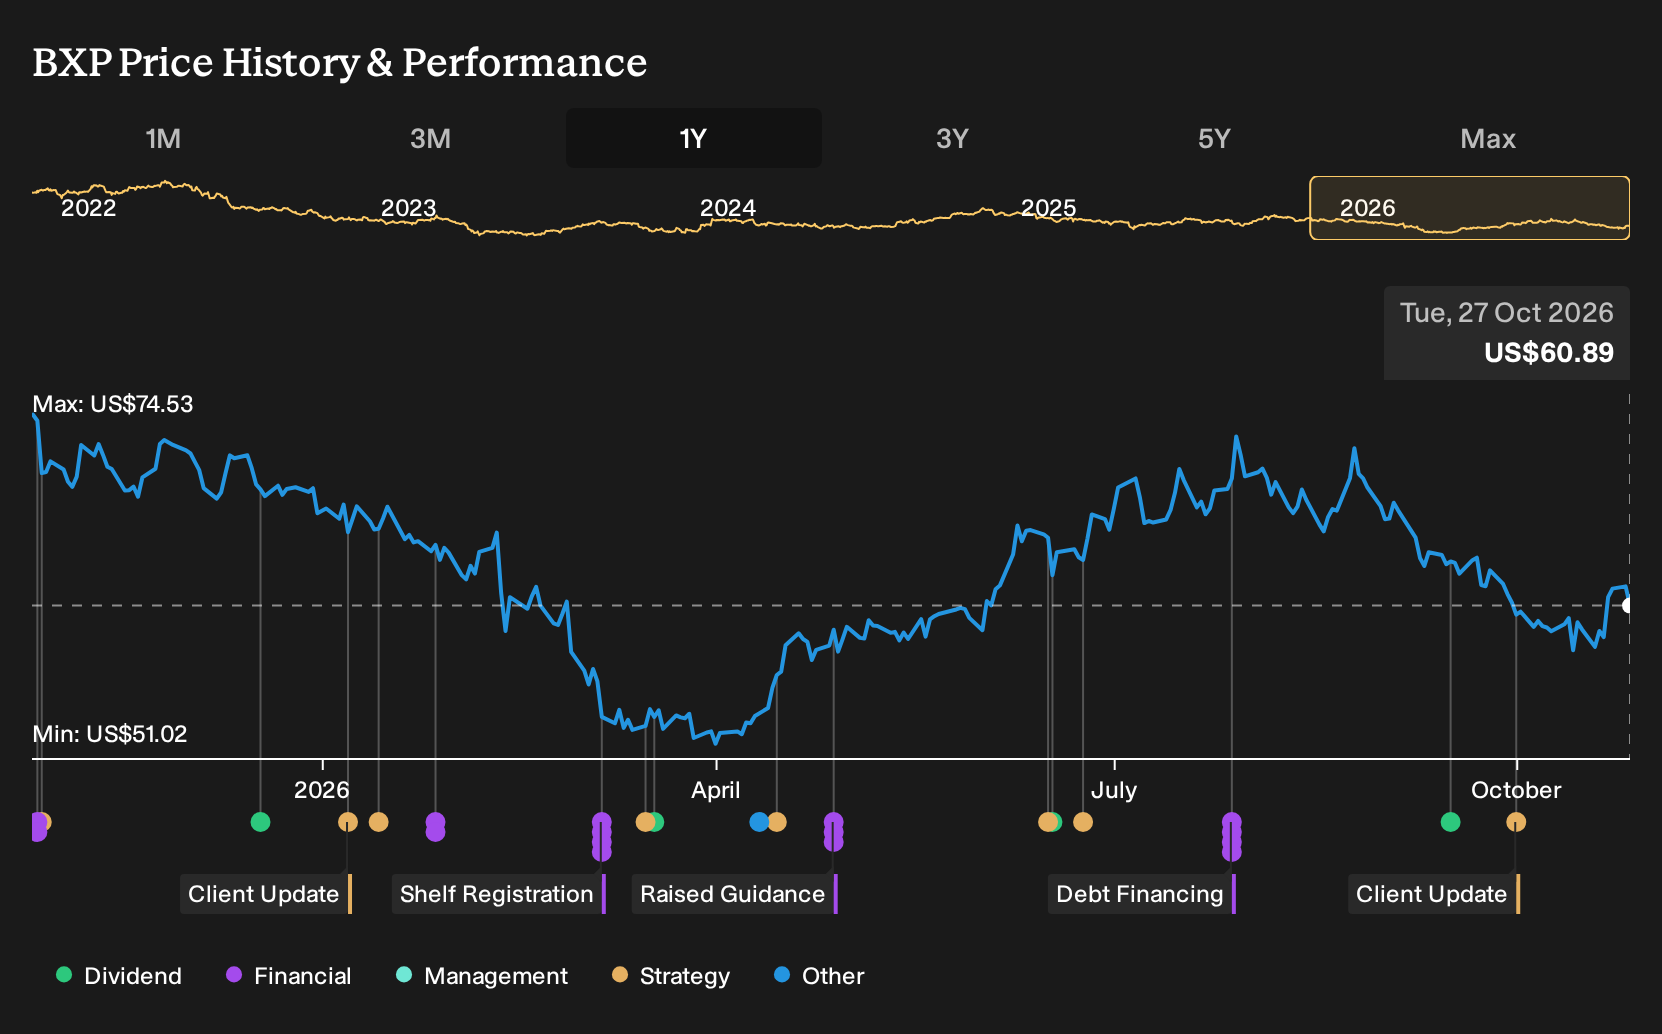
Uncover how BXP's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You now have BXP printing a quarterly profit, yet the most pessimistic analysts were still pencilling in only about US$3.8b of revenue and roughly US$290.9 million of earnings by 2029. That more cautious story leans on margin pressure. Use this earnings surprise as a prompt to compare those forecasts and stress test your own view.
Explore 3 other BXP fair value estimates, including one that suggests it could be worth just $73.30!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BXP research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BXP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BXP's overall financial health at a glance.
Looking For More Ideas Beyond BXP?
If BXP's earnings turnaround has you rethinking where you want real estate exposure, it can help to line it up against other stocks that fit specific qualities on your watchlist. The Simply Wall St Screener gives you a quick way to filter for different traits, then compare fundamentals side by side.
- For investors who want potential upside with a smaller starting price tag, consider using the screener to surface 7 elite penny stocks with strong financials that still show solid underlying metrics.
- If quality at a reasonable price is the priority, focus your search on companies flagged in our 29 high quality undervalued stocks that pair strong fundamentals with more modest valuations.
- Income focused readers can zero in on stronger yield opportunities by filtering for 5 dividend fortresses that combine higher payouts with underlying financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com