


EN
Dividend Increase Approved Is Altering The Investment Case For Dormakaba Shares
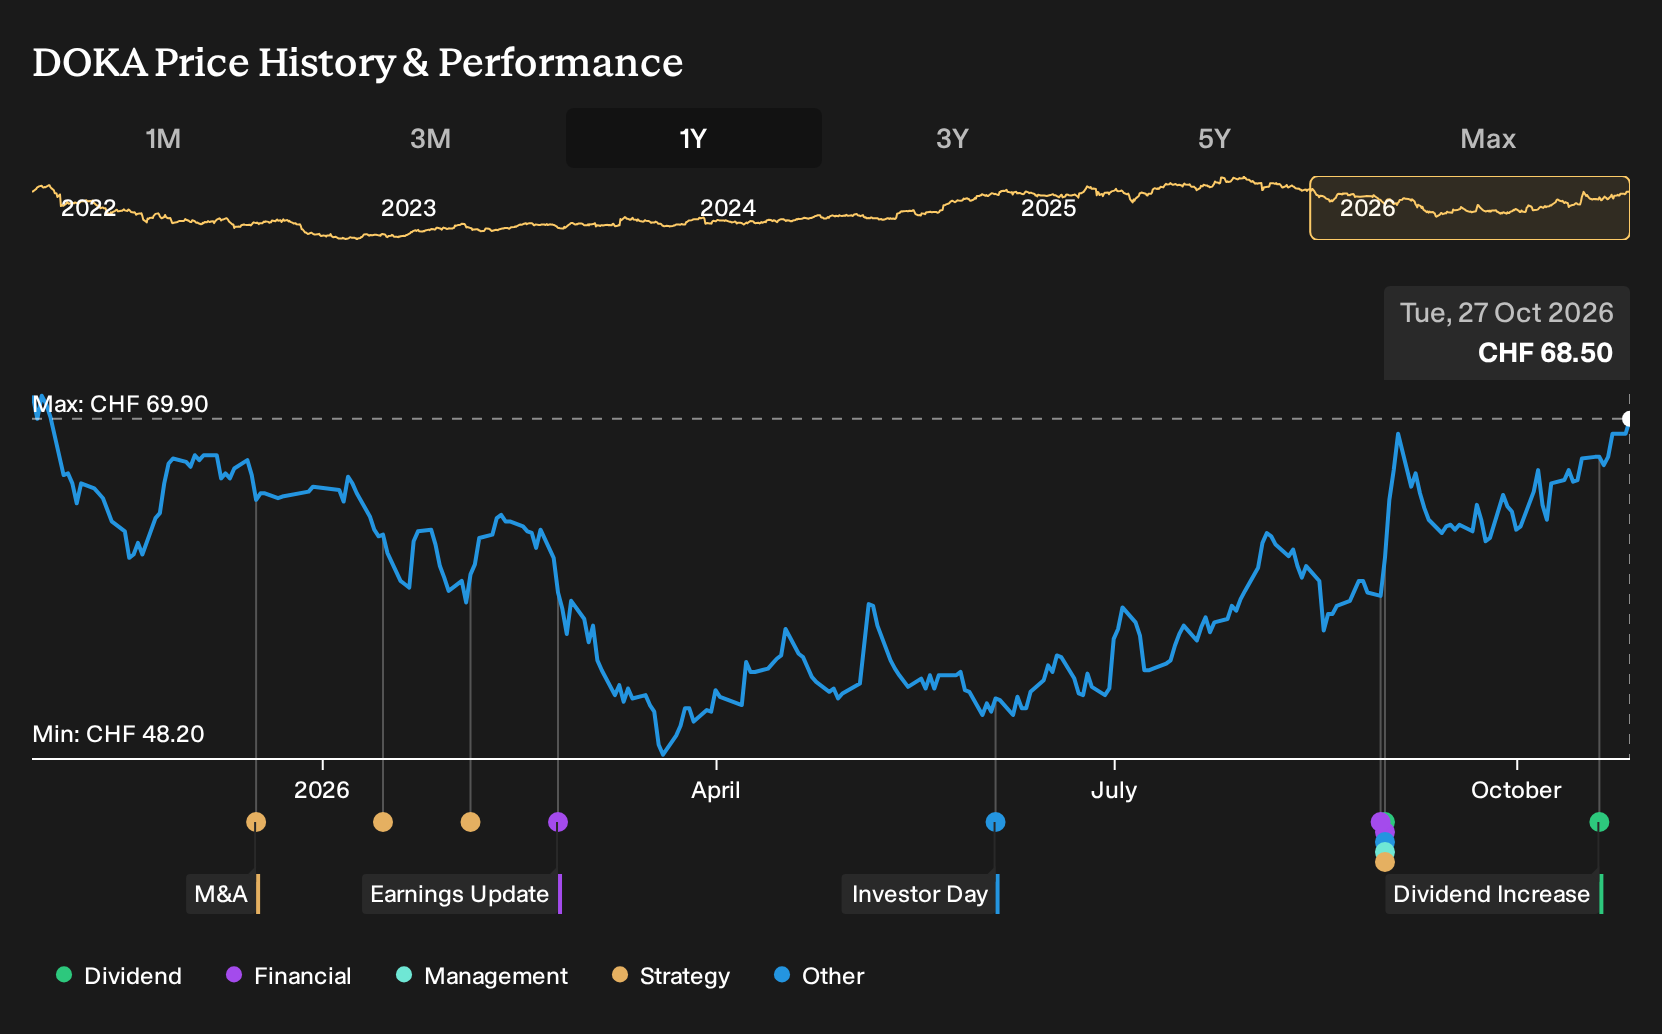
- dormakaba Holding shareholders approved a dividend of CHF 0.95 per share at the 20 October 2026 AGM, a 3.3% increase versus the previous year, with payments scheduled from 26 October 2026 and subject to Swiss withholding tax.
- The higher cash payout reflects a closer alignment between dormakaba Holding’s Shape4Growth efficiency gains and direct returns to investors, which is notable given prior revenue pressure in some regions and segments.
- This 3.3% dividend increase may influence dormakaba Holding’s investment narrative, which focuses on margin management and capital discipline.
Scan how dormakaba Holding's dividend move compares by reviewing a curated 224 dividend fortresses with solid cash payouts that may appeal if income is a key part of your strategy.
dormakaba Holding Investment Narrative Recap
For dormakaba Holding, the core belief is that a leaner cost base from Shape4Growth and exposure to security intensive sectors can support earnings, even when some regions or segments are softer. The higher dividend fits that story but does not materially change the near term setup. The bigger swing factor remains whether revenue can stabilise where it has been pressured.
The short term catalyst is operational detail from upcoming updates, including how access solutions in weaker regions and OEM demand are trending. The key risk is that cost savings carry too much of the earnings load. If revenue growth stays under strain, the current margin profile could be harder to keep over time.
The AGM dividend decision is the clearest signal right now. A CHF 0.95 payout, up 3.3% on last year, suggests management is comfortable linking Shape4Growth efficiency gains to cash returns while still dealing with regional and segment specific revenue pressure.
For investors, a useful lens is how this interacts with the Q1 2027 sales and trading statement on 28 October 2026. That update can show whether order intake in areas such as data centers, airports and North America is doing enough to offset China, Southeast Asia and softer movable wall and OEM demand. Together these areas shape the real catalyst and risk balance.
dormakaba Holding analyst assumptions in focus
dormakaba Holding's narrative projects CHF 3.2b revenue and CHF 152.4m earnings by 2029, based on analysts using a 4.3% yearly revenue growth rate and an earnings increase of about CHF 55.4m from current earnings of CHF 97.0m.
Uncover why dormakaba Holding's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts revenue risk at the center. The lowest dormakaba Holding analysts previously worked with a slower 2.9% yearly sales growth path and earnings of about CHF 154.1m by 2029 from CHF 88.0m today. That is a more cautious story. The new dividend and the Q1 2027 call could shift those expectations. Readers can compare both trajectories and see which version of the future feels more reasonable.
Explore another dormakaba Holding fair value estimate, including one that suggests it could be worth just CHF 76.06.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your dormakaba Holding research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for dormakaba Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate dormakaba Holding's overall financial health at a glance.
Looking for more dormakaba Holding style investment ideas?
If dormakaba Holding sits on your watchlist, it can help to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about resilience, start with a 223 resilient stocks with low risk scores that can help you focus on businesses where the risk score is already in your comfort zone.
- If balance sheet strength is non negotiable for you, filter for companies on the list of solid balance sheet and fundamentals (207 results) and compare their financial footing to dormakaba Holding.
- When you want something a bit off the beaten path, scan a 610 high quality undiscovered gems that surfaces lesser known companies with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com