


EN
Insiders Own Up To 28% Of These European Growth Stocks
As European markets grapple with heightened inflationary pressures and geopolitical tensions, the pan-European STOXX Europe 600 Index recently experienced a decline of 1.39%, reflecting broader concerns across major indices like Germany's DAX and France's CAC 40. In such an environment, growth companies with significant insider ownership can be particularly appealing, as insider stakes often signal confidence in a company's long-term prospects despite market volatility.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 58.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.3% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.1% |
Underneath we present a selection of stocks filtered out by our screen.
Elekta (OM:EKTA B)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Elekta AB (publ) is a medical technology company that offers clinical solutions for treating cancer and brain disorders across the Americas, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of approximately SEK22.81 billion.
Operations: The company's revenue segments include SEK4.48 billion from the Americas.
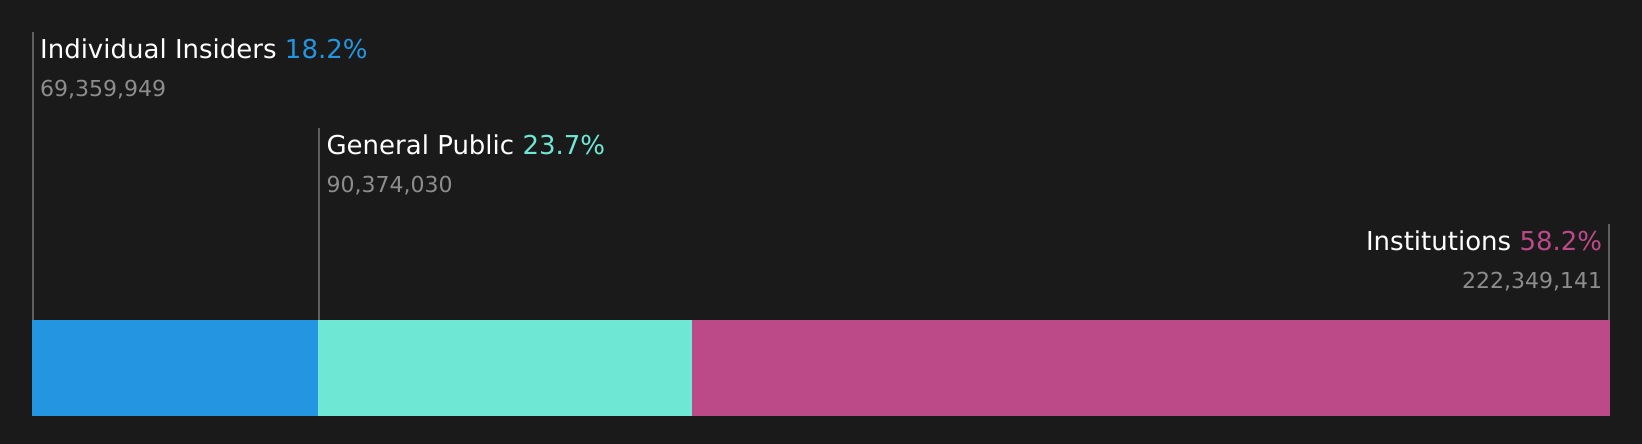
Insider Ownership: 17.4%
Elekta, a growth company with substantial insider ownership, is poised for future profitability with earnings forecasted to grow at 35.02% annually. Despite trading at 49.2% below its estimated fair value, Elekta's high debt level remains a concern. Recent product announcements highlight advancements in adaptive radiotherapy and radiosurgery technologies, potentially enhancing treatment precision and patient outcomes. Insider buying activity over the past three months underscores confidence in the company's strategic direction amidst evolving healthcare needs.
- Click here and access our complete growth analysis report to understand the dynamics of Elekta.
- The analysis detailed in our Elekta valuation report hints at an deflated share price compared to its estimated value.
Ratos (OM:RATO B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Ratos AB (publ) is a private equity firm that focuses on buyouts, turnarounds, add-on acquisitions, and small to middle market transactions, with a market cap of SEK13.05 billion.
Operations: Ratos generates revenue through its specialization in buyouts, turnarounds, add-on acquisitions, and transactions within the small to middle market sectors.
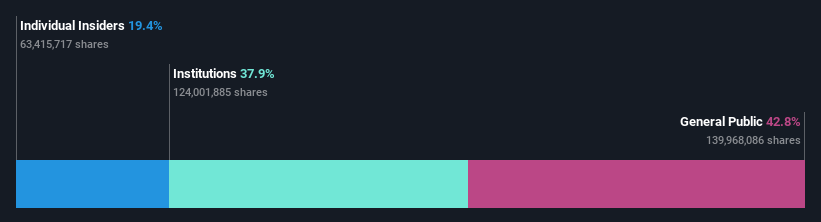
Insider Ownership: 15.2%
Ratos is pursuing growth through strategic acquisitions, leveraging a strong financial position to enhance its platform companies. Despite trading at 45% below estimated fair value and forecasted earnings growth of 43.19% annually, its revenue growth of 2.9% per year lags behind ambitious targets. Recent earnings reveal a decline in net income, with SEK 273 million for Q3 compared to SEK 395 million last year, highlighting challenges amidst expansion efforts in the Swedish market.
- Get an in-depth perspective on Ratos' performance by reading our analyst estimates report here.
- Our expertly prepared valuation report Ratos implies its share price may be lower than expected.
Straumann Holding (SWX:STMN)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Straumann Holding AG is a global provider of tooth replacement and orthodontic solutions, operating in countries such as Switzerland, the United States, China, and others, with a market cap of CHF15.57 billion.
Operations: The company's revenue is derived from its operations (CHF1.31 billion) and sales across various regions, including Asia Pacific (CHF630.19 million), North America (CHF740.35 million), Latin America (CHF337.34 million), and Europe, Middle East, and Africa (CHF1.14 billion).
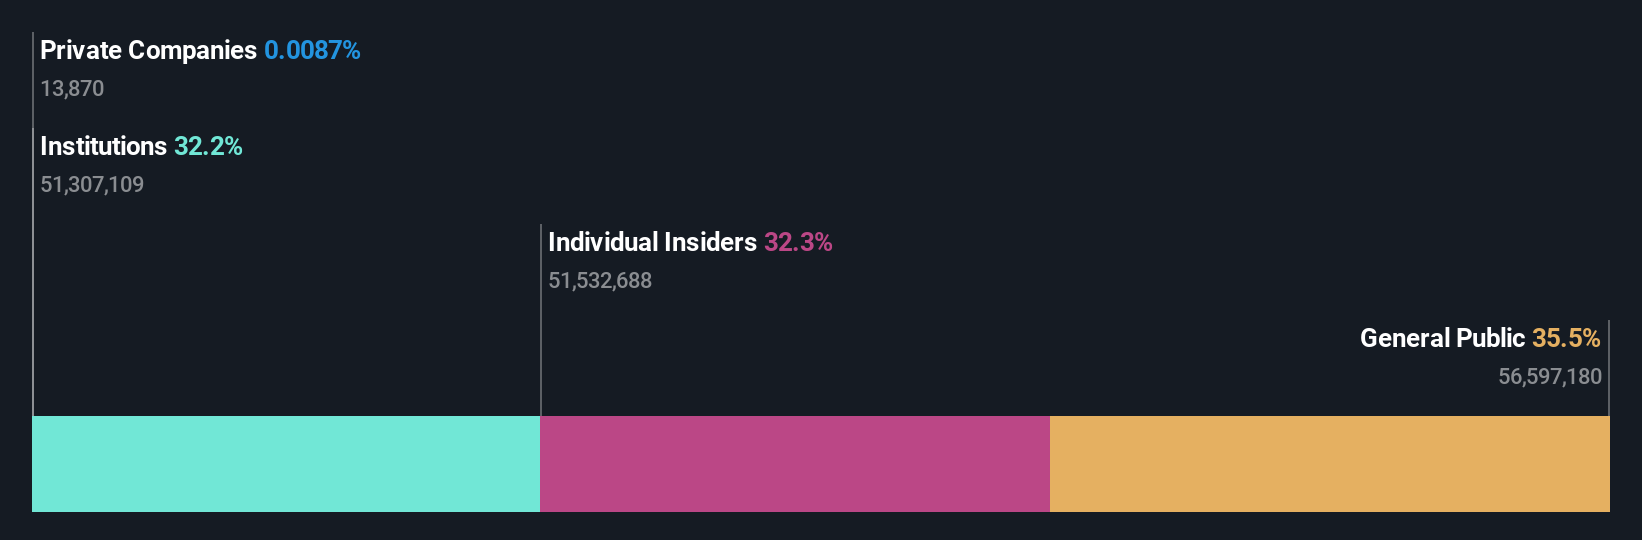
Insider Ownership: 28.8%
Straumann Holding is poised for growth with forecasted annual earnings and revenue growth rates of 16.9% and 9.4%, respectively, outpacing the Swiss market averages. Despite trading at 38.4% below its estimated fair value, the company faces a leadership transition as Christopher Norbye prepares to take over as CEO in December 2026. Recent earnings show sales of CHF 1.38 billion for H1 2026, with net income rising to CHF 249.7 million from the previous year’s figures.
- Delve into the full analysis future growth report here for a deeper understanding of Straumann Holding.
- The valuation report we've compiled suggests that Straumann Holding's current price could be quite moderate.
Taking Advantage
- Navigate through the entire inventory of 202 Fast Growing European Companies With High Insider Ownership here.
- Searching for a Fresh Perspective? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com