


EN
Schneider National (SNDR) Stock Could Be Overvalued Despite Its 39% Run
Schneider National has delivered a solid run over the past year, which naturally puts more focus on whether the current share price lines up with what its earnings can support. With the stock changing hands around US$31.11 at the last close, the key issue is how much of that recent strength is already captured in its profit profile.
- The stock is up 38.9% over the past year, so anyone looking at Schneider National today is really asking how much earnings power is already priced in.
- The business leans heavily on how efficiently it turns freight capacity and logistics assets into profit, which can shape the level and stability of earnings that investors are effectively paying for.
- Your read on Schneider National is one view; the desks covering it have another. See what analysts think Schneider National's shares could be worth.
The issue now is whether Schneider National's recent share price leaves investors paying a level that its earnings can reasonably justify.
If you want a reference point for how other listed businesses with earnings stories are being priced, compare Schneider National against companies in the 29 high quality undervalued stocks.
Does Schneider National Look Pricey on Earnings?
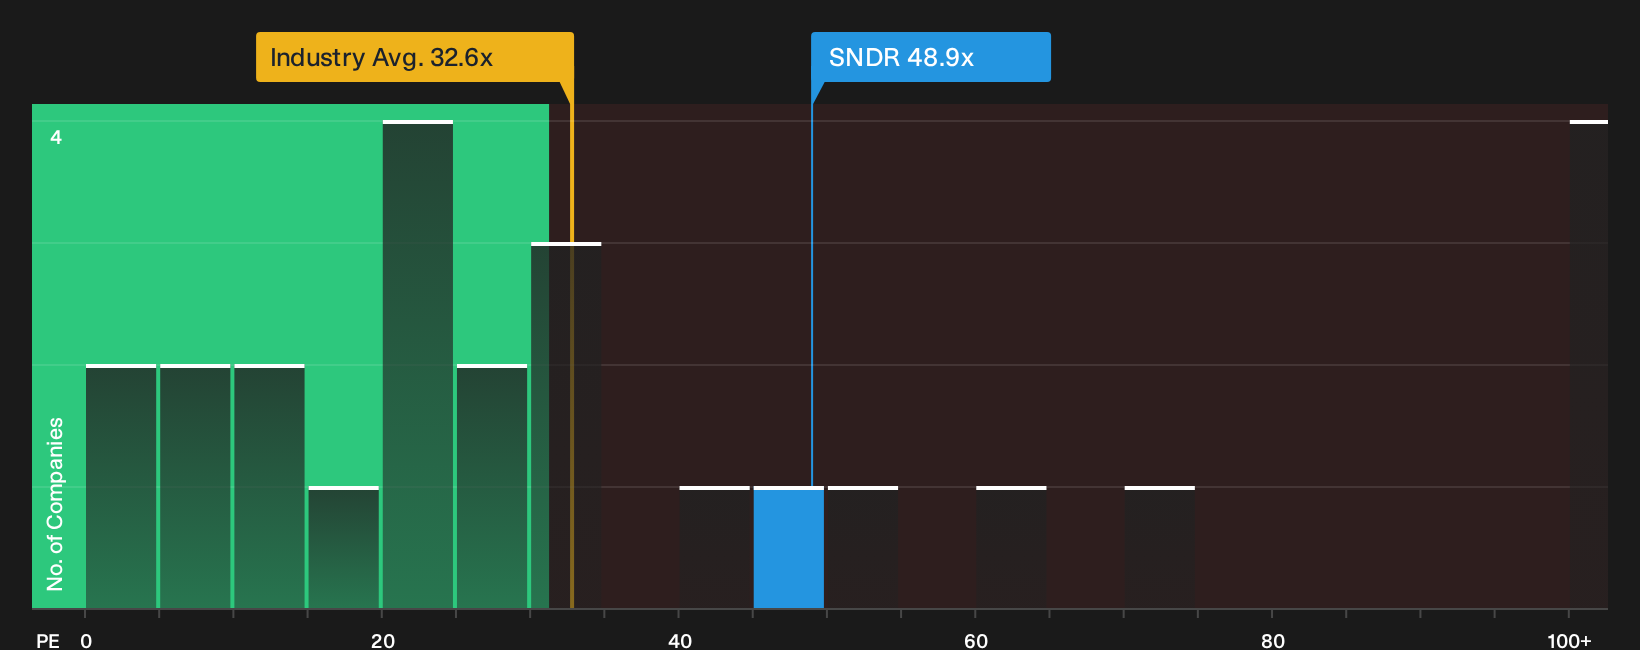
The P/E ratio works well for Schneider National because earnings are a central yardstick for an asset heavy hauler like this. At around 48.9x, the current P/E sits well above the Transportation industry average of 32.6x and below the peer group average of 78.2x. The market is already assigning a premium price to each dollar of profit compared with the sector overall, though not the highest in its peer set.
The fair P/E that would line up with the company’s profile comes out lower than the current market multiple, so on this framework the shares screen as overvalued rather than cheap. That gap suggests you would need to believe Schneider National delivers stronger or more resilient earnings than implied by the model before treating today’s valuation as comfortable. Explore the numbers behind Schneider National's P/E valuation.
The Schneider National Narrative: What Would Justify Today's Price?
Narratives on Schneider National pick up where the P/E debate leaves off and spell out which combinations of future growth, profitability and earnings resilience would need to hold for the stock to be worth materially more or less than today’s price on Simply Wall St’s Community page. Rather than relying on a single multiple or one model output, each scenario lays out the assumptions behind its fair value so you can compare those expectations with reported results as they are released.
Community views on Schneider National are split between investors who see more upside left and those who think most of the story is already in the price.
Bull case: 13% undervalued
"Continued investment in technology and AI driven tools across Schneider National’s logistics, driver support and recruiting operations, including reported 17% productivity gains in frontline logistics staff…"
Discover why this Narrative puts Schneider National at 13% undervalued.
Bear case: roughly fairly valued
"While the Dedicated mix has been a key pillar of Schneider National’s more resilient portfolio, the anticipated loss of a large Dedicated customer becoming more visible in 2H 2026…"
Explore why this Narrative puts Schneider National at roughly fairly valued.
Schneider National’s price is only one piece of the decision
Before you get too anchored on multiples and scenarios, it helps to ask who is steering Schneider National day to day and how their incentives line up with the outcomes you care about. See who runs Schneider National and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com