


EN
Wesdome Gold Mines (TSX:WDO) Following Eagle River Weakness Is The Valuation Too Low
Wesdome Gold Mines (TSX:WDO) is back in focus after a production update highlighted an 18% drop in output at its Eagle River mine, while management pursues projects aimed at stabilizing operations and extending mine life.
Recent trading tells a mixed story for Wesdome Gold Mines. The 1 month share price return is down 22.4%, while the year to date share price return is 30.8% and the 1 year total shareholder return is 37.5%, with the 3 year total shareholder return above 7x. This pattern suggests short term momentum has cooled as the production update lands, even though longer term shareholders have seen very strong gains. They are now reassessing how much risk is currently priced in.
Scan beyond Wesdome Gold Mines and compare its recent pullback against our hand picked 35 elite gold producer stocks to see how other producers are handling operational and production risk.
Wesdome Gold Mines looks like a solid operator on paper, yet the recent pullback challenges that story. After this move, are you paying a fair price for that quality or stretching for it?
Preferred P/E of 9.8x: Is it justified?
Wesdome Gold Mines screens as inexpensive on earnings. The stock last closed at CA$28.41 while trading on a P/E of 9.8x that lines up with peers yet sits well below what some models suggest could be a fairer level.
The P/E ratio links the current share price to the profits the business generates per share. For a miner like Wesdome Gold Mines, this matters because earnings can swing with grades, costs, and production decisions, so investors often watch the earnings tag more closely than simple revenue multiples.
At a P/E of 9.8x, the market is paying the same earnings multiple as the peer average of 9.8x. However, it is applying a clear discount to the Canadian Metals and Mining industry average of 14.2x. That is a meaningful gap. The estimated fair P/E of 18.1x is materially higher again, which signals a level the market could move towards if profits and project delivery line up with expectations.
Explore the SWS fair ratio for Wesdome Gold Mines.
Result: Price-to-earnings of 9.8x (UNDERVALUED)
Still, the 18% production drop at Eagle River and the 100% reliance on Canadian operations leave Wesdome Gold Mines exposed to both asset concentration and local disruptions.
Find out about the key risks to this Wesdome Gold Mines narrative.
Another View: What the SWS DCF Model Says
A second lens tells a stronger story. Our DCF model suggests Wesdome Gold Mines at CA$28.41 is trading well below an estimated future cash flow value of CA$70.84. This points to a large valuation gap that investors need to interpret carefully.
If the cash flows underpinning that DCF hold up, the spread between price and model value raises a simple question. Is the market being too cautious about Wesdome Gold Mines, or is the DCF giving too much credit for future execution risk priced into the stock already?
Look into how the SWS DCF model arrives at its fair value.
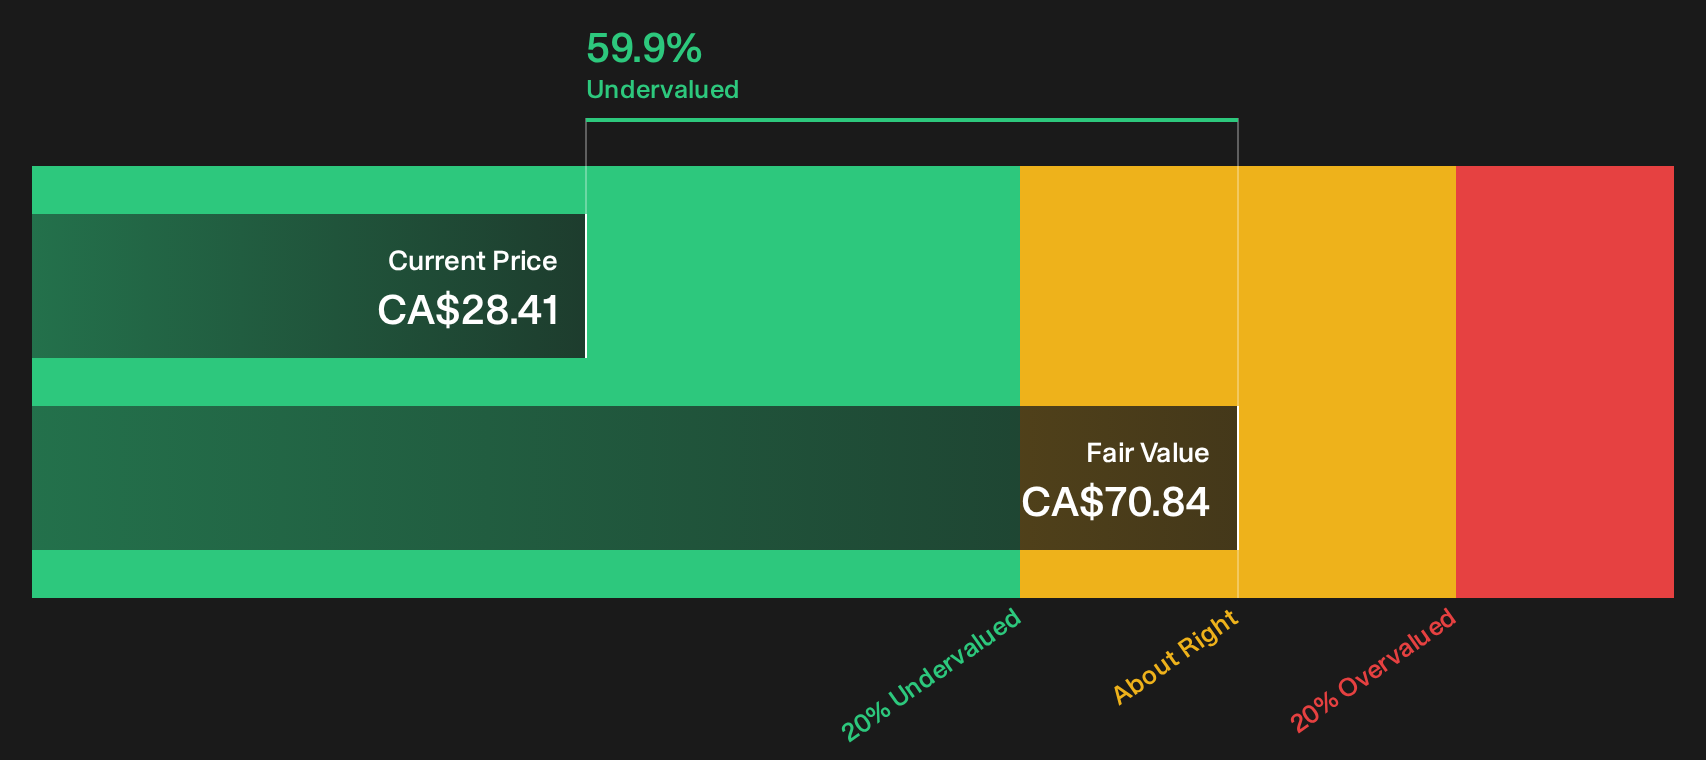
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wesdome Gold Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message? If Wesdome Gold Mines has you undecided, act promptly, stress test the numbers yourself, then weigh up the 5 key rewards
Looking for more Wesdome Gold Mines style investment ideas?
If Wesdome Gold Mines has sharpened your focus, do not stop here. Broaden your watchlist and pressure test your thesis against other high potential opportunities.
- Target resilient performers that aim to limit downside risk while still giving you room to participate in upside with the 8 resilient stocks with low risk scores.
- Hunt for quality businesses that trade on appealing valuations by scanning the 3 high quality undervalued stocks before capital shifts to the next set of opportunities.
- Spot financially disciplined operators with stronger balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (7 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com