


EN
Is DICK'S Sporting Goods (DKS) Reasonably Priced On Earnings?
DICK'S Sporting Goods has seen its share price move sharply over recent years, and the question now is whether the current US$141.50 level is properly grounded in what the business earns. With the stock giving investors a very mixed ride across different timeframes, the issue comes down to how much of those earnings you are effectively paying for today.
- Over the past 3 years, DICK'S Sporting Goods has delivered a gain of 42.2% which puts real weight on whether its current earnings profile can support that kind of share price reset.
- The new Foot Locker partnership with the New York Knicks points to management leaning on branded basketball demand and in arena exposure, which can influence how investors think about future profitability and the durability of earnings in athletic retail.
- The analysts covering DICK'S Sporting Goods have run their own numbers. See what analysts think DICK'S Sporting Goods's shares could be worth.
The stock's next move may depend on whether today's price is well aligned with the earnings power that DICK'S Sporting Goods is currently generating.
If you are weighing DICK'S Sporting Goods against other athletic and retail plays, it can help to line it up beside solid balance sheet and fundamentals stocks screener (24 results).
Does DICK'S Sporting Goods Look Undervalued on Earnings?
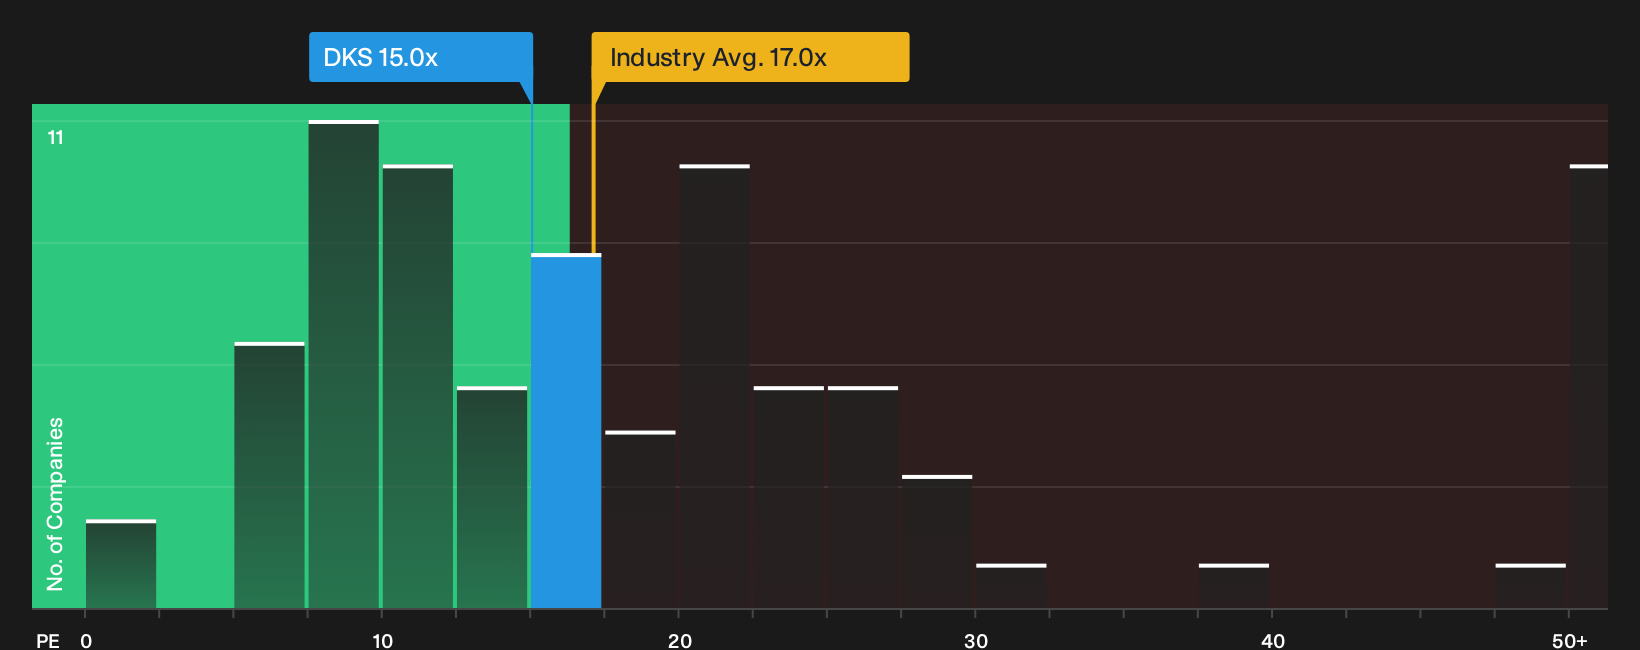
The P/E ratio is a useful lens for DICK'S Sporting Goods because earnings remain a central anchor for how investors judge established retailers. On this measure, the stock trades on roughly 15.0x, which is below both the Specialty Retail industry average of about 17.0x and an estimated peer group on roughly 22.9x.
The fair P/E that factors in DICK'S Sporting Goods' sector, profitability profile and size sits above the current multiple, so the market price leans toward undervalued on this yardstick. Because the recent New York Knicks partnership gives Foot Locker fresh ways to reach basketball fans, the stock still changes hands at a discount to where this earnings based framework might place it. That gap suggests you need to weigh how durable you think those profits are compared with other retailers before deciding how attractive the current P/E really is. Explore the numbers behind DICK'S Sporting Goods's P/E valuation.
The DICK'S Sporting Goods Narrative: What Would Justify Today's Price?
Narratives for DICK'S Sporting Goods sit between the current P/E puzzle and the assumptions behind it, spelling out what kind of future on growth, profitability and earnings would need to hold for the share price to end up meaningfully higher or lower than today. Instead of a single output from a ratio or model, they show the path that number relies on so you can watch how the actual business lines up with that story over time on Simply Wall St's Community page.
Community views on DICK'S Sporting Goods now split between investors who see execution upside and others who focus on the Foot Locker drag.
Bull case: 10% undervalued
"The current valuation suggests that the market is heavily discounting the Foot Locker risks and the recent guidance cuts, and is not fully recognizing DICK'S Sporting Goods for the contribution from high-ROI store formats, ancillary platforms, and the potential benefits of the combined athletic footwear ecosystem..."
Discover why this Narrative puts DICK'S Sporting Goods at 10% undervalued.
Bear case: 25% overvalued
"Full-year Foot Locker pro forma comp guidance moved from 1.5% to 3% growth to 2% to flat and the operating income expectation shifted from a profit of $110M to $150M to a loss of $40M to $80M..."
Explore why this Narrative puts DICK'S Sporting Goods at 25% overvalued.
DICK'S Sporting Goods: why the current price is only half the story
Valuation tells you what you are paying today, but the analysts who model DICK'S Sporting Goods a few years ahead offer a separate lens on where earnings might go next and how that lines up with this share price. Explore where analysts expect DICK'S Sporting Goods to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com