


EN
Norion Bank (OM:NORION) Could Be 63% Below Fair Value After Q3 Results
Norion Bank (OM:NORION) just delivered third quarter results along with news that its Board will weigh a share repurchase program, putting earnings quality and potential capital returns in sharper focus for investors.
Norion Bank’s latest quarterly update and potential buyback discussion come after a mixed year for the share price. The stock is at SEK64.6, with a 90 day share price return of 12.54%, but the year to date share price return is down 4.44%.
Scan how Norion Bank compares with other financials that combine profitability, capital return potential, and balance sheet resilience by reviewing our hand picked 223 resilient stocks with low risk scores.
The recent rebound in Norion Bank following stronger quarterly earnings and the potential buyback decision puts a simple puzzle in front of you. Is most of the re rating already done, or does value still sit ahead?
Price-to-Earnings of 9.3x: Is it justified?
Norion Bank trades on a P/E of 9.3x, which sits below several valuation reference points and provides a clear entry metric to compare with the SEK64.6 share price.
The P/E ratio compares what investors currently pay for each unit of earnings to what the business is generating today. For a lender such as Norion Bank, which is forecast to grow earnings at 12.4% per year and revenue at 14.7% per year, this earnings-based yardstick indicates how much future profitability may already be reflected in the market value.
Context matters for this kind of multiple. Norion Bank's P/E of 9.3x is lower than the European Banks industry average of 11.6x and is also below the peer average of 14.5x. It is further below an estimated fair P/E ratio of 12.7x, a level the valuation work suggests the market could move towards if sentiment and fundamentals stay aligned.
Explore the SWS fair ratio for Norion Bank.
Result: Price-to-Earnings of 9.3x (UNDERVALUED)
Still, the Norion Bank story can shift quickly if credit conditions tighten or if the Board holds back on a meaningful share repurchase decision.
Find out about the key risks to this Norion Bank narrative.
Another view using cash flows
The low P/E paints Norion Bank as inexpensive, yet the SWS DCF model points to something far more extreme. On that framework, a share price of SEK64.6 compares with an estimated future cash flow value of SEK173.97, which implies a wide valuation gap that is harder to ignore.
If that kind of spread between the market quote and a cash flow based estimate matters to you, it is worth seeing how those assumptions are built in detail. Look into how the SWS DCF model arrives at its fair value.
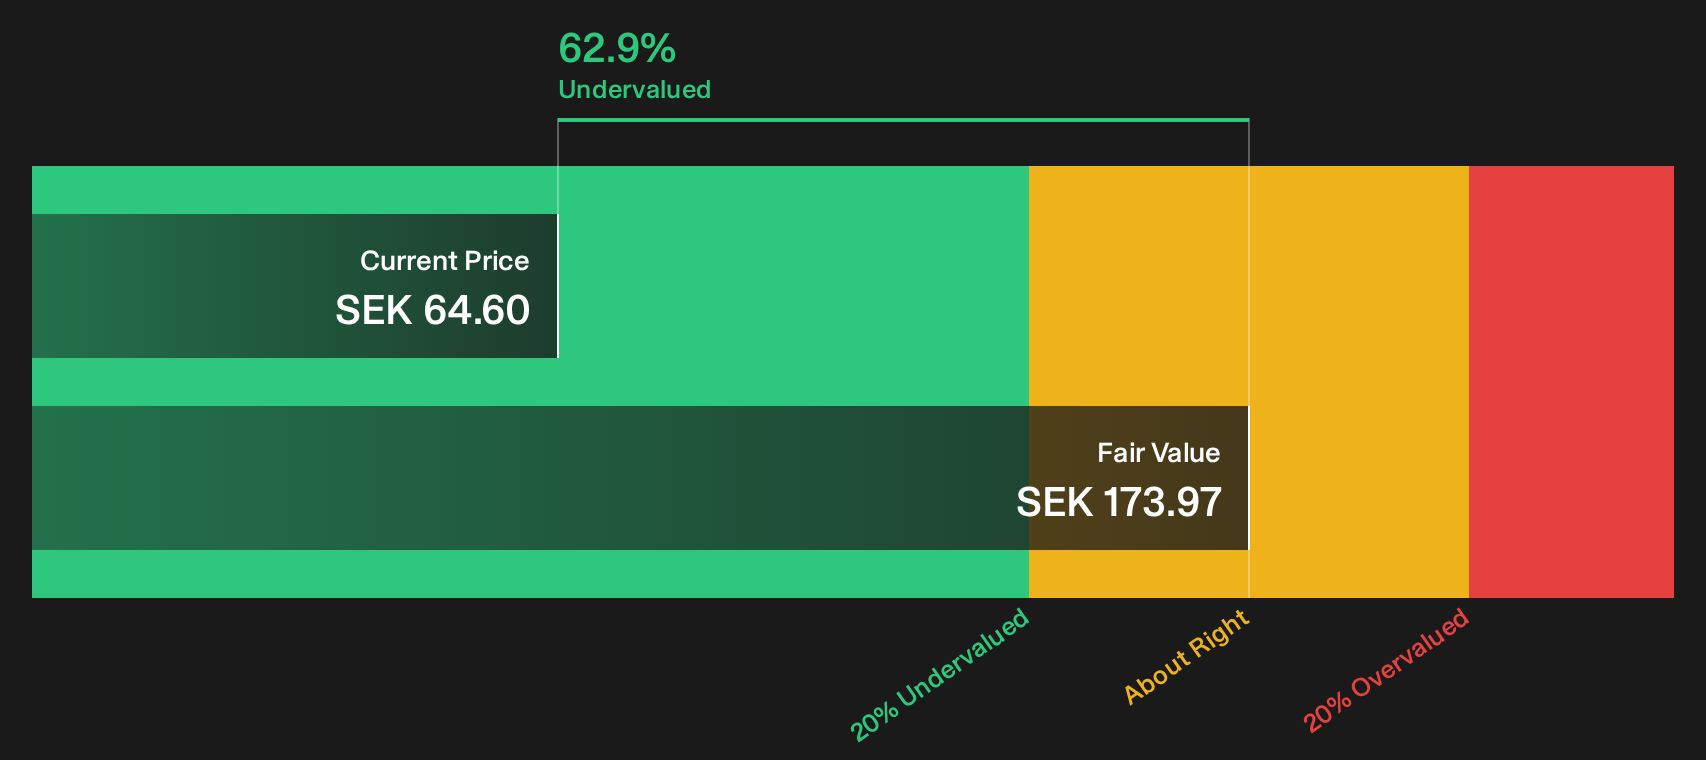
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norion Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Norion Bank can feel confusing, so move fast, review the full data set, and weigh both sides with the 3 key rewards and 2 important warning signs
Looking for more Norion Bank style investment ideas?
If Norion Bank has sharpened your focus on value and risk, do not stop here. Broader opportunity often appears where you least expect it, so keep scanning.
- Target dependable income streams by reviewing a curated set of higher yielding companies through the 224 dividend fortresses.
- Hunt for quality at a discount with the 610 high quality undiscovered gems, where strong fundamentals may not yet be fully recognised in prices.
- Zero in on balance sheet strength and robust fundamentals using our focused list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com