


EN
Argan (AGX) Stock May Trade At A Premium Following Top Pick Call
Argan has delivered very large share price gains over the past few years, which puts a sharp spotlight on whether the current tag still lines up with what the business earns. With the stock pulling back in recent weeks, the question is whether the recent price takes proper account of its earnings power.
- Over 5 years the share price return is close to 8x, which raises the stakes on whether earnings are doing enough heavy lifting to justify that kind of move.
- Recent commentary points to a strong position in power generation projects, which can shape how investors think about the durability and timing of future profit streams that underpin any earnings based valuation.
- The analysts covering Argan have run their own numbers. See what analysts think Argan's shares could be worth.
The stock's next move may depend on whether Argan's current earnings profile supports the price investors are paying today.
If you are weighing Argan's earnings story against its recent share price surge, it can help to benchmark it against 29 high quality undervalued stocks.
Does Argan Look Pricey on Earnings?
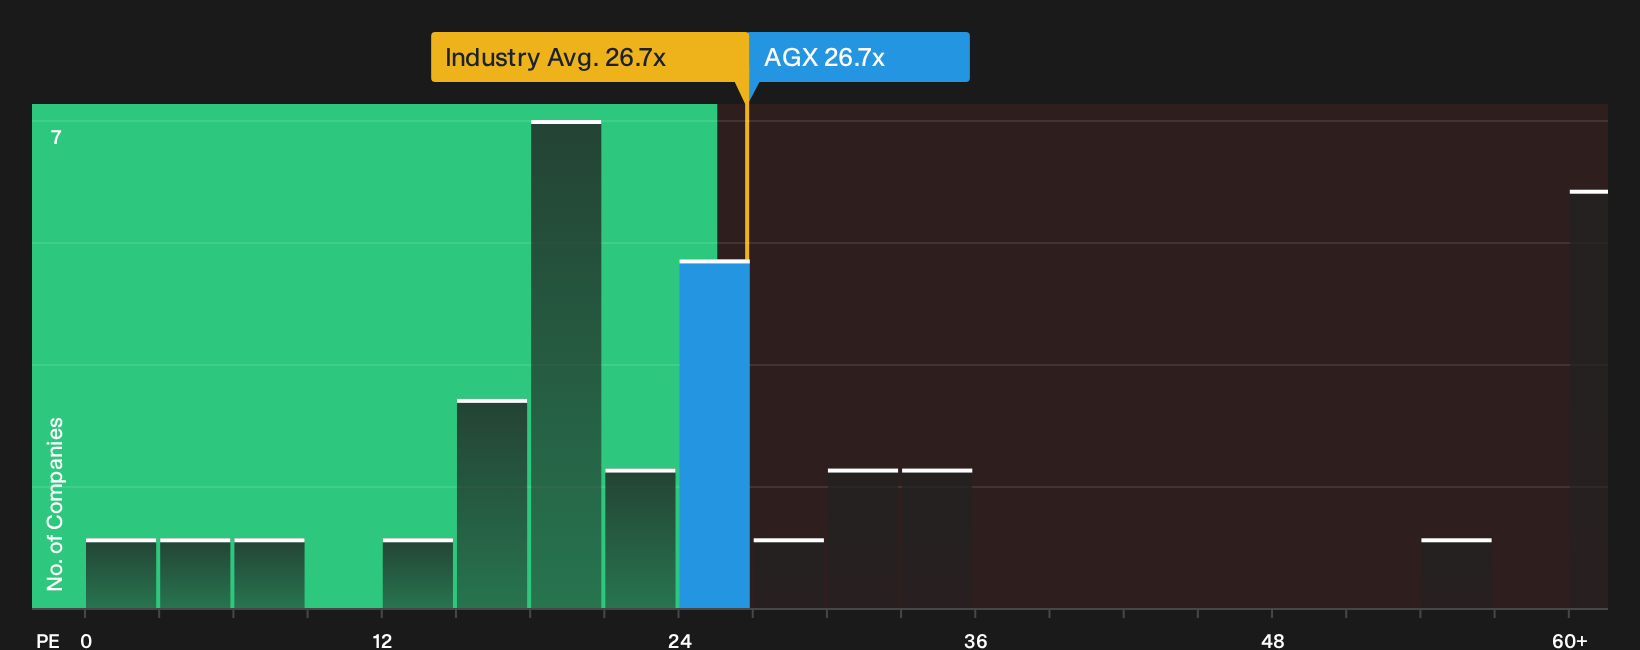
The P/E ratio suits Argan because earnings still sit at the center of how investors judge its project based business. On this lens, the stock trades at about 26.7x earnings, very close to the Construction sector average of roughly 26.7x and only slightly below the peer group near 28.9x. Because the current multiple sits above what a tailored fair multiple estimate suggests for Argan, the shares screen as overvalued on this framework.
JPMorgan’s recent callout of Argan as a top pick for the rest of 2026 helps explain why enthusiasm is high. However, that optimism already looks well reflected in the current earnings multiple. For anyone considering the ticker today, the key question is whether the profit profile implied by this premium to the fair level feels robust enough to justify paying up on P/E. Explore the numbers behind Argan's P/E valuation.
The Argan Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Argan pick up where the P/E puzzle leaves off. They explain which potential paths for Argan's revenue, profitability, and earnings would need to occur for the stock to be worth materially more or materially less than it is today. These Narratives are available on the company’s Community page so you can see the story behind the numbers. Where a single multiple or model gives one number, these Narratives describe the future that number relies on so you can watch whether it still matches reality.
Community views on Argan are split between a backlog and cash story and a crew capacity ceiling that could cap what comes next.
Bull case: 40% undervalued
"The capital light EPC model and roughly $1.0b of cash and investments with no debt, alongside ongoing dividends and buybacks…"
Discover why this Narrative puts Argan at 40% undervalued.
Bear case: 25% overvalued
"Argan’s model relies on executing 10 to 12 complex jobs at once, with nine projects already underway and the non craft workforce at its highest level…"
Explore why this Narrative puts Argan at 25% overvalued.
One more Argan check before you stop at the P/E
Price multiples and storylines tell only part of it, because professional coverage also sketches where they currently expect Argan to be a few years from now. Explore where analysts expect Argan to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com