


EN
TOPPAN Holdings (TSE:7911) Could Be 32% Undervalued As Expansion Bets Build
The recent optimism around TOPPAN Holdings (TSE:7911) stems from its push into sustainable packaging, digital security, and advanced semiconductors, which has sharpened attention on whether its elevated P/E still leaves room for mispricing.
Recent trading has been choppy. TOPPAN Holdings’ share price return is down 12.06% over 30 days and 7.19% year to date. However, a 1-year total shareholder return of 15.99% and 5-year total shareholder return of 153.97% point to momentum that has built over time despite the current pullback.
Compare TOPPAN Holdings’ rerating story with other high quality undervalued opportunities by scanning the 16 high quality undervalued stocks, which highlights companies that share strong fundamentals and potential mispricing.
TOPPAN Holdings now trades at a sizeable discount to both intrinsic estimates and analyst targets, even after its strong multi year run. Is that a genuine margin of safety, or is the market flagging real risk?
Most Popular Narrative: 32% Undervalued
TOPPAN Holdings closed at ¥2,162.5, while the most followed narrative pegs fair value at ¥3,175. This frames the recent share price pullback as a potential valuation gap rather than a broken story.
The integration of Sonoco's packaging business is expected to markedly expand TOPPAN's global reach and scale, enhancing its position in sustainable, eco-friendly packaging, an area supported by long-term sustainability and ESG momentum. The resulting synergies and access to high-growth markets should improve revenue growth and raise overall net margins as higher-margin sustainable packaging makes up a greater share of earnings.
See why 2 investors see TOPPAN Holdings as 32% undervalued.
Result: Fair Value of ¥3,175 (UNDERVALUED)
Still, shrinking traditional print and the heavy cost of portfolio reshaping could erode TOPPAN Holdings’ profits faster than newer packaging and electronics earnings ramp up.
Find out about the key risks to this TOPPAN Holdings narrative.
Another View: What TOPPAN Holdings’ P/E Is Really Saying
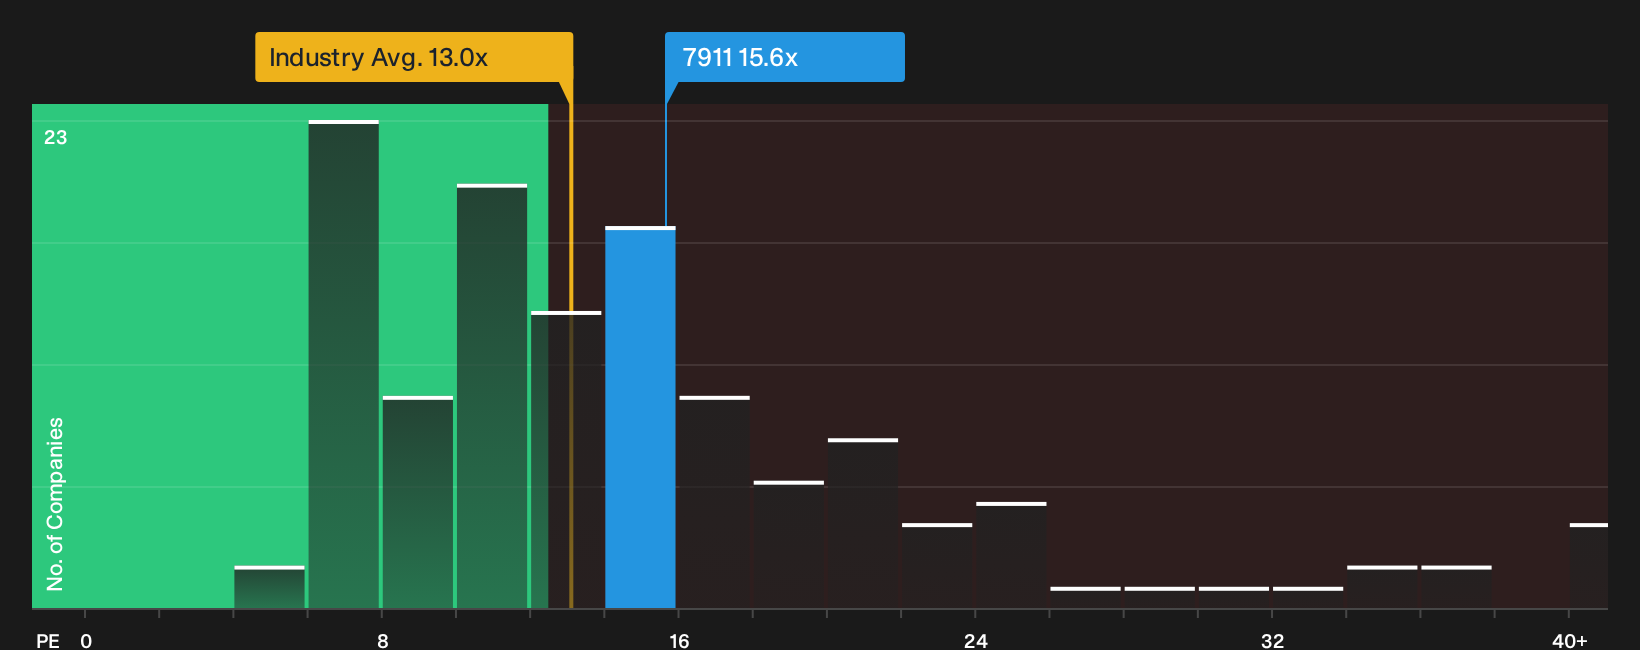
Against all the talk about fair value at ¥3,175, the current P/E of 15.6x tells a different story. TOPPAN Holdings trades above the JP Commercial Services average of 13x and the peer group on 14.3x, yet still sits below an estimated fair ratio of 21.8x.
That combination points to a stock that screens expensive relative to the sector today, while still leaving room for the market to move closer to the higher fair ratio over time. The key question for investors is whether earnings quality and future execution justify paying up now for that potential re rating.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on TOPPAN Holdings so far and wondering how much is risk and how much is opportunity. Move fast, stress test the numbers, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond TOPPAN Holdings?
You have a clear view on TOPPAN Holdings now. Keep that momentum going by lining up a few fresh contenders before the next move in your portfolio.
- Spot potential value rebounds early by scanning the 16 high quality undervalued stocks, which combine solid fundamentals with prices that may not fully reflect underlying quality.
- Build more resilient income by reviewing the 29 dividend fortresses, which focus on higher yielding businesses with the financial strength to support ongoing payouts.
- Sleep easier through volatility by checking the 22 resilient stocks with low risk scores, which filter for sturdier balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com