


EN
How Investors May Respond To Panasonic Holdings (TSE:6752) Europe Laptop Launch
- Panasonic Holdings, through Panasonic Connect Europe, has launched the Let’s note CF-FC7 professional laptop in Europe, an ultra-light, AI ready Copilot+ PC built in Japan with a 14 inch WUXGA display, 512GB SSD and 16GB LPDDR5x memory for Windows 11 Pro business workloads.
- The FC7’s focus on on device AI processing, long battery life and durability testing highlights Panasonic’s push to address demanding enterprise mobility use cases rather than general consumer computing.
- We will now look at how Panasonic Holdings' European launch of its AI ready Let’s note CF FC7 could influence the broader investment narrative.
Scan beyond Panasonic Holdings and track how AI ready hardware is spreading across listed companies with our hand picked 55 AI infrastructure stocks, which is shaping the next wave of enterprise computing.
Panasonic Holdings Investment Narrative Recap
To own Panasonic Holdings, you need to be comfortable with a group in the middle of a multi year reset. The core belief is that cost cuts, portfolio pruning and a heavier tilt to AI related and data center demand can matter more over time than short term noise in EV batteries and one off charges. The Let’s note CF FC7 launch in Europe fits that story only at the margin and is unlikely to shift near term numbers on its own.
The key near term swing factor still sits in execution on restructuring and the ability to translate the planned ¥145b fixed cost reduction into cleaner margins, especially after profit margins slipped to 3.1% from 4.5%. The biggest risk remains operational strain in energy storage and EV related projects, where weaker sector demand, tariffs and ramp up issues in North America could restrain operating leverage even if other units perform more steadily.
The CF FC7 Copilot+ PC debut ties most clearly into Panasonic Holdings’ broader push into AI related devices and systems, where management has outlined a FY29 sales target of ¥1.4b backed by around ¥500b of planned capex over FY27 to FY29. While this specific notebook is a Connect segment product, it reinforces the narrative that AI capable hardware is not limited to data centers but extends into premium client devices for enterprise users.
For catalysts, the interesting link is how AI ready client hardware like the FC7 can sit alongside Panasonic Holdings’ exposure to AI servers, multilayer circuit board materials and factory automation tied to data centers. If orders for infrastructure products keep building and the firm reallocates more battery capacity from EVs into data center energy storage, the mix of AI centric revenue could grow, while execution missteps or slower demand in those projects would cut into that opportunity.
Panasonic Holdings' analyst narrative points to revenues of ¥9,165.1b and earnings of ¥735.4b by 2029, based on assumed yearly top line growth of 3.9% and an earnings increase of about ¥482.2b from ¥253.2b today.
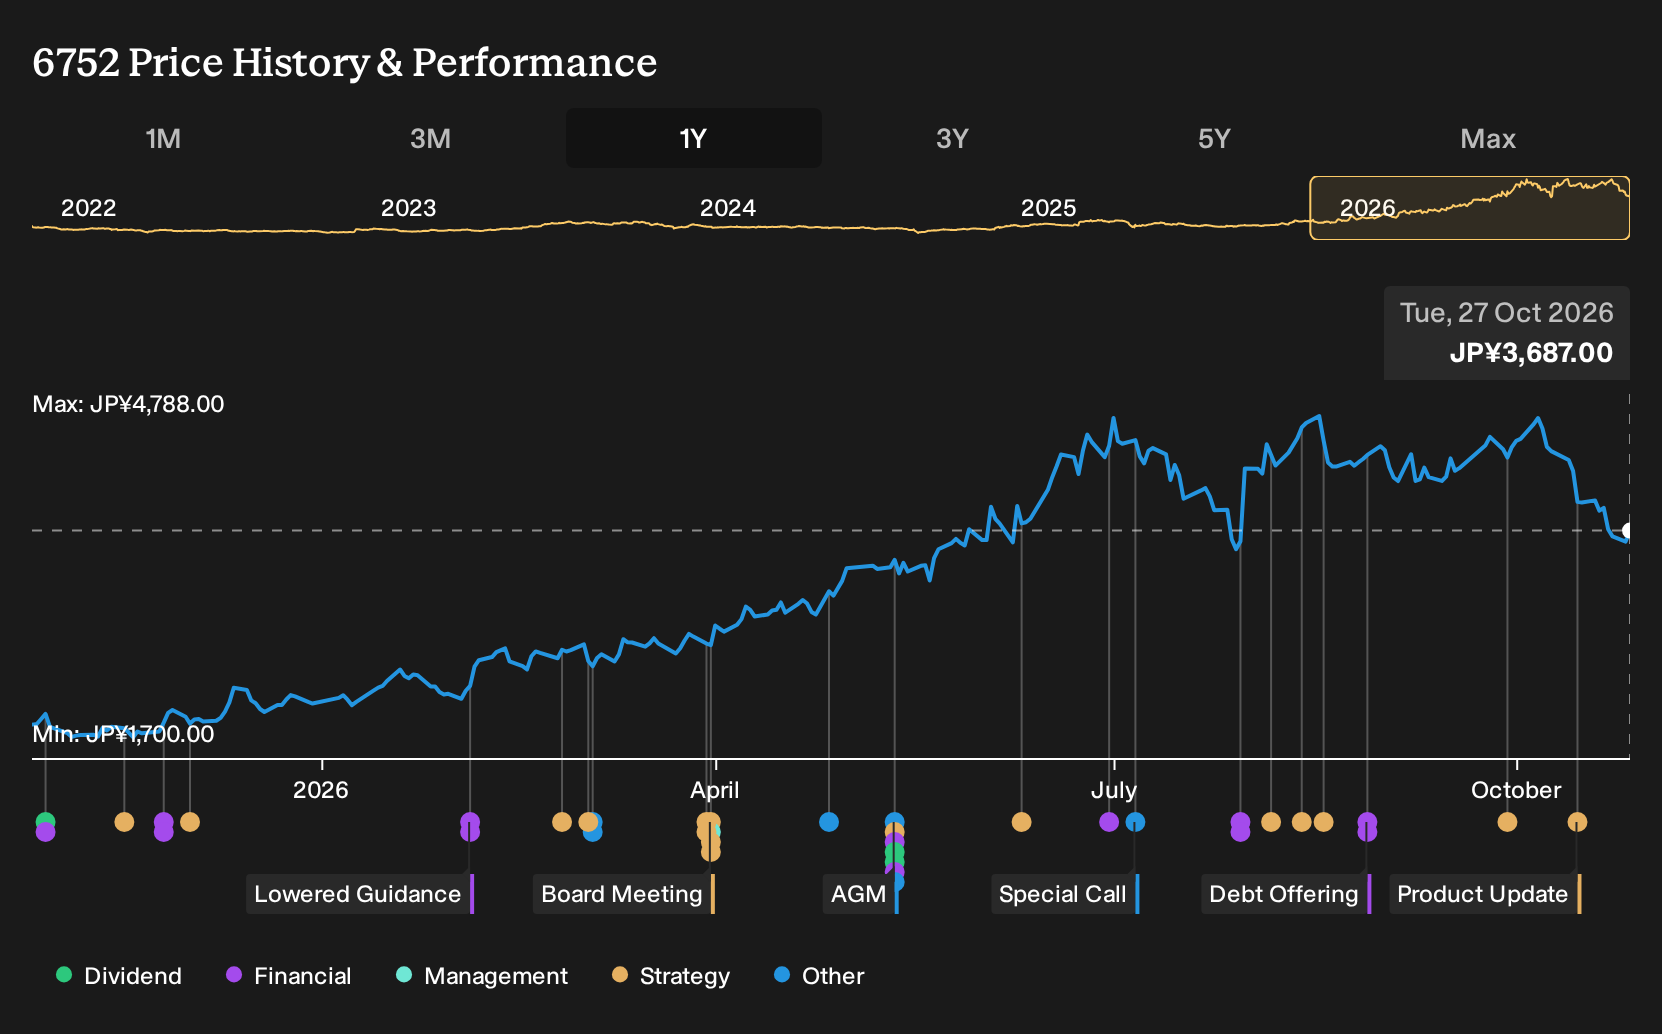
Uncover why Panasonic Holdings' fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish angle that matters for this Panasonic Holdings news is concern that AI related demand is already fully priced in. The lowest analysts were working off 2029 revenue of ¥8,828.4b and earnings of ¥689.3b before this FC7 launch, and saw fair value closer to ¥3,410.69. That is a much harsher read than consensus. Use this contrast as a prompt to explore multiple viewpoints, and then decide how much weight to give a single enterprise laptop launch in your own framework.
Explore 3 other Panasonic Holdings fair value estimates, including one that suggests it could be worth just ¥4974!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Panasonic Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Panasonic Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Panasonic Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Panasonic Holdings?
Once you have formed a view on Panasonic Holdings, it can help to line it up against other opportunities and see where the risk, balance sheet strength and potential income profile feel more attractive to you.
- If you want income to do more of the heavy lifting in your returns, consider companies with resilient payouts and start with a focused set of 29 dividend fortresses that may suit a yield oriented approach.
- Readers who care most about capital strength and financial resilience can narrow the field quickly by scanning a curated list of solid balance sheet and fundamentals (23 results) to see which businesses line up with their comfort zone.
- For those hunting for less crowded stories with solid fundamentals, a targeted 72 high quality undiscovered gems can surface candidates that are not already on everyone else’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com