


EN
Asian Growth Stocks Insiders Are Betting On
As global markets navigate the challenges of AI investment concerns and rising oil prices, Asia's economic landscape remains a focal point for investors seeking growth opportunities. In this environment, companies with high insider ownership often stand out as potential contenders, as they may signal confidence from those closest to the business operations.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.1% |
| SEERS (KOSDAQ:A458870) | 33.6% | 37.8% |
| Meitu (SEHK:1357) | 23.1% | 26.5% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 104.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 67.4% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
We'll examine a selection from our screener results.
Exicon (KOSDAQ:A092870)
Simply Wall St Growth Rating: ★★★★★★
Overview: Exicon Co., Ltd. is a semiconductor test solution company operating in Korea and internationally, with a market cap of ₩751.15 billion.
Operations: The company generates revenue primarily from its semiconductor segment, amounting to ₩97.82 billion.
Insider Ownership: 17.3%
Return On Equity Forecast: 22% (2029 estimate)
Exicon is experiencing substantial growth, with revenue expected to increase by 45% annually, outpacing the Korean market's 13.7%. Its earnings are forecasted to grow significantly at 47.7%, surpassing the local market's 28.1%. Despite high volatility in its share price recently, Exicon became profitable this year and trades at a considerable discount of 42.1% below estimated fair value. No significant insider trading activity has been reported over the past three months.
- Take a closer look at Exicon's potential here in our earnings growth report.
- Our expertly prepared valuation report Exicon implies its share price may be too high.

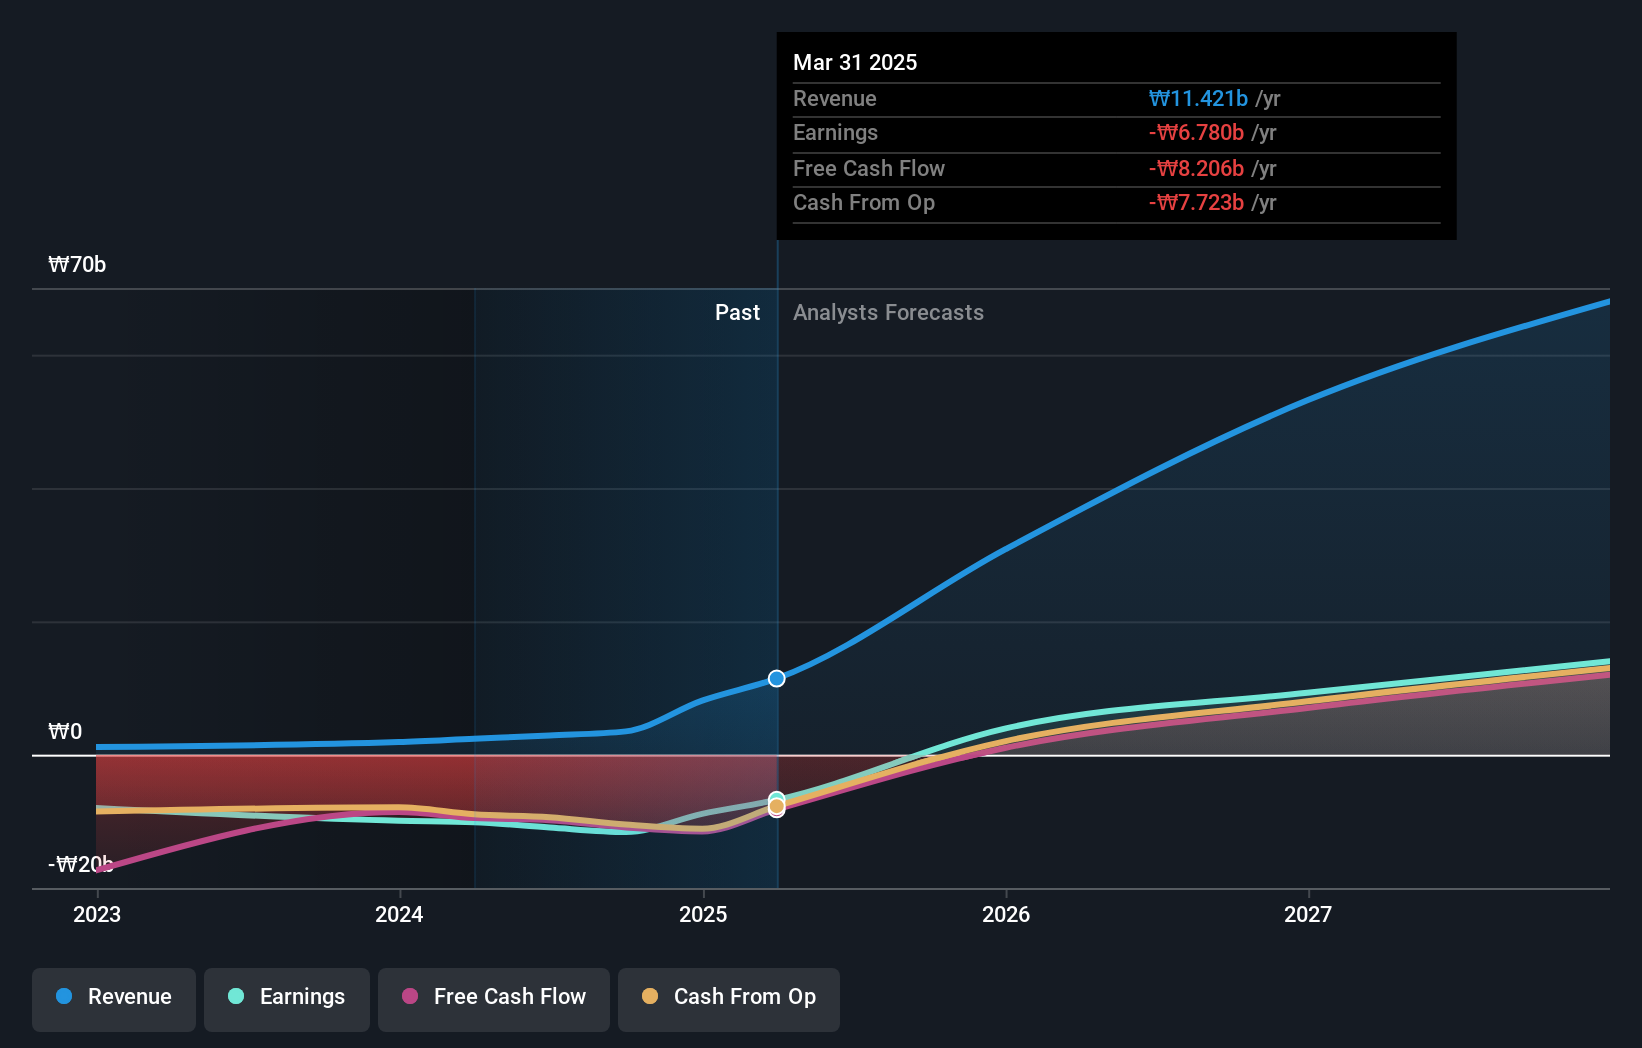
SEERS (KOSDAQ:A458870)
Simply Wall St Growth Rating: ★★★★★★
Overview: SEERS Co., Ltd. develops, manufactures, and sells medical devices in South Korea with a market cap of ₩1.07 billion.
Operations: The company generates revenue primarily from its medical equipment segment, amounting to ₩97.05 billion.
Insider Ownership: 33.6%
Return On Equity Forecast: 53% (2029 estimate)
SEERS is poised for substantial growth, with earnings projected to rise 37.8% annually, outstripping the Korean market's 28.1%. Revenue is expected to grow at 38.2%, well above market averages. Despite recent share price volatility and high non-cash earnings, SEERS trades significantly below its estimated fair value. Recent private placements raised KRW 110 billion through convertible bonds, enhancing capital structure without insider trading activity in the past three months.
- Get an in-depth perspective on SEERS' performance by reading our analyst estimates report here.
- The analysis detailed in our SEERS valuation report hints at an inflated share price compared to its estimated value.
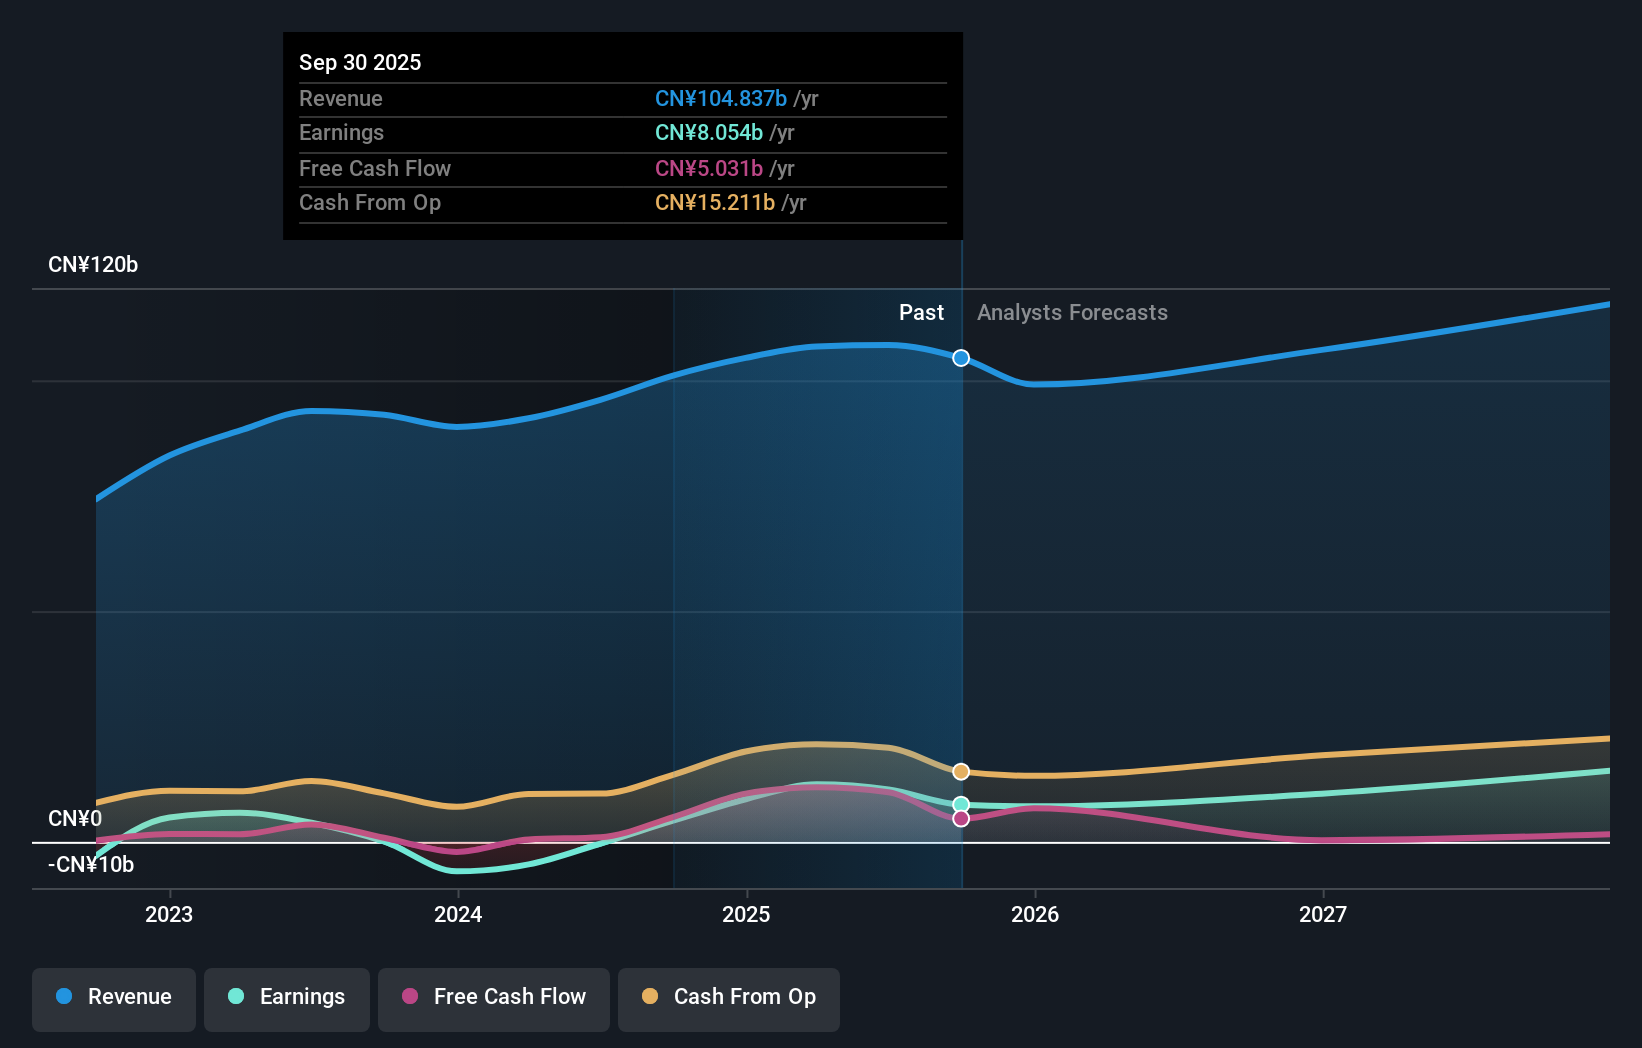
Wens Foodstuff Group (SZSE:300498)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Wens Foodstuff Group Co., Ltd. operates in the agricultural and animal husbandry sectors both in China and internationally, with a market capitalization of approximately CN¥105.40 billion.
Operations: Wens Foodstuff Group Co., Ltd. generates revenue through its agricultural and animal husbandry operations, both domestically and internationally.
Insider Ownership: 28.0%
Return On Equity Forecast: 21% (2029 estimate)
Wens Foodstuff Group faces challenges with declining sales and a net loss of CNY 4.96 billion for the first nine months of 2026, compared to a profit last year. Despite trading significantly below estimated fair value, its revenue growth forecast at 6.3% annually lags behind market expectations. Profitability is anticipated within three years, aligning with above-average market growth projections. However, dividend sustainability remains an issue due to insufficient earnings coverage and cash flow constraints.
- Dive into the specifics of Wens Foodstuff Group here with our thorough growth forecast report.
- Insights from our recent valuation report point to the potential undervaluation of Wens Foodstuff Group shares in the market.
Next Steps
- Get an in-depth perspective on all 512 Fast Growing Asian Companies With High Insider Ownership by using our screener here.
- Seeking Other Investments? Trump's oil boom is here — pipelines are primed to profit. Discover the 22 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com