


EN
What Baby Bunting Group Bears Saw Before A 62% Drop
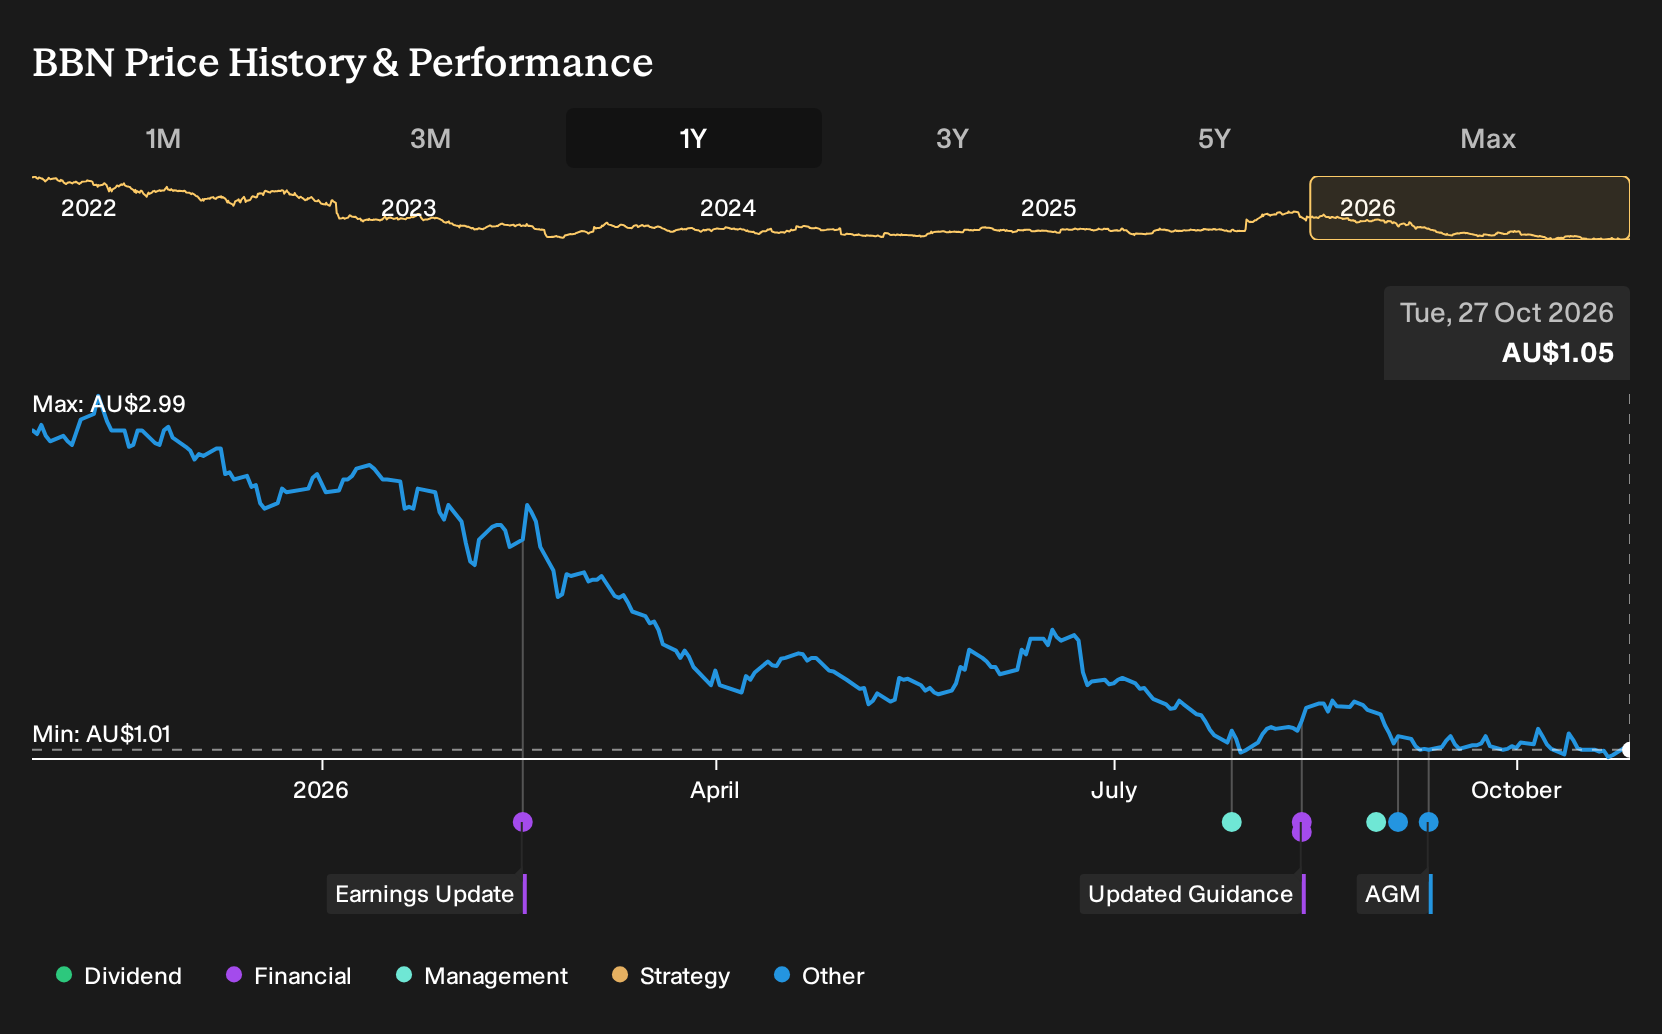
If you only glanced at Baby Bunting Group’s latest update, rising revenue and a higher net margin might look like progress worth paying for. Holding Baby Bunting Group over the past year would have meant a 62.4% loss, including dividends. If you had been weighing up an investment back on 27 October 2025, what in the bullish and bearish records already on file hinted that better results could still line up with such a heavy drawdown?
Baby Bunting Group has already moved. See which of 2 high quality undervalued stocks still trade below our estimates.
The Two Baby Bunting Narratives Investors Had To Weigh
The shares cost A$2.8 at the start of the period, and anyone looking at Baby Bunting Group then faced two very different stories about what that price implied.
On the optimistic side, the bull case saw store refurbishments, digital adoption and urban expansion supporting revenue assumptions of 10.9% a year and higher margins. This fed into a Fair Value of A$3.04, the price that scenario suggested the stock could justify.
The bear view pointed to declining birth rates, online rivals and store oversaturation, pairing 5.9% revenue growth assumptions with margin pressure and a Fair Value of A$2.4 based on a lower 15.7x future P/E.
What The Results Changed For Baby Bunting Group
The most concrete update came from Baby Bunting Group’s H2 2026 numbers. Total revenue moved from A$267.567m to A$284.642m, while net income rose from A$5.645m to A$9.357m and net margin shifted from 2.1% to 3.3%. That profitability step supported parts of the optimistic thesis, yet the moderate top line change kept the cautious case alive.
The real lesson is about which assumption you test first. When a thesis leans heavily on margin expansion, track reported net margin every period and compare it directly with the original forecasted level.
What Baby Bunting’s Fall Seems To Be Pricing In
Baby Bunting Group now trades at A$1.04, and the selected Narrative’s Fair Value sits above that level. The argument turns on whether refurbishment projects, media income and private label can support a larger, more profitable retailer without stretching the balance sheet.
For the 62.4% decline over the past year to mark an opening rather than a warning, a buyer today would need to believe refurbishments, returns on funds employed and New Zealand profitability can be maintained while growth projects remain funded from operating cash flow.
"The main thing that has to go right is for Store of the Future refurbishments, private label and exclusive products, retail media and New Zealand expansion to keep delivering sales uplifts, gross margin expansion and operating leverage while funding ongoing capital expenditure from operating cash flow."
The price and this Narrative do not agree. → Uncover what this Narrative says Baby Bunting Group is actually worth
Looking Beyond Baby Bunting
Baby Bunting Group is a very specific retail story. Your watchlist does not need to stop with one specialist chain.
Think about the quieter plumbing behind modern shopping. Every online basket, whether for prams or processors, leans on someone else’s digital rails.
One large technology ecosystem spends its time building that hidden layer. It runs cloud platforms, powers online marketplaces and experiments with consumer apps.
The same group also backs payment platforms, logistics networks and AI tools. If those digital foundations keep mattering to commerce, its role could look different from a simple online retailer today.
One Narrative has already put a figure on it. → Uncover the company trading 59% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com