


EN
How Investors Are Reacting To Hochschild Mining (LSE:HOC) Maintained Production Guidance
- Hochschild Mining reported Q3 2026 output with gold production of 62.56 koz and silver production of 1,753 koz, and confirmed full year guidance of 300,000 to 328,000 gold equivalent ounces remains unchanged.
- The mix of softer silver volumes, slightly higher gold output and a reaffirmed production target highlights management confidence in current assets, while operational work at Mara Rosa continues to reshape the group production profile.
- We will now assess how Hochschild Mining's decision to maintain 2026 production guidance could influence the broader investment narrative around the business.
Compare Hochschild Mining's production story with other precious metals opportunities by scanning our hand picked 35 elite gold producer stocks that could reshape your watchlist.
Hochschild Mining Investment Narrative Recap
To own Hochschild Mining, you need to believe the current production base plus Brazil and Peru growth projects can sustain healthy cash generation while capital spending remains elevated. The latest quarter showed slightly softer silver volumes and slightly higher gold output. Full year guidance staying at 300,000 to 328,000 gold equivalent ounces suggests the near term production story is broadly intact.
The key short term catalyst is execution at Mara Rosa and the cost path towards more normal all in sustaining cost levels after a high US$3,551 per ounce in H1 2026. The biggest risk is still timing and cost control on Monte do Carmo and Royropata. This guidance confirmation does not materially change that balance.
The most relevant update for this Q3 news is Hochschild Mining confirming it remains on track for 2026 production guidance of 300,000 to 328,000 gold equivalent ounces. That statement sits alongside nine month gold output of 192.89 koz and silver production of 5,627 koz. This frames how much has already been delivered against the full year target.
For you, the link to catalysts is about confidence in the bridge from today’s 2026 levels to the potential volume uplift expected from 2027 and 2028 projects. Meeting this year’s guidance supports the case that the operational base at Inmaculada, San Jose and Mara Rosa can fund and underpin Monte do Carmo and Royropata, even as all in sustaining cost guidance remains elevated.
What Analyst Forecasts Assume For Hochschild Mining
Hochschild Mining's narrative projects US$2.2b revenue and US$612.2m earnings by 2029. This implies 13.5% yearly revenue growth and an earnings increase of about US$311.5m from US$300.7m today.
Discover how Hochschild Mining's fair value indicates a 62% potential upside to its current price, which could close faster than many investors expect.
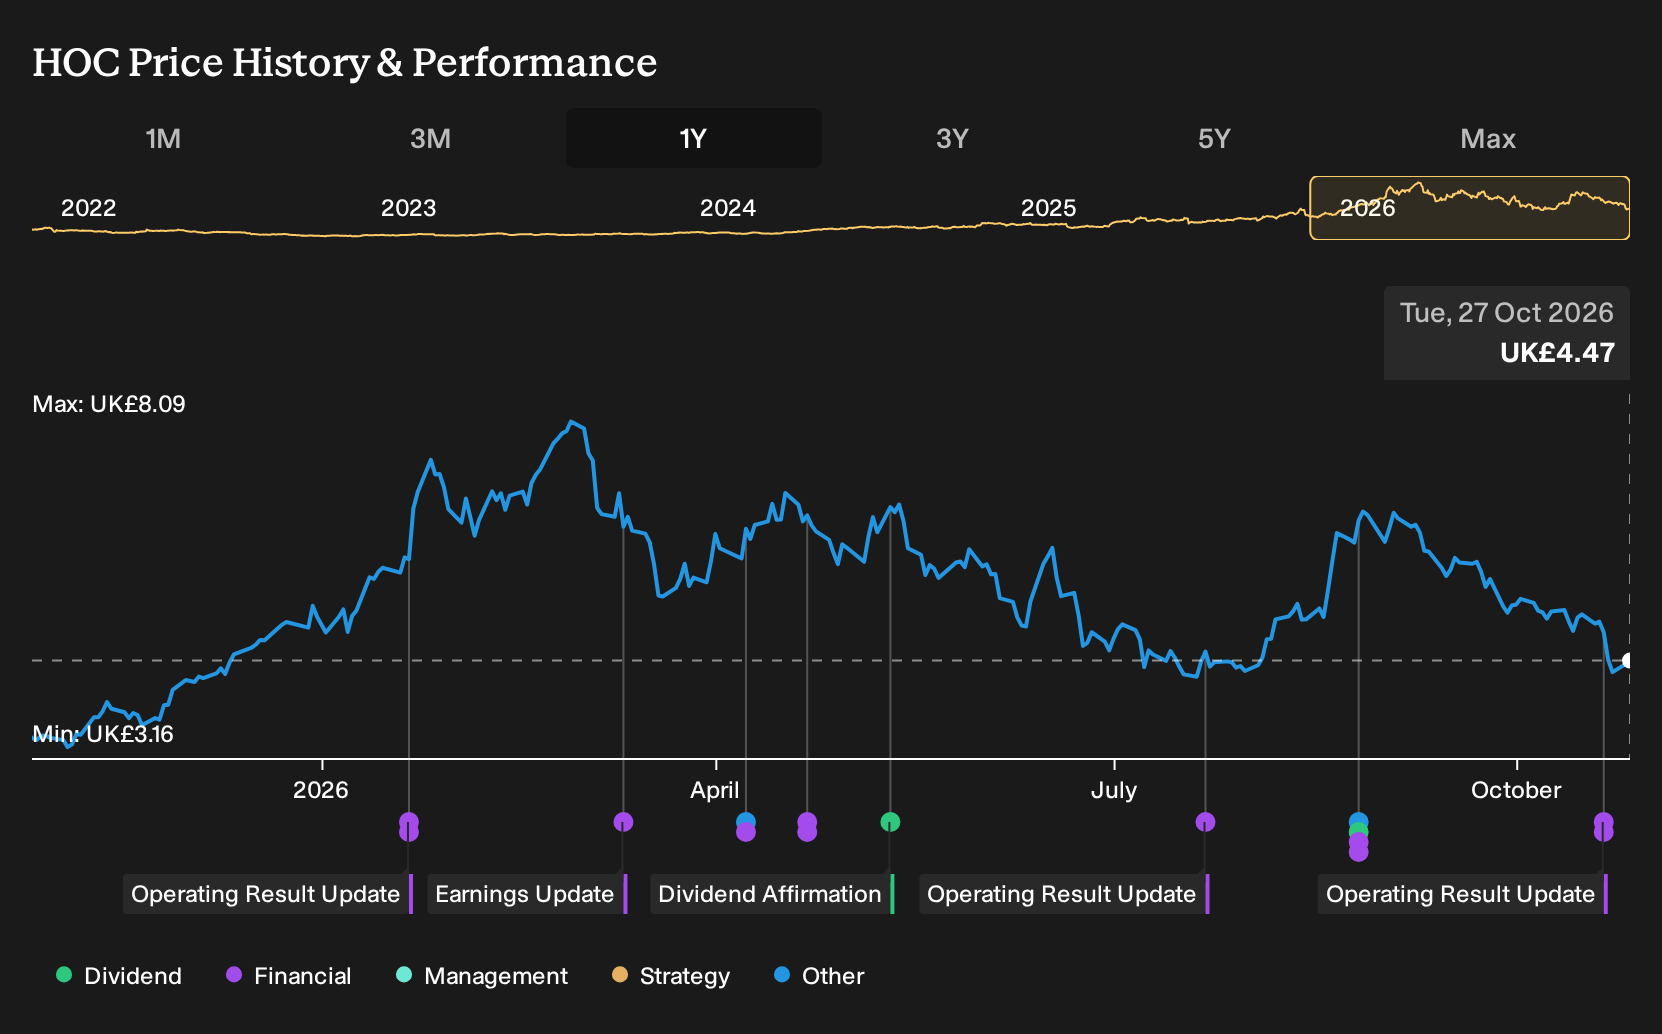
Exploring Other Perspectives
Some of the most optimistic analysts focus on a single catalyst for Hochschild Mining: Mara Rosa shifting from breakeven to a high margin hub. They were already modelling about US$2.3b in revenue and US$704.9m in earnings by 2029. Those forecasts came before this guidance confirmation, so you may see opinions move as assumptions get refreshed.
Explore 3 other Hochschild Mining fair value estimates, including one that suggests potential upside of up to 280% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hochschild Mining research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hochschild Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hochschild Mining's overall financial health at a glance.
Looking for more investment ideas beyond Hochschild Mining?
Once you have formed a view on Hochschild Mining, it can help to compare that thesis with other opportunities that share some of the qualities you care about, whether that is valuation, resilience or income.
- If you want candidates where quality and valuation line up, take a look at our curated 10 high quality undervalued stocks, which filters for businesses combining stronger fundamentals with more modest pricing.
- For readers who prioritise balance sheet strength and durability through different cycles, the list of solid balance sheet and fundamentals (10 results) can highlight companies with cleaner finances and healthier fundamentals.
- Income focused investors can scan the 5 dividend fortresses to see which higher yielding payers might warrant a spot on a watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com