


EN
Norfolk Southern (NSC) Earnings Put Its Valuation Back In Focus
Earnings jump puts Norfolk Southern in focus
Norfolk Southern (NSC) is back on investors’ radar after third quarter net income reached US$759 million, with earnings per share from continuing operations at US$3.38, ahead of last year’s US$3.16.
The recent earnings beat has arrived alongside a clear pickup in momentum for Norfolk Southern, with a 1-month share price return of 8.54% helping lift the stock to US$339.74 and a 1-year total shareholder return of 23.30% reinforcing a stronger longer term run.
Compare how Norfolk Southern’s earnings trend aligns with other rail and infrastructure plays by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Norfolk Southern has the earnings profile and dividend track record that many investors look for. After this latest jump in the share price, the real question is whether that quality is already fully reflected in today’s valuation.
Most Popular Narrative: 4.6% Undervalued
Norfolk Southern’s most followed valuation narrative points to a fair value of $356.11, slightly above the latest close at $339.74. This puts the recent earnings beat in the context of a stock that some investors see as not fully pricing in its longer term plan.
The current valuation implies the share price does not fully reflect this narrative that Norfolk Southern may be undervalued relative to its progress on productivity, industrial development projects and intermodal growth.
See why 11 investors see Norfolk Southern as 5% undervalued.
Result: Fair Value of $356.11 (UNDERVALUED)
Still, higher fuel costs, which management has guided as a headwind, and ongoing merger uncertainty with Union Pacific could both unsettle the Norfolk Southern narrative.
Find out about the key risks to this Norfolk Southern narrative.
Another View: Norfolk Southern on earnings multiples
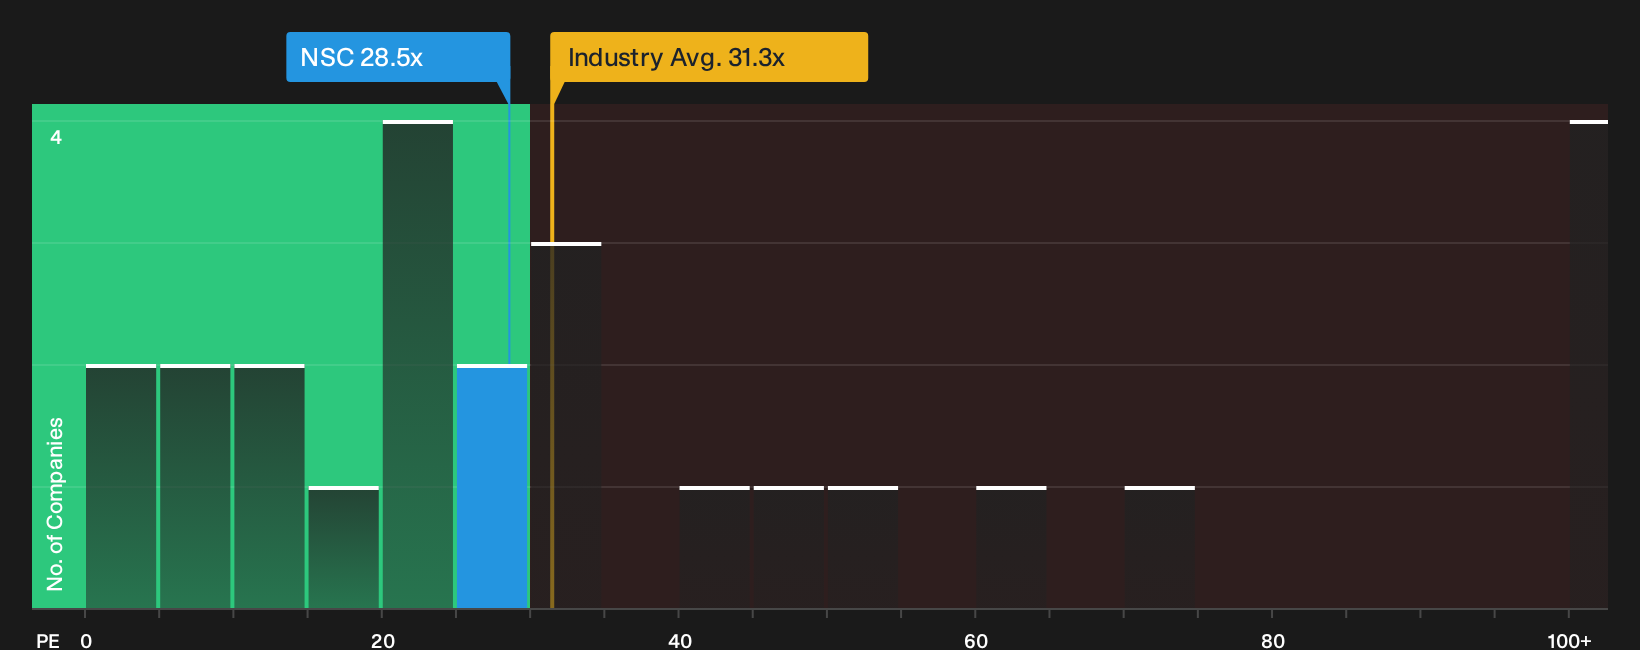
There is a different read on Norfolk Southern once the focus shifts to its current P/E of 28.5x. That figure sits below the broader US Transportation industry at 31.3x, yet above both the peer average of 25.6x and a fair ratio of 21x that the market could move toward over time. For investors, that mix points to some valuation risk if sentiment cools, even with earnings forecast to grow 10.52% each year. How comfortable are you paying today’s multiple for that profile?
To see how these numbers stack up in more detail, including how the current level compares with the fair ratio and sector benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Norfolk Southern so far. If you want to move quickly and build your own view from the ground up, start by weighing the 3 key rewards and 1 important warning sign
Looking for more Norfolk Southern investment ideas?
If Norfolk Southern has sharpened your focus, do not stop here. Broader context across other opportunities can help you pressure test your thesis and timing.
- Target stability first and scan a 30 resilient stocks with low risk scores that filters for businesses with resilience at the balance sheet and risk score level.
- Zero in on value and review a 29 high quality undervalued stocks that highlights companies combining strong cash flows with what may be compressed valuations.
- Hunt for under-the-radar potential and work through a 21 high quality undiscovered gems that surfaces quality stocks many investors may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com