


EN
Is Beam Therapeutics (BEAM) Undervalued On Early BEAM 301 Trial Results?
Beam Therapeutics (BEAM) presented new clinical data to investors after releasing initial Phase 1/2 results for BEAM-301 in glycogen storage disease type Ia, highlighting dose-dependent effects and an acceptable safety profile.
That data drop lands at a tricky moment for Beam Therapeutics, with the share price at $24.90 after a 1-day share price return of 4.67% but a year-to-date share price return that is down 8.25%, while the 3-year total shareholder return of 17.79% contrasts with a 5-year total shareholder return that is down 74.25%. This suggests that short bursts of renewed momentum have not yet offset the longer-term drawdown in investor confidence.
Scan Beam Therapeutics can be evaluated alongside other high-potential biotech plays by comparing it with a curated 34 healthcare AI stocks that are drawing attention around cutting-edge therapies and clinical catalysts.
The share price bounce after Beam Therapeutics’ BEAM-301 update has narrowed some of the obvious pessimism, so the question now is whether the current valuation still compensates you for the clinical and execution risk ahead.
Most Popular Narrative: 51% Undervalued
Beam Therapeutics is trading at $24.90 against a widely followed fair value estimate of about $51.07. As a result, the prevailing narrative sees a sizeable valuation gap that hinges on how its gene editing pipeline plays out over the next decade.
Beam Therapeutics is focusing on advancing their two core franchises in hematology and liver genetic diseases, with promising lead programs BEAM-101 for sickle cell disease and BEAM-302 for alpha-1 antitrypsin deficiency, both showing strong preclinical validation, which could lead to increased revenue from new treatments.
The BEACON trial for BEAM-101 demonstrated potential clinical differentiation, with rapid neutrophil engraftment and high HbF induction, suggesting that it could become a best-in-class treatment, thereby potentially increasing market share and impacting revenue.
See why 61 investors see Beam Therapeutics as 51% undervalued.
Result: Fair Value of $51.07 (UNDERVALUED)
Still, the narrative can break if busulfan safety concerns slow BEAM-101 adoption or if funding needs intensify before Beam Therapeutics reaches commercial scale.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: Beam Therapeutics Through The P/S Lens
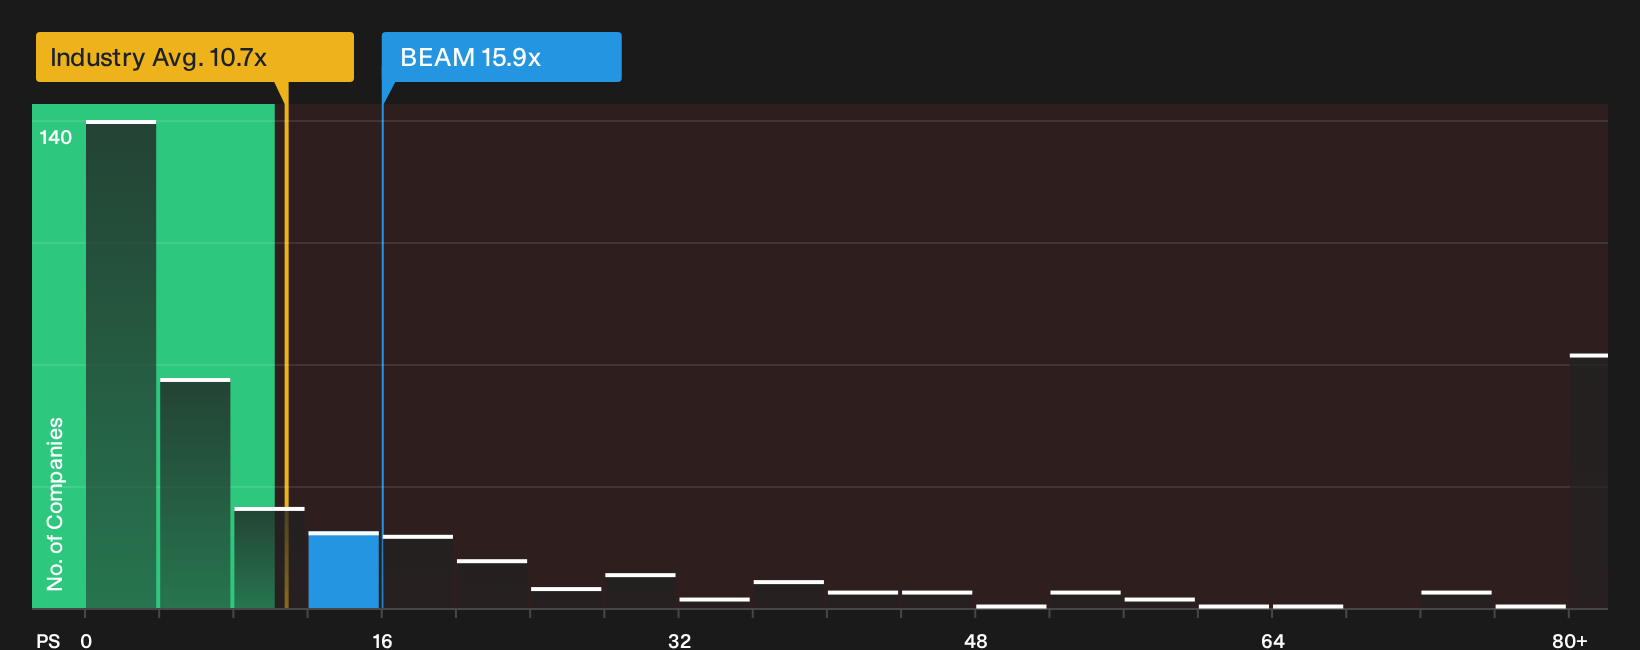
The fair value narrative for Beam Therapeutics points to an 18% discount using intrinsic estimates, yet the simple P/S tells a tougher story. The stock trades on a 15.9x P/S, richer than both the US biotech average at 10.7x and a fair ratio closer to 0.8x.
That kind of gap implies investors are paying a heavy premium today for potential future revenue, while the regression based fair ratio points to a level the market could move towards if enthusiasm cools. Is that a risk you are comfortable carrying given the clinical and funding hurdles still on the table?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Beam Therapeutics story so far. Consider the differing views in the market by weighing both sides of the ledger and reviewing the 3 key rewards and 2 important warning signs.
Looking for more Beam Therapeutics investment ideas?
Beam Therapeutics is only one piece of the puzzle, and widening your watchlist with a few focused filters can help you spot opportunities before the crowd notices.
- Target steady compounding by scanning companies with reliable payouts and yields through a curated 5 dividend fortresses that keeps income potential front and centre.
- Hunt for mispriced quality by running a 29 high quality undervalued stocks that highlights financially solid businesses trading below their assessed worth.
- Protect your downside by filtering for resilience using a 30 resilient stocks with low risk scores that screens for stocks with stronger balance sheets and more contained risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com