


EN
Performance Food Group (PFGC) On Private Brand Momentum And A Valuation Debate
Performance Food Group (PFGC) is back on investors’ radar after recent trading, with the stock closing at US$96.26 and short-term returns moving in different directions across the week, month, and past 3 months.
Over the past year, Performance Food Group has delivered a mixed picture, with the share price up 9.32% year to date but the 1-year total shareholder return down 3.86%. The 3-year and 5-year total shareholder returns of 66.66% and 109.67% signal longer term momentum that has cooled in recent months, as the 90-day share price return fell 17.48% even after a 5.14% 30-day rebound.
Scan how Performance Food Group stacks up against other potential rebound stories in our hand picked list of 29 high quality undervalued stocks with solid business fundamentals and room for sentiment to shift.
Bulls see Performance Food Group’s recent pullback as a reset after strong multiyear returns, while bears read it as a warning on sentiment. Which side do the current valuation markers support next?
Most Popular Narrative: 22% Undervalued
Performance Food Group’s most followed valuation view pegs fair value at $123.23, comfortably above the recent $96.26 close. This helps put the recent share pullback into context for anyone weighing the setup from here.
Rising private brand penetration, which reached roughly 54% of cases sold to independent restaurants in Q4 2026 and now spans about 25,000 SKUs across 85 brand families, creates scope for mix driven gross margin improvement and stronger earnings as volumes grow through these higher margin products.
See why 3 investors see Performance Food Group as 22% undervalued.
Result: Fair Value of $123.23 (UNDERVALUED)
Still, the narrative can break if Convenience revenue pressures persist or Cheney Brothers integration costs stay elevated for longer and squeeze Performance Food Group’s margin ambitions.
Find out about the key risks to this Performance Food Group narrative.
Another View: What P/E Says About Performance Food Group
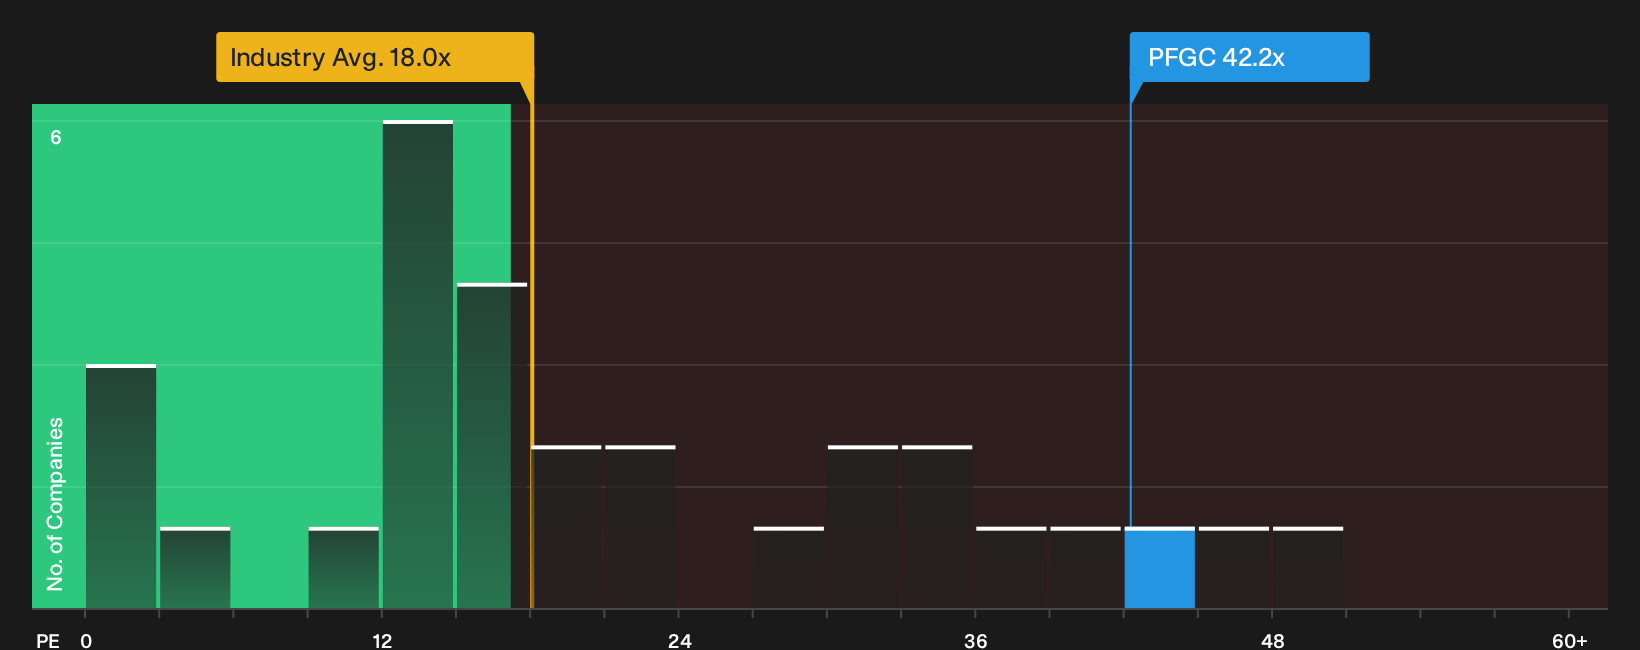
On the flip side of that undervalued fair value estimate, Performance Food Group trades on a P/E of 42.2x, compared with 18x for the wider US Consumer Retailing group and 34.1x for peers. The fair ratio model points to 31x as a level the market could move toward.
That gap implies investors are already paying a premium for PFGC, even before assuming the full analyst growth and margin story plays out. The question is whether you see more room for the multiple to stretch, or more risk that it drifts closer to the fair ratio over time.
For a closer look at how this pricing premium lines up against earnings power and peer valuations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and caution around Performance Food Group right now? Act quickly, review the full picture, and weigh both sides through 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Performance Food Group?
If Performance Food Group has you thinking about valuation, now is the moment to broaden your watchlist with a few focused, high conviction stock ideas.
- Target resilient compounding potential by scanning a curated 30 resilient stocks with low risk scores that prioritises companies with lower risk profiles and steadier fundamentals.
- Hunt for quality at a sensible price as you work through a carefully filtered 29 high quality undervalued stocks that screens for strong businesses trading below fair value estimates.
- Strengthen your income toolkit by reviewing a focused 5 dividend fortresses that highlights higher yielding payers with an emphasis on sustainability and balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com