


EN
Learn Why The Bull Case For Power Corporation Of Canada Stock Could Change Following Full Year Earnings
- Power Corporation of Canada reported full year 2025 net income of about C$2.63b, with contributions from insurance, asset management, wealth technology, and alternative asset platforms, supported by ongoing acquisitions and portfolio reshaping.
- The combination of substantial cash on hand, ongoing dividends, and share repurchases highlights how Power Corporation of Canada is using its balance sheet to support its long term capital allocation approach across subsidiaries and investment platforms.
- We will now look at how Power Corporation of Canada's C$2.63b net income shapes the broader investment narrative around its subsidiaries.
Compare how Power Corporation of Canada’s diversified earnings stack up against other balance sheet focused businesses by scanning our hand picked list of solid balance sheet and fundamentals (7 results).
Power Corporation of Canada Investment Narrative Recap
To own Power Corporation of Canada, you need to believe in a long term story built on diversified financial services, steady fee income, and disciplined capital allocation across its subsidiaries. The C$2.63b net income print supports that narrative, but it does not radically change it. The near term swing factor still looks tied to how insurance and wealth platforms sustain client inflows and keep expenses controlled.
The biggest risk is still concentration in Great West Lifeco and IGM Financial, plus execution risk in newer digital and alternative platforms that are not consistent fee engines yet. The latest results do not remove that dependence. They simply show the structure working as intended in the current period, while regulatory and competitive pressures remain very real.
With no fresh company announcements around this result, the most relevant reference point is management’s ongoing focus on capital deployment across subsidiaries. The current mix of dividends, buybacks, and balance sheet cash sets expectations that future capital recycling will matter at least as much as reported net income for sentiment around Power Corporation of Canada.
For you as a shareholder, that means paying close attention to how cash moves between Great West, IGM, Wealthsimple, and the alternative asset platforms. Any shift in payout policies, fundraising traction, or third party asset flows at Sagard and Power Sustainable could quickly influence perceived catalysts, particularly if fee related earnings from alternatives move closer to being a consistent contributor rather than a drag.
What The Analyst Framework Implies For Power Corporation of Canada
Analysts sketch a fairly specific roadmap for Power Corporation of Canada. They are assuming revenue grows by 8.1% a year over the next three years and that profit margins hold near 7.4%. Based on those assumptions, the current consensus points to earnings of about C$3.5b by 2028, compared with C$2.8b today. This implies an increase of roughly C$700m in annual profit if those estimates play out.
Power Corporation of Canada's narrative projects C$47.0b revenue and C$3.5b earnings by 2028. This would require 8.1% yearly revenue growth and an earnings increase of about C$700m from C$2.8b today.
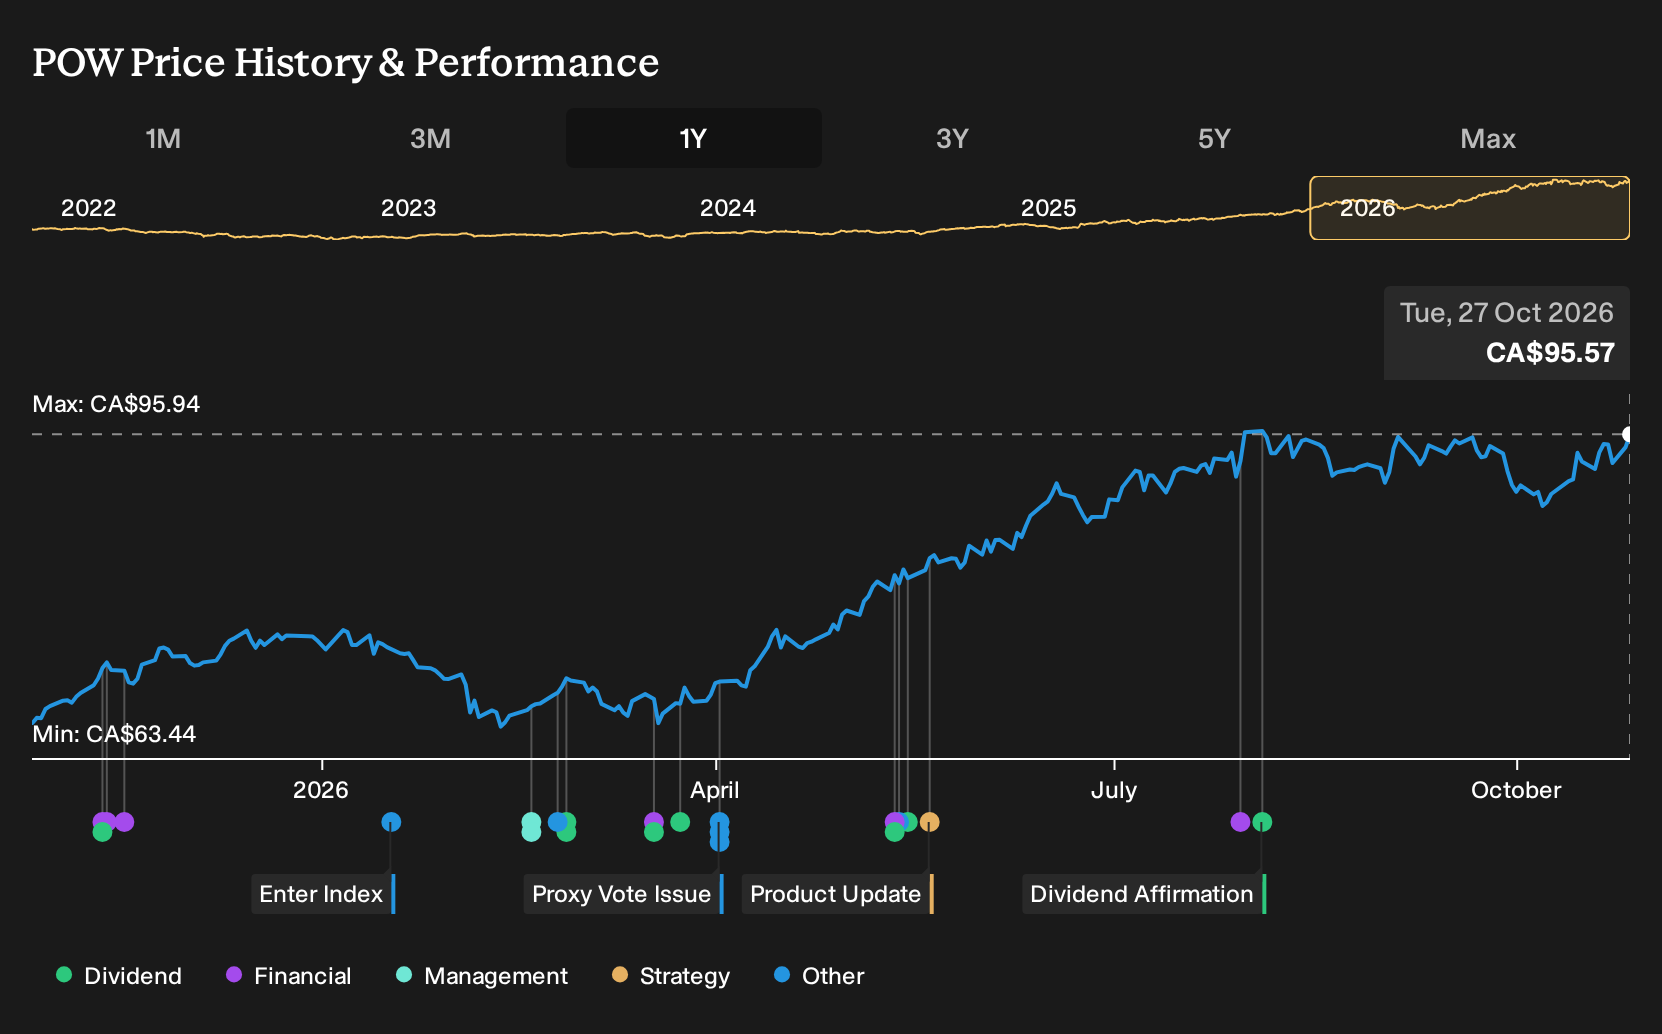
Uncover why Power Corporation of Canada's fair value indicates a 35% potential downside to its current price. This reflects a valuation premium that leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly C$62.5 to C$90.8, so private investors are assigning a wide range of outcomes to Power Corporation of Canada. Set that against concentration risk in Great West and IGM, as well as unproven alternative platforms, and you can see why opinions differ sharply. Explore those viewpoints before deciding where you stand.
Explore another Power Corporation of Canada fair value estimate, including one that suggests as much as 35% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Power Corporation of Canada research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Power Corporation of Canada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Power Corporation of Canada's overall financial health at a glance.
Looking for more investment ideas beyond Power Corporation of Canada?
If you want to stress test your thesis on Power Corporation of Canada, a smart next step is to line it up against other businesses with different income profiles, balance sheet strength, and return drivers using the Simply Wall St Screener.
- If capital preservation sits high on your list, compare Power Corporation of Canada with a 8 resilient stocks with low risk scores that prioritise resilient fundamentals and lower assessed risk levels.
- For investors hunting for quality at a reasonable price, scan a curated 3 high quality undervalued stocks that blend strong cash flows with more modest valuation multiples.
- Income focused readers can weigh Power Corporation of Canada against a 3 dividend fortresses that target yields of 5% or more alongside stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com