


EN
Mosaic Stock Faces Earnings Decline Ahead Of Quarterly Results
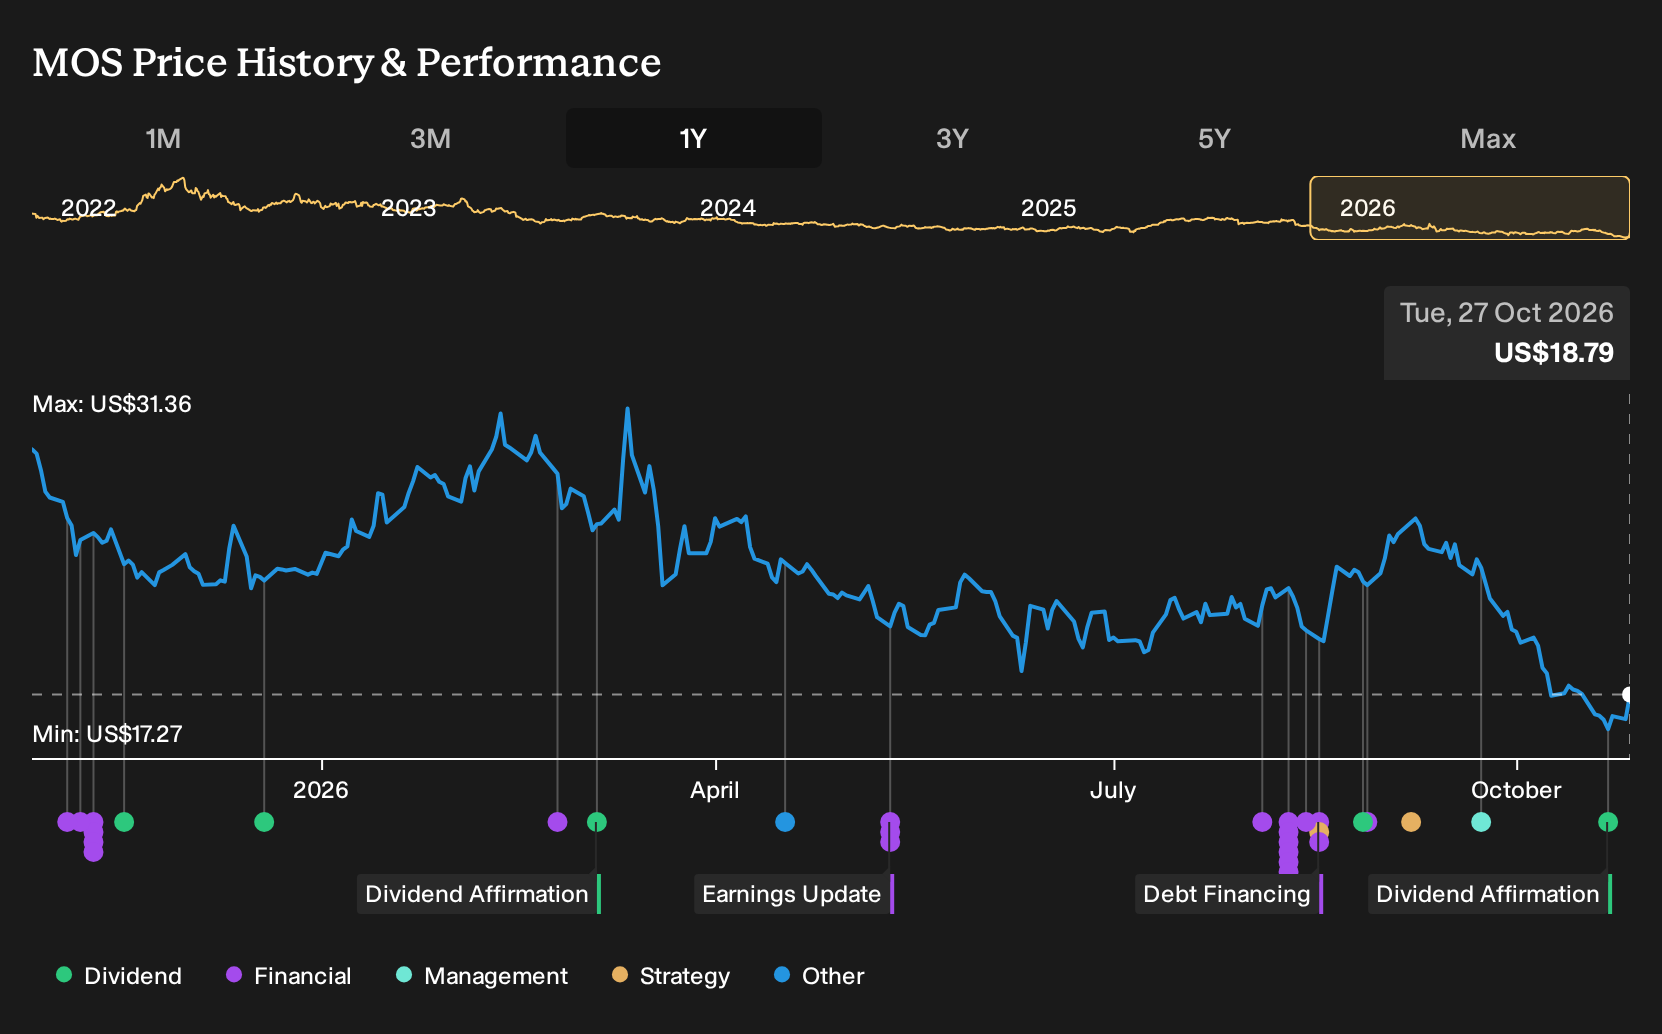
- Mosaic's board has declared a quarterly dividend of $0.22 per share, payable on December 18, 2026 to shareholders of record on December 4, 2026, and has clarified that any later dividends will depend on future board approvals.
- The expected year over year decline in earnings and revenue for the September 2026 quarter highlights current pressure on Mosaic's core fertilizer operations, even as it continues to return cash through dividends.
- This analysis now considers how Mosaic's investment narrative could be influenced by the expected earnings decline in the context of the maintained dividend.
Compare Mosaic's mix of earnings pressure and a maintained payout with other hand picked income opportunities by scanning 5 dividend fortresses, which may offer a different balance between dividend yield and business momentum.
Mosaic Investment Narrative Recap
To own Mosaic, you need to be comfortable with a fertilizer producer that is currently unprofitable and facing an expected earnings and revenue decline for the September 2026 quarter, yet is still reshaping its portfolio toward higher margin areas such as Mosaic Biosciences and rare earth projects. The near term swing factor is whether nutrient demand and input costs allow that mix shift to start to show up in cleaner earnings.
The biggest operational risk right now is that cash generation remains tight while capital expenditure and dividends stay heavy, which could squeeze flexibility if pricing or volumes soften further. In that context, the upcoming November 3 earnings release matters more for clarity on margins, sulfur and ammonia input costs, and any update on production curtailments.
The fresh US$0.22 per share quarterly dividend declaration is the clearest new data point, because it intersects directly with Mosaic’s already stretched dividend coverage and interest coverage metrics. Management is choosing to keep returning cash even while the business reported a loss of US$638.5 million and year to date operating cash flow of about US$270 million against roughly US$1.5 billion of combined capital expenditure and dividends.
For you as an income focused holder, the key question is whether that payout level remains compatible with the current balance sheet and the planned portfolio reshaping if earnings pressure persists beyond this expected weak quarter. The board has indicated that future dividends need fresh approval each time, so the catalyst to watch is any shift in tone around capital allocation once results for the September 2026 period are released.
Mosaic's narrative incorporates analyst expectations that annual revenue will grow by 2.5%, reaching about US$13.2b in 2029, with earnings of roughly US$674.0 million in that same year. This would represent an earnings improvement of about US$1.3b from the current loss of US$638.5 million.
Discover why Mosaic's fair value suggests a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Mosaic view leans hard on cash strain rather than phosphate demand. The most bearish analysts were modelling revenue of about US$11.4b and earnings of roughly US$422.7 million by 2029, compared with the higher consensus. Those estimates came before this dividend affirmation, so opinions may evolve as new data lands.
Explore 4 other Mosaic fair value estimates, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mosaic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mosaic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mosaic's overall financial health at a glance.
Looking For More Mosaic Investment Ideas?
If Mosaic has sharpened your focus on income, balance sheet strength, and earnings resilience, it can help to set it alongside a wider watchlist. Use the Simply Wall St Screener to scan other candidates that line up with the mix of dividends, quality, and risk you want.
- For investors who care most about dependable finances, run your eye over a list of solid balance sheet and fundamentals (24 results) that can help you compare Mosaic with peers that also keep debt and liquidity in tighter check.
- If you are hunting for potential mispricing, sort through a 29 high quality undervalued stocks that highlights shares where fundamentals and current pricing look out of sync.
- When income is the priority, weigh Mosaic’s payout against a 5 dividend fortresses that focuses on companies combining higher yields with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com