


EN
Could Rising Earnings Estimates Alter The Investment Case For Cousins Properties Stock (CUZ)?
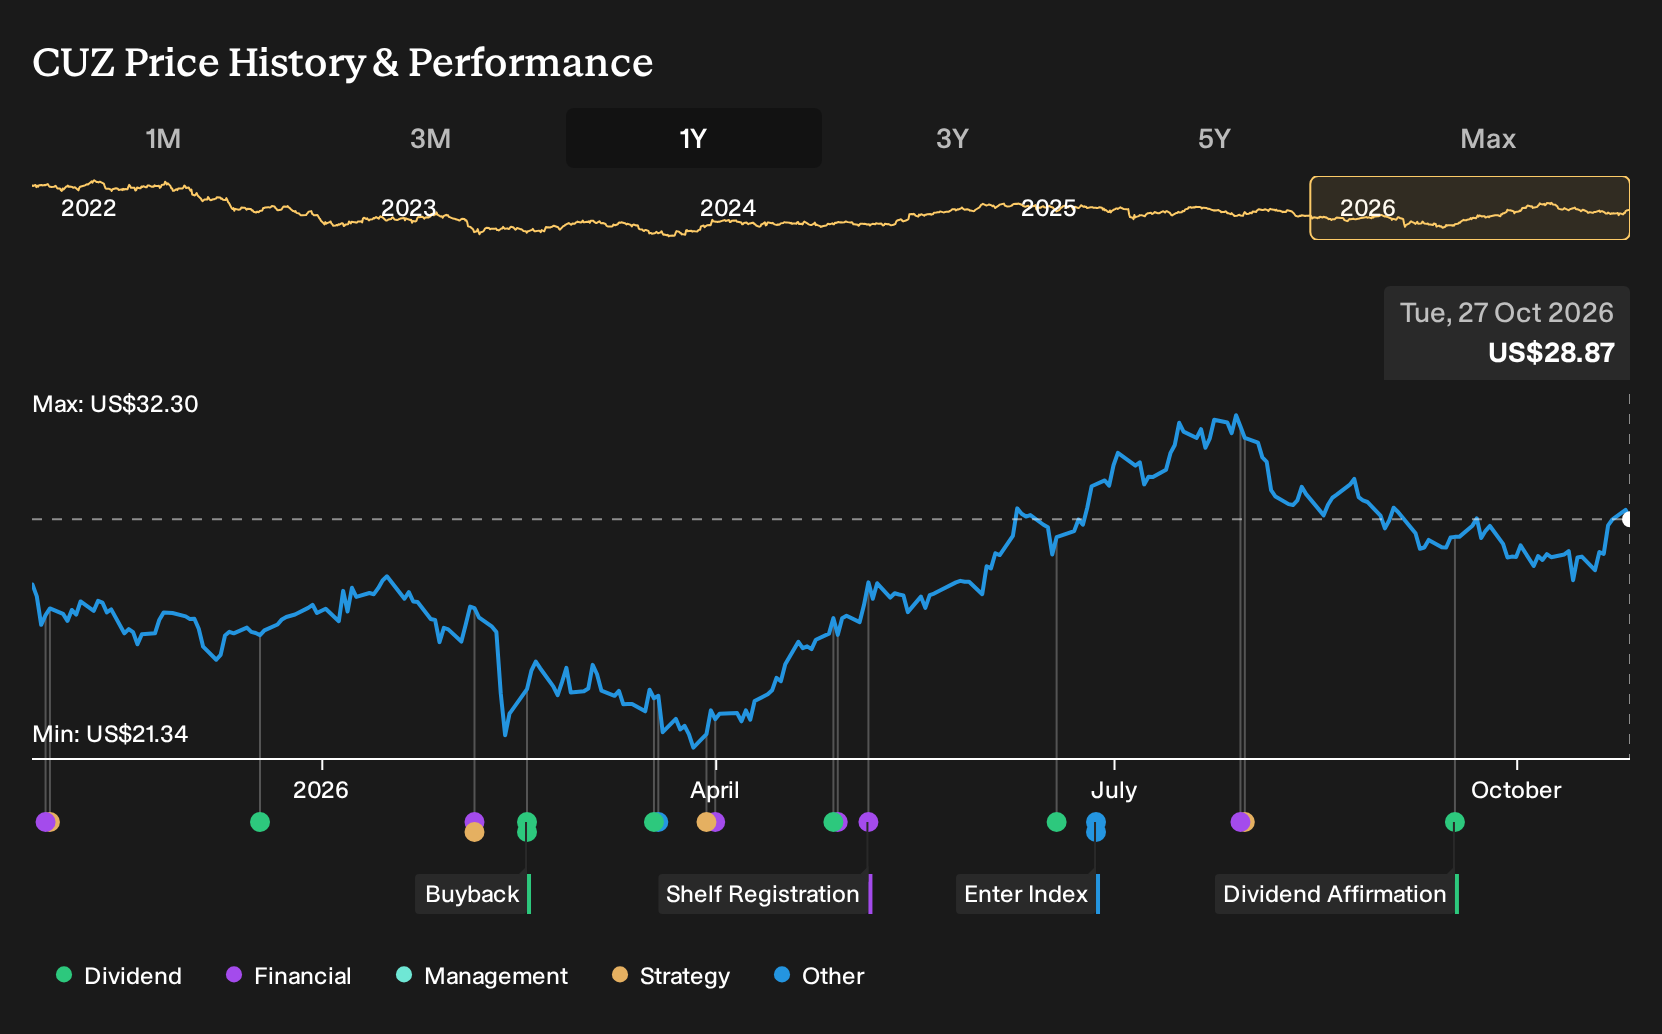
- Cousins Properties recently reported quarterly earnings for the September 2026 period, with consensus expectations calling for earnings of $0.73 per share and a 5% revenue uplift compared with the same quarter a year earlier.
- The upward revision to earnings estimates in the month before the release highlights how recent leasing and operating trends have shaped expectations for Cousins Properties’ Sun Belt office portfolio.
- This article examines how Cousins Properties’ investment narrative is influenced by these higher earnings expectations ahead of the quarterly release.
Scan for other office and income-focused real estate plays that might react around earnings season using our curated list of 5 dividend fortresses
Cousins Properties Investment Narrative Recap
Cousins Properties remains a conviction call on tenants continuing to prefer newer, high quality Sun Belt offices even as the broader office market adjusts to hybrid work. To stay comfortable as a shareholder, you need to believe those leasing pipelines keep translating into occupancy and rent roll ups across cities like Atlanta, Austin and Phoenix.
The near term catalyst is the September quarter print on October 29, where investors are watching how rent spreads, cash NOI and leasing volumes line up with expectations. Upward estimates may help sentiment but do not change the biggest current risk, which remains large upcoming lease expirations and potential downtime on move outs.
The most relevant recent marker for this earnings setup is the guidance and rent roll up data already on the table. Management highlighted 49 consecutive quarters of positive second generation cash rent roll ups and net effective rents in 2026 that sit between 8.5% and 16.8% above 2025 levels.
Those figures frame what investors are really checking in this release. You want to see whether new leases and renewals continue to price above expiring rents, because that supports revenue and cash NOI, even if headline occupancy moves around large expirations or if tenant downsizing from hybrid work weighs on the leasing funnel.
Cousins Properties Consensus Assumptions
Cousins Properties' narrative projects US$1.1b revenue and US$98.7 million earnings by 2029. This implies 3.5% yearly revenue growth and an earnings increase of about US$92.3 million from US$6.4 million today.
Uncover how Cousins Properties' fair value indicates a 16% potential upside to its current price before the market closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst, which is tighter return to office policies. They were pencilling in revenue of about US$1.2b and earnings of roughly US$140.3 million by 2029, far above consensus. Those forecasts were set before this Cousins Properties earnings report, so opinions may evolve.
Explore 2 other Cousins Properties fair value estimates, including one that suggests as much as 57% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cousins Properties research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cousins Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cousins Properties' overall financial health at a glance.
Looking For More Cousins Properties Style Ideas?
If Cousins Properties has you thinking more broadly about income, balance sheet strength and risk, it can help to scan a wider field of potential holdings using focused stock lists built around those themes.
- For income focused portfolios that still keep an eye on quality, check out our hand picked universe of 5 dividend fortresses that may fit a yield oriented plan.
- If capital preservation and a smoother ride matter most to you, filter the market using a 30 resilient stocks with low risk scores and see which businesses align with that mindset.
- When you want to get ahead of the crowd, search through a 21 high quality undiscovered gems that combines strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com