


EN
How Nasdaq Composite Removal At CECO Environmental Stock Has Changed Its Investment Story
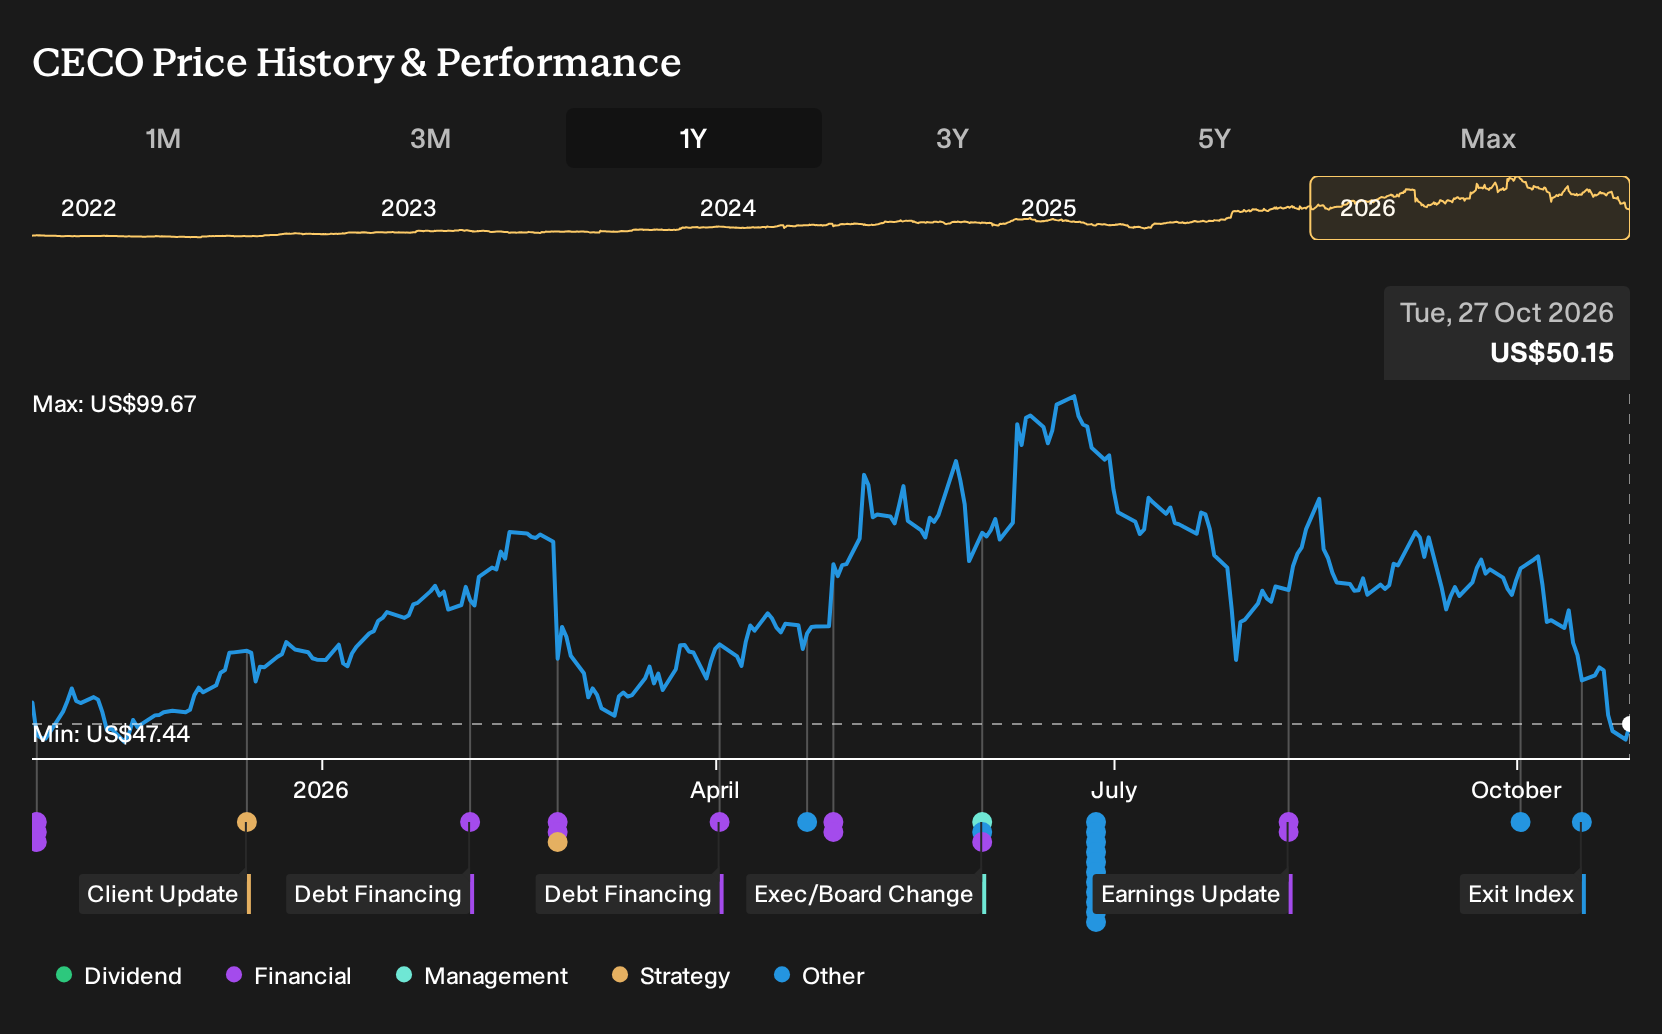
- CECO Environmental was removed from the NASDAQ Composite index in mid October 2026, following a reconfiguration of the benchmark’s constituents.
- The exclusion may matter for CECO Environmental’s fundamentals because index related selling can shift the shareholder base and influence capital access and funding costs.
- We will now look at how CECO Environmental’s investment narrative could be affected by its removal from the NASDAQ Composite index.
Compare how CECO Environmental’s situation stacks up against other potential turnaround stories by scanning our curated list of 21 high quality undiscovered gems featuring similarly under the radar profiles.
CECO Environmental Investment Narrative Recap
For CECO Environmental, the investment story hinges on whether the record US$1.82b backlog and US$8.5b pipeline actually turn into profitable projects. You need to be comfortable that integration of Thermon, mix shift into higher margin industrial water and process heating, and execution on long cycle power and gas projects offset current losses and a weak net income base.
The NASDAQ Composite removal mainly affects who owns the shares rather than how many scrubbers, heaters, or water systems CECO Environmental delivers. The bigger near term swing factor remains project timing and integration risk. The key threat is that delayed Middle East water work and any pressure on leverage combine to squeeze margins and cash generation.
With no fresh operational announcements tied directly to the index removal, the most relevant disclosures remain the earlier backlog and order figures. Record US$799m in quarterly bookings, a trailing book to bill above 2.0, and a backlog that extends into 2029 and 2030 all keep attention on execution, not index status, as the real driver.
That backlog and the Thermon deal sit at the center of the current catalyst set for CECO Environmental. Delivery of cost synergies, stability of large power and natural gas projects, and conversion of higher margin industrial water and data center related work into earnings all matter more for the thesis than index inclusion. Leverage and dilution history remain firmly on the risk list.
CECO Environmental's current analyst narrative points to revenues of US$2.5b and earnings of US$358.9 million by 2029, based on a forecast revenue growth rate of 41.0% per year and an earnings swing of about US$389.5 million from a loss of US$30.6 million today.
Uncover why CECO Environmental's fair value indicates a 95% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on CECO Environmental’s Thermon combination as the real swing factor, rather than the NASDAQ Composite exit. Before this index change, the highest forecasts were aiming for about US$2.3b of revenue and US$284.1 million of earnings by 2029. Those views could shift, so compare several narratives before deciding what this index move means for you.
Explore 3 other CECO Environmental fair value estimates, including one that suggests as much as 126% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking For More Investment Ideas Beyond CECO Environmental?
If you want to stress test your view on CECO Environmental and broaden your watchlist, use the Simply Wall St Screener to line it up against other opportunities with very different risk and return profiles.
- If you care most about quality and valuation discipline, start with a curated set of companies that currently screen as 29 high quality undervalued stocks to see where the market might be pricing in too much pessimism.
- If capital preservation comes first for you, compare CECO Environmental with a 30 resilient stocks with low risk scores and see which businesses better match your comfort level.
- If balance sheet strength is non negotiable in your process, focus on companies from the list of solid balance sheet and fundamentals (24 results) and look for those that combine resilience with consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com