


EN
Is Schneider Electric (ENXTPA:SU) Undervalued Following Its NVIDIA And HPE Physical AI Partnership?
Schneider Electric (ENXTPA:SU) has drawn fresh attention after announcing a collaboration with NVIDIA and HPE that targets Physical AI in heavy industry, with the goal of keeping data, security and costs tightly controlled at the edge.
Recent trading tells a mixed story. The 1 day share price return of 2.97% and a year to date share price gain of 2.38% come after a 30 day share price decline of 16.6%. At the same time, the 3 year total shareholder return of 75.66% and 5 year total shareholder return of 77.01% show that longer term holders in Schneider Electric have still seen strong compounding, despite a 1 year total shareholder return that is down 3.73%. The latest Physical AI partnerships and a recent €6b equity offering add fresh context to that shift in sentiment.
Scan Schneider Electric’s Physical AI move against a curated field of peers by comparing it with 55 AI infrastructure stocks that are shaping the next wave of industrial and data center buildouts.
Schneider Electric now trades around €242 after the equity raise, while analyst targets and intrinsic estimates point higher. Is that discount compensation for real risks, or has caution drifted too far?
Most Popular Narrative: 25.7% Undervalued
On the widely followed fair value view, Schneider Electric’s narrative estimate of €326.55 sits well above the latest €242.70 close. This puts the current Physical AI excitement in the context of a longer runway built around software, data and electrification.
The expansion of Schneider Electric’s integrated software, data and AI platform, combining AVEVA, OSIsoft PI, ETAP, Cognite, AiDASH and the planned PTC acquisition into an open, interoperable system from design through control and data intelligence, is set to increase the share of software and services and support higher recurring earnings and margin mix.
See why 121 investors see Schneider Electric as 26% undervalued.
Result: Fair Value of €326.55 (UNDERVALUED)
Still, the Physical AI story only holds if Schneider Electric absorbs the large PTC deal without balance sheet strain and lifts Industrial Automation margins as planned.
Find out about the key risks to this Schneider Electric narrative.
Another View: Schneider Electric Through The P/E Lens
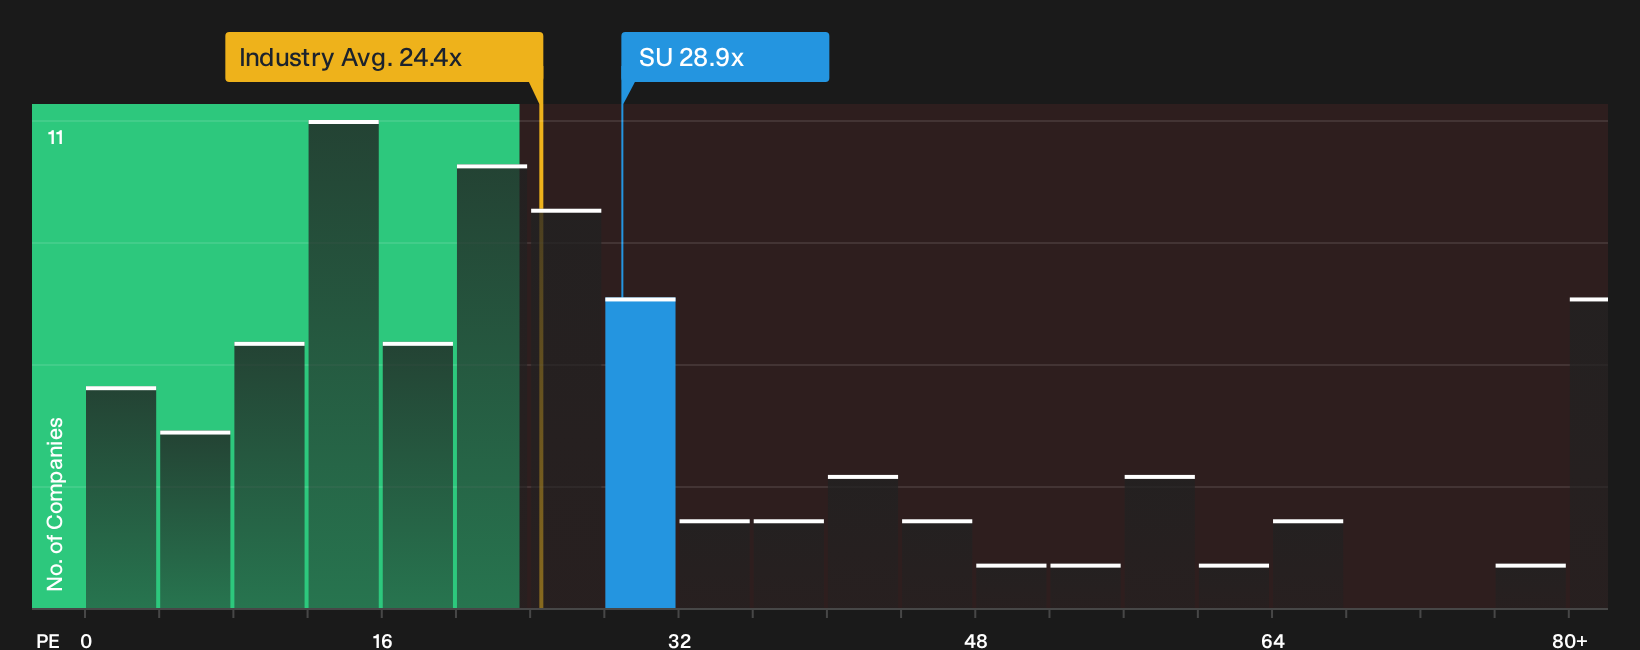
Switch the focus from fair value models to the simple P/E ratio and Schneider Electric looks less clear cut. The stock trades on 28.9x earnings, above both the European electrical industry at 24.4x and its peer average of 27.1x, yet still below a fair ratio estimate of 33.7x. That gap hints at a premium price with some embedded cushion, rather than a straightforward bargain or bubble. How comfortable are you paying up today for a profile that some metrics still frame as good value?
To see how that price tag stacks up against the underlying numbers, take a closer look at our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Schneider Electric is split, with meaningful risks on one side and clear potential rewards on the other. Move quickly, test the assumptions against your own thresholds, and then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Schneider Electric?
If Schneider Electric has sharpened your focus on quality and price, do not stop here. Use focused stock lists to pressure test your next moves.
- Target fresh value by scanning a 195 high quality undervalued stocks that filters for companies where price and fundamentals show a potential gap.
- Build staying power by reviewing a list of solid balance sheet and fundamentals (207 results) that can help anchor your portfolio in sturdier financial footing.
- Hunt for under-the-radar potential through a 610 high quality undiscovered gems that highlights quality businesses the broader market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com