


EN
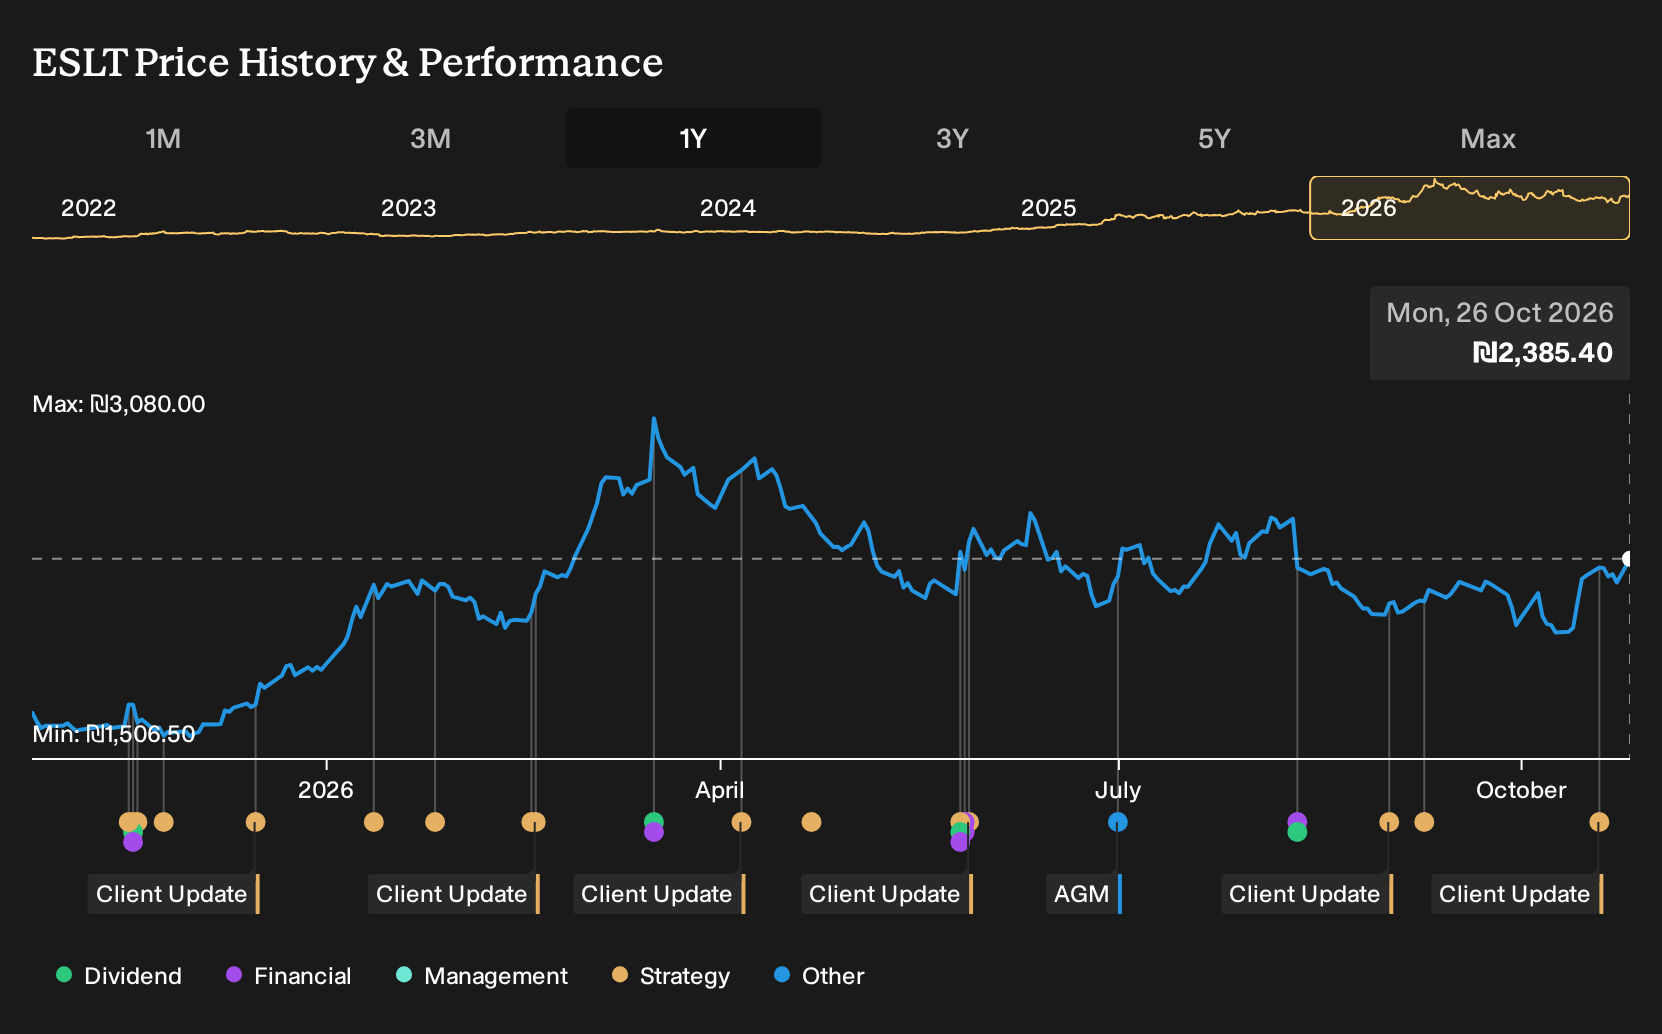
Elbit Systems Stock In Focus After $200 Million Asia Pacific Defense Contract Win
- Elbit Systems reported that it secured contracts of about $200 million from an Asia Pacific customer for airborne ISTAR payloads, training systems support and upgrades, and advanced Head Up Display solutions, with work scheduled over up to five years.
- The award deepens Elbit Systems' role in integrated airborne mission and training architectures, where long duration support work can influence visibility on future workload and resource planning.
- We will now examine how Elbit Systems' investment narrative is shaped by this multi year $200 million airborne ISTAR and training award.
Scan how other defence and aerospace contractors are positioning around long term contracts like Elbit Systems' recent wins by reviewing the hand picked 223 resilient stocks with low risk scores for comparison.
Elbit Systems Investment Narrative Recap
To own Elbit Systems, you need to be comfortable with a global defense contractor whose fortunes are tied to multi year procurement cycles, a record US$25.2b backlog and consistent demand for complex systems. The key near term swing factor is execution quality on those large programs, because slippage or cost creep can change how that backlog converts into cash and profit.
The new US$200m Asia Pacific ISTAR and training contracts add more visibility but are small against existing backlog, so they do not materially change the short term story. The bigger risk remains any cooling of defense budgets or mix shifts away from Elbit Systems product areas.
The recent US$235m contract for EXTRA MR rockets and PULS launchers in Europe sits close to the heart of the current thesis. It points to artillery and munitions demand that ties directly into Elbit Systems Land and rocket artillery exposure, where operational scale and factory throughput already matter for profitability and cash conversion.
For shareholders, the link between that rocket deal and the new airborne ISTAR award is contract quality and execution. A growing share of long duration, government to government programs concentrates operational risk. Any production or integration setbacks across artillery, avionics or training systems could pressure margins, even if headline backlog and order momentum remain strong.
Elbit Systems' current earnings of $636.0 million are set against analyst forecasts that point to $11.8b in revenue and $1.1b in earnings by 2029. This implies annual top line growth of 11.5% and an earnings increase of about $464.0 million from earnings today.
Uncover why Elbit Systems' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community span a wide band, from about 998 to roughly 2,968, which implies some investors see Elbit Systems at roughly triple the worth others do. With that kind of spread, and with fresh multi year contracts now in play, you are looking at a story where views can swing sharply as defense budgets, backlog quality and program execution all shift. Exploring those different Community models can help you stress test your own expectations and see how much risk and upside others are willing to underwrite.
Explore 3 other Elbit Systems fair value estimates, including one that suggests as much as 58% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Elbit Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Elbit Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elbit Systems' overall financial health at a glance.
Looking For More Ideas Beyond Elbit Systems?
If the Elbit Systems story has you thinking about where else long contract visibility and balance sheet strength might matter, it can help to line it up against a broader watchlist of opportunities.
- For investors who want income to be a core part of their returns, scan through 224 dividend fortresses that meet a 5%+ yield hurdle while aiming for resilience.
- If capital preservation is high on your priority list, compare Elbit Systems to a curated 223 resilient stocks with low risk scores that score well on financial durability.
- For those hunting for under followed opportunities with strong fundamentals, widen the search with a 610 high quality undiscovered gems that may not yet be widely tracked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com