


EN
The Bet Transocean Holders Made
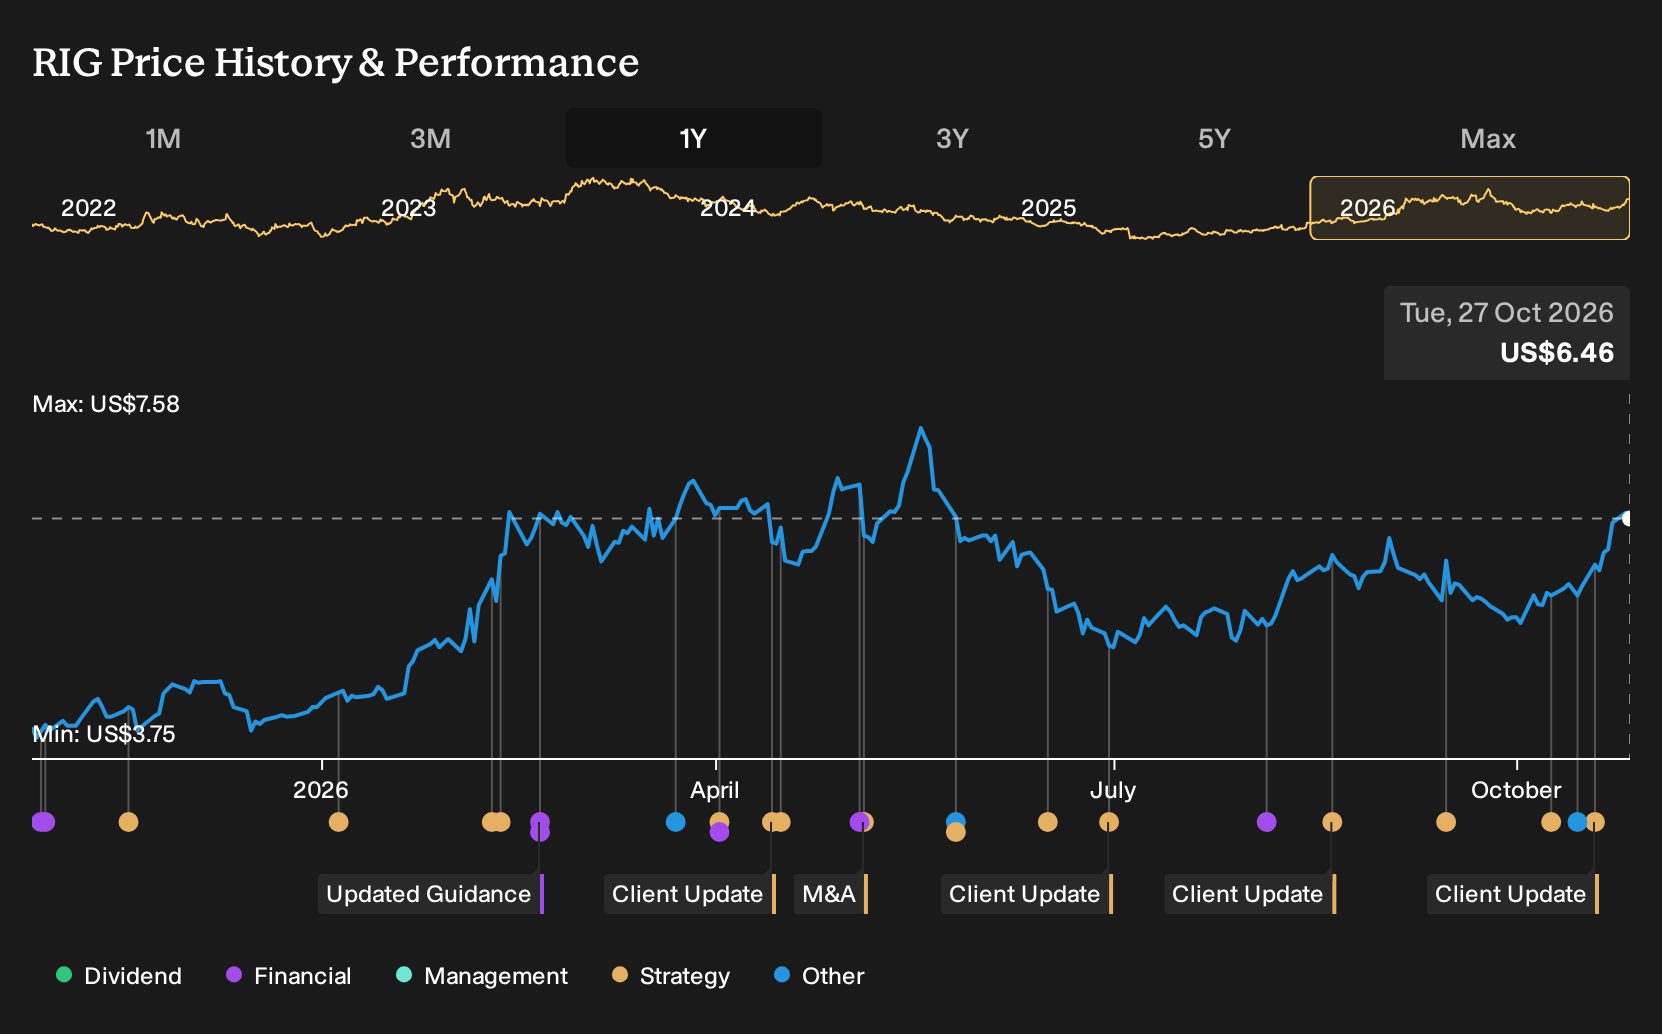
If you had decided to back Transocean before the Valaris merger headlines, Equinor’s multi-rig pact, and a backlog edging past US$7.7b, the payoff would now look very different. Holding Transocean over the past year would have returned 72.3%, including dividends. If that kind of swing hinged on Q2 2026 profits flipping from deep losses a year earlier, what exactly were early buyers weighing when debt, regulation and offshore demand were all pulling in different directions?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Transocean harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument Transocean Investors Were Actually Having
The shares cost US$3.86 at the start of the period, and anyone looking at Transocean then was really choosing between two clean but conflicting stories.
The bullish narrative put fair value at US$5.5, 42% above the start price, and hinged on revenue growth of 2.0% a year and a future P/E assumption of 35.2x as ultra deepwater demand tightened.
The bearish view set fair value at US$2.5, 35% below the start price, and emphasized falling revenue of 3.4% a year and the strain from high debt and rising regulatory costs.
What The Results Changed For Transocean’s Case
The key datapoint was Q2 2026, when Transocean moved from a loss of US$938 million in Q2 2025 to a profit of US$170 million on slightly lower revenue of US$966 million versus US$988 million. Net margin swung from a deeply negative 94.9% to a positive 17.6%. This supported the more optimistic view on profitability even as the top line drifted.
For another stock, that lesson is straightforward. When a debate hinges on margins, track whether profit and net margin move in the forecast direction even if sales do not, and check whether that shift holds for more than one reporting period.
What Transocean’s Run Now Asks You To Believe
Transocean now trades at US$6.46, after a 72.3% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which reflects a view that the recent backlog wins and the Valaris deal leave less room for error on execution and costs.
The same Narrative argues that today’s valuation leans on strong rig utilization, cleaner finances and successful Valaris integration. A buyer at today’s price is effectively assuming that backlog turns into sustained cash generation. The key question is how rising freight, fuel and capex may affect that cash outcome.
"The numbers imply that Transocean’s current share price already prices in very strong utilization, successful balance sheet repair and full delivery of the planned Valaris cost synergies, which leaves limited room for disappointment if offshore activity or contract economics soften."
One Narrative disagrees with today's price. → See where this Narrative says Transocean should trade
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 46% below our estimate - turns a large backlog of complex technology projects into installation and service revenue.
- Company 2 - 22% below our estimate - ties an artificial intelligence software ecosystem to cloud, productivity, security and developer tools.
- Company 3 - 31% below our estimate - targets artificial intelligence data centre demand with specialised processors linked to proprietary software.
That is three of the list. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com