


EN
Elastic (ESTC) Stock Could Be 32% Undervalued Following Recent AI Selloff
Elastic has rallied strongly in 2026, and with the stock now reflecting a sizable year to date gain, the key issue for you is whether its current price lines up with the cash flows the business can produce.
- The share price is up 45.4% year to date, which puts fresh focus on whether investors are paying a level that its future cash generation can reasonably support.
- Recent reports of solid revenue growth and broader adoption across search, observability and security suggest Elastic's cash flow outlook may benefit if those trends persist.
- If you'd rather focus on earnings, this one's for you. See why Elastic's 29.5x P/E tells a different valuation story.
For investors, the debate is whether Elastic's current valuation is justified by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
If you want to see how Elastic's cash flow story compares with other opportunities in the market, it can help to line it up next to 29 high quality undervalued stocks.
Is Elastic a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model used here focuses on the cash Elastic can return to shareholders over time. Based on the latest figures, the business produced trailing twelve month free cash flow of about $349.1 million, and the model then assumes that this stream grows over the coming decade rather than shrinking.
Forecast free cash flow is projected to reach the low hundreds of millions of dollars in the next few years and then build further toward the end of the ten year window. This supports a two stage Free Cash Flow to Equity setup with a stronger early phase and a steadier second stage. Against a current share price of $105.52, those projected cash flows translate into an estimated intrinsic value that the model suggests is substantially above where the stock trades today. The recent tech sell off linked to AI funding concerns helps explain why the price stays below intrinsic value despite Elastic still generating positive free cash flow. Find out what Elastic could be worth using our Discounted Cash Flow (DCF) estimate.
The Elastic Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Elastic pick up where that valuation puzzle leaves off and explain which assumptions on Elastic's growth, profitability and earnings profile would need to hold for the shares to be worth meaningfully more or less than today. These Narratives are available on the platform's Community page. Each Narrative presents fair value as a clear thesis about how the business might develop over time, allowing you to watch that idea play out against future results.
Elastic attracts two very different storylines, one arguing the long term AI and security opportunity is underappreciated while the other sees execution risk already priced in.
Bull case: roughly fairly valued
"Deepening long term enterprise commitments, reflected in more than 1,800 customers with at least US$100,000 in ACV, over 37% of these using Elastic for AI use cases and cRPO and RPO growth above 20%, indicate that Elastic is increasingly embedded as core AI, observability and security infrastructure..."
Discover why this Narrative puts Elastic at roughly fairly valued.
Bear case: 25% overvalued
"Although Elastic is reporting rapid uptake of AI features among large customers, the slight decline in net expansion rate to 111% in Q1 FY27 suggests AI and agentic workloads on proprietary data may not yet be driving the broader seat and usage growth implied in prior models..."
Explore why this Narrative puts Elastic at 25% overvalued.
One more Elastic check that sits beside the valuation work
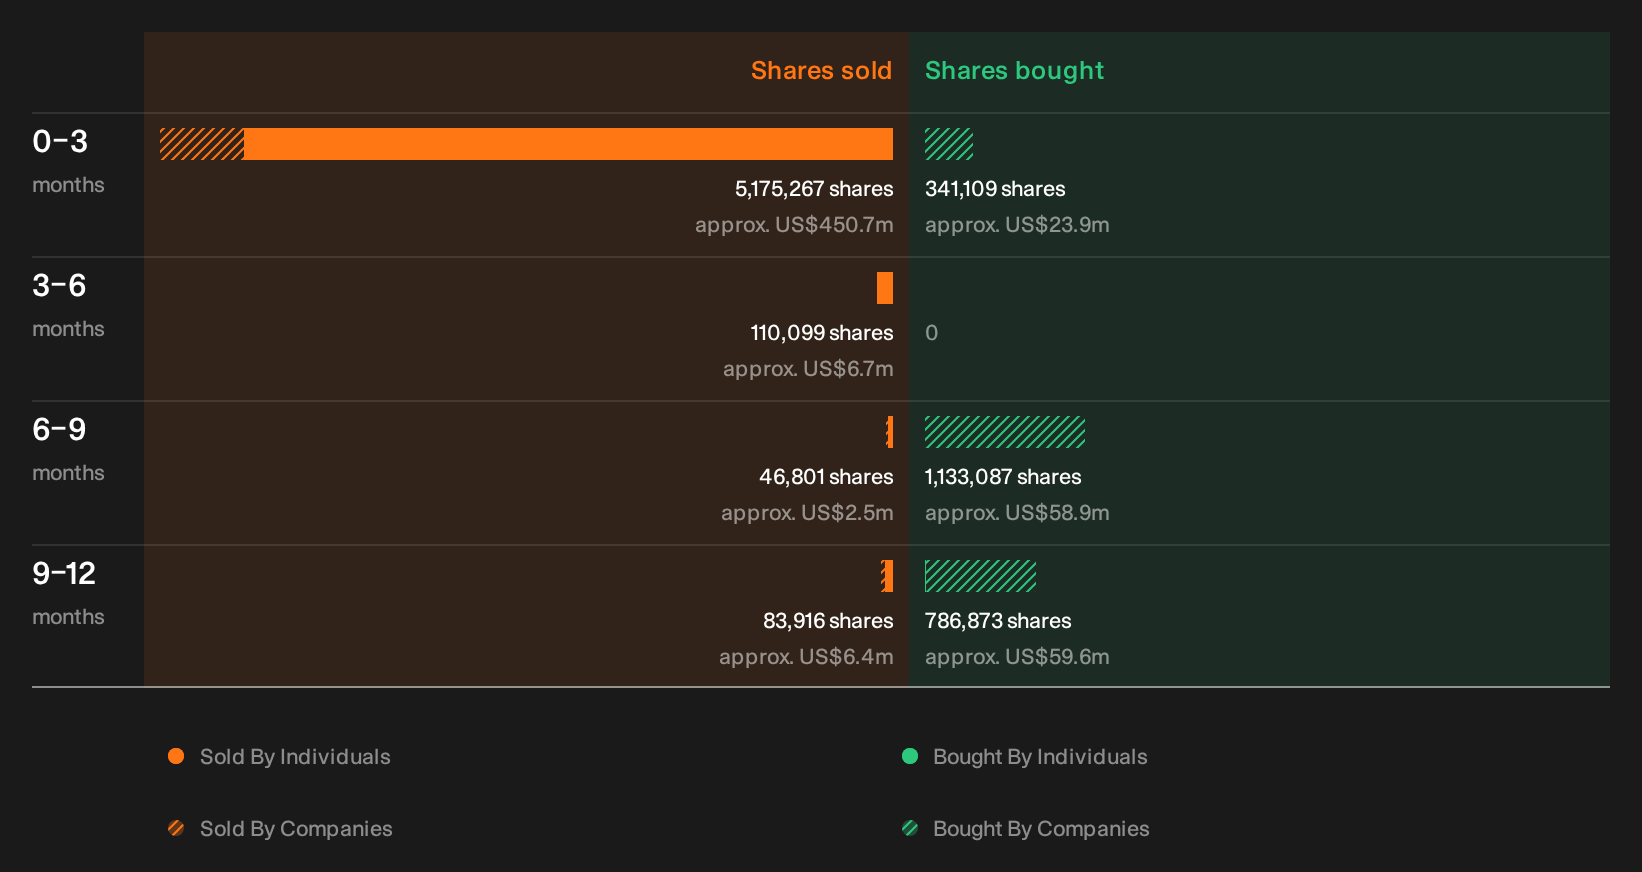
Price and cash flow only tell part of the story for Elastic, because recent management share dealings also sit on the table for you to review, including who sold, how much, and what that might signal. See the recent insider selling flagged for Elastic.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com