


EN
Does Mitie Group (LSE:MTO) Already Price In Its Earnings Strength?
Mitie Group has delivered a strong share price run over recent years, which naturally raises the question of whether the current valuation is still in line with what its earnings can support. With that kind of backdrop, you need to ask if the recent price level is being driven more by the profit profile of the business or by investor enthusiasm.
- Over the past 5 years the stock has gained 268.3%, which puts a lot of weight on whether the underlying earnings story is solid enough to justify that kind of compounding.
- The business model relies heavily on converting contract revenue into steady profit and cash flow, which can influence how comfortably earnings back up the current share price.
- Your read on Mitie Group is one view; the desks covering it have another. See what analysts think Mitie Group's shares could be worth.
For investors, the debate is whether Mitie Group's current share price is adequately supported by the level and quality of its earnings today.
If you want to stress test the same earnings question beyond Mitie Group, it can help to scan a wider field of 10 high quality undervalued stocks.
Does Mitie Group Look Pricey on Earnings?
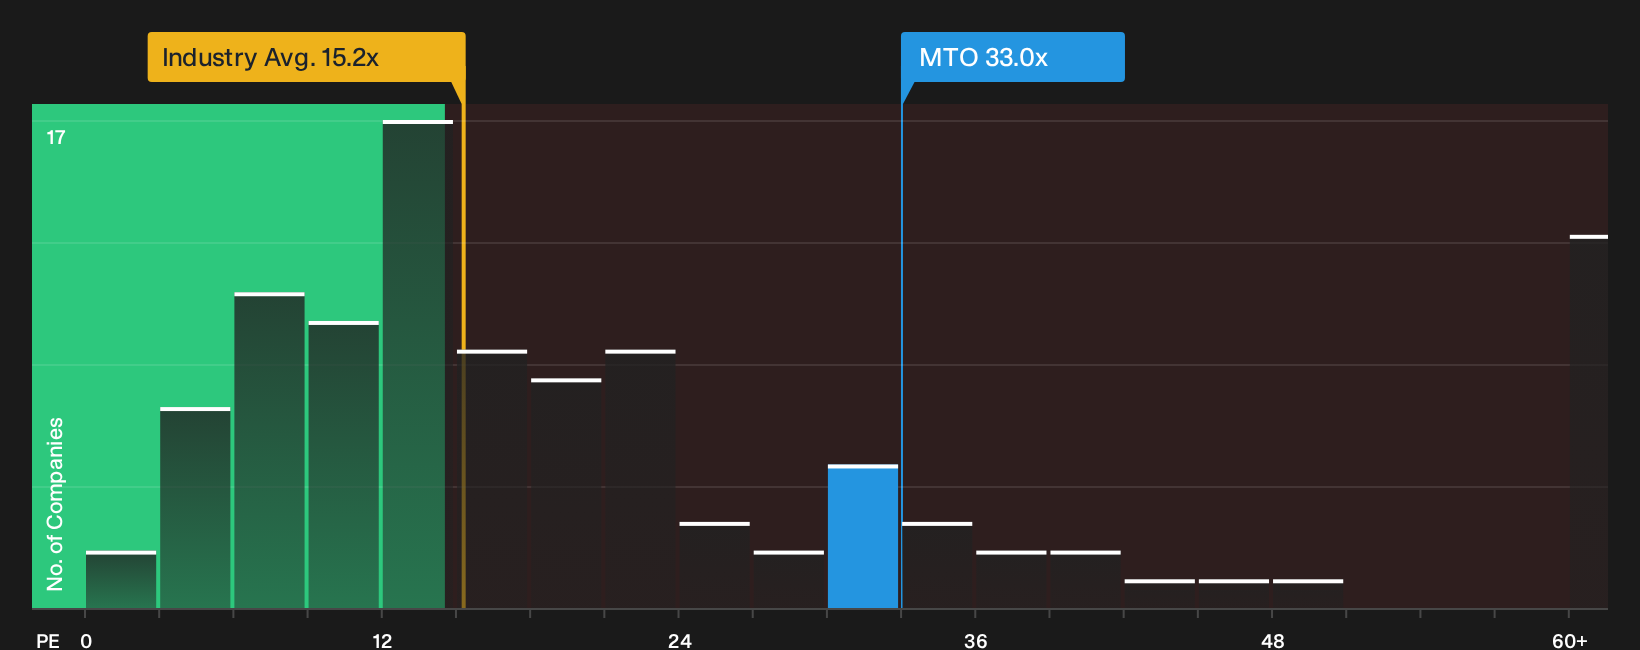
The P/E ratio suits Mitie Group because profit is a key lens for a contract heavy services operator. On that measure, the shares trade on about 33.0x earnings, which is well above the Commercial Services industry average of roughly 15.1x. Compared with a peer set closer to 20.6x, the stock also changes hands at a clear premium.
A tailored fair value multiple for Mitie Group, which factors in its specific growth profile, margins, scale and risk, sits below the current 33.0x level. That gap suggests investors are paying up for the existing earnings stream and are willing to ascribe a richer tag than the model implies on today’s fundamentals. Anyone looking at the stock has to decide whether the quality and durability of those earnings fully justify that higher P/E. Explore the numbers behind Mitie Group's P/E valuation.
The Mitie Group Narrative: What Would Justify Today's Price?
Narratives on Mitie Group pick up where this valuation question leaves off and explain what sort of future growth, profitability and earnings path would need to hold for the stock to appear materially higher or lower than today's price on Simply Wall St's Community page. Each scenario assigns a fair value to a specific mix of potential catalysts and risks, allowing you to see over time which version of Mitie Group's story is actually unfolding.
The Simply Wall St community is split on how much more Mitie Group can really offer from here, even if both camps describe it as roughly fairly valued.
Bull case: roughly fairly valued
"Rollout of AI, the MITIEverse command centre and agent based automation across workforce and workflow management aims to reduce back office and operational costs at scale, which can support margin progression and potentially improve free cash flow and earnings..."
Discover why this Narrative puts Mitie Group at roughly fairly valued.
Bear case: roughly fairly valued
"The current valuation and agreed £3.1b cash offer imply that the share price already reflects a fair view of Mitie Group’s delivery on its plan and future cash returns..."
Explore why this Narrative puts Mitie Group at roughly fairly valued.
One more Mitie Group cross check before you stop at the P/E
Price comparisons tell you what investors pay today, but the next question is how professional analysts currently sketch Mitie Group a few years down the road. Explore where analysts expect Mitie Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com