


EN
Earnings Beat Might Change The Case For Investing In Merit Medical Systems Stock (MMSI)
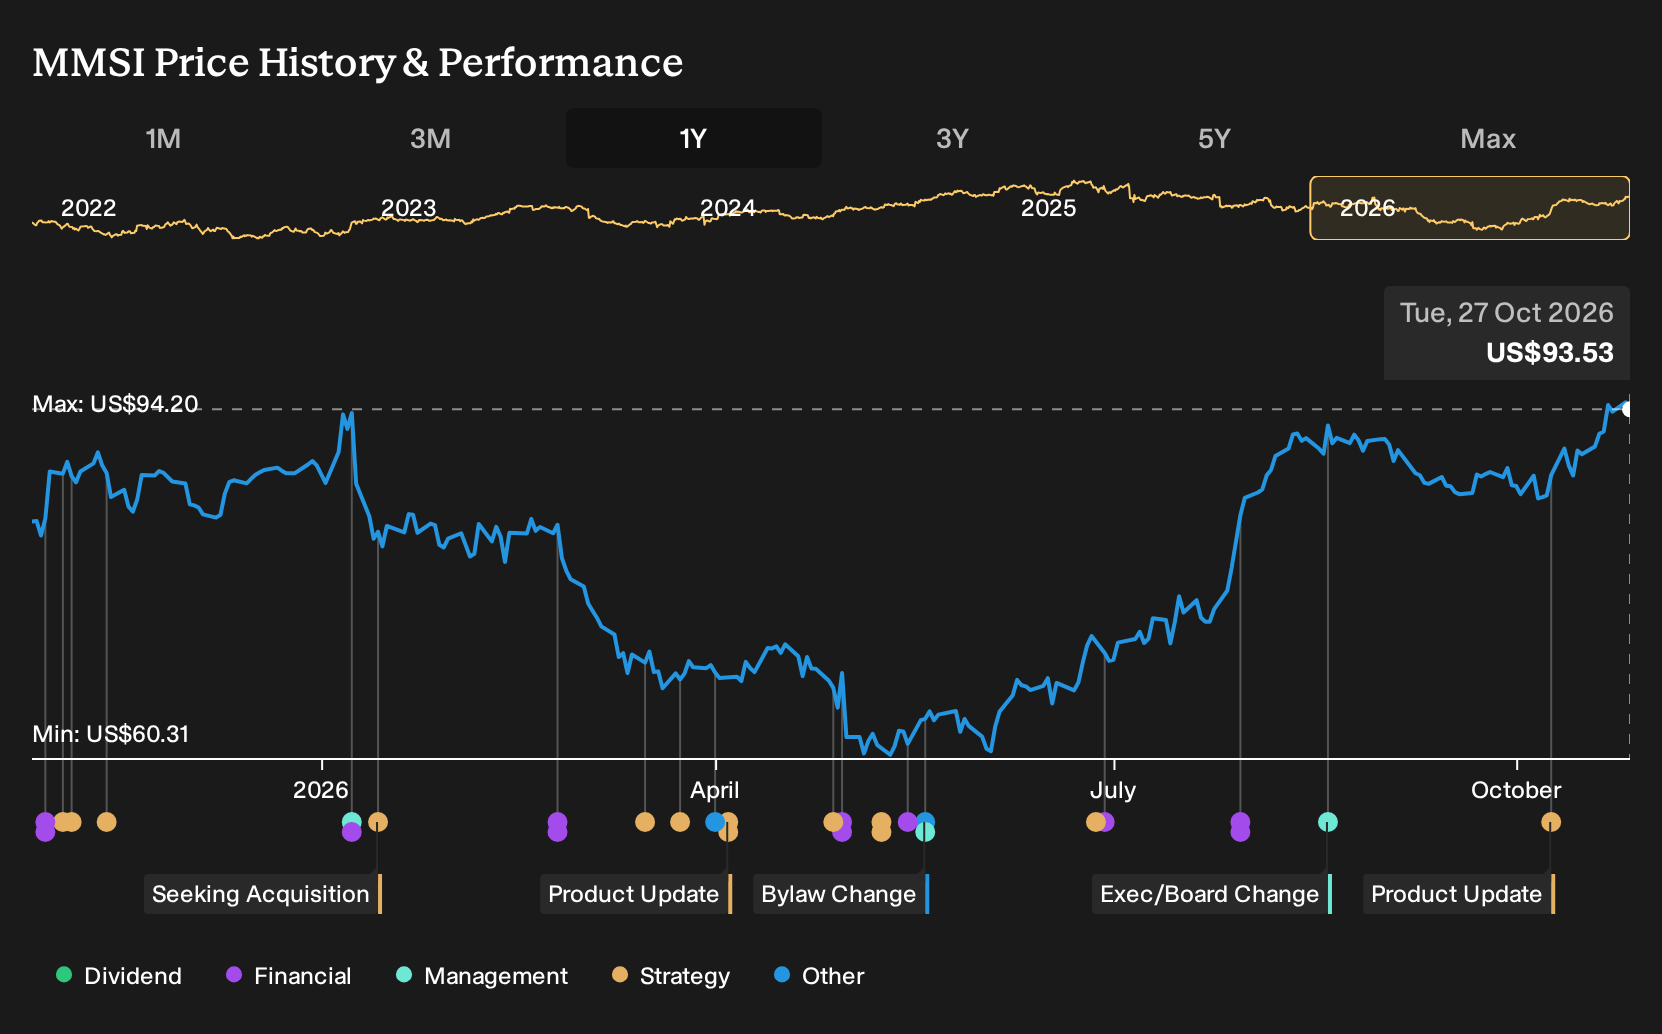
- Merit Medical Systems reported past Q2 2026 adjusted EPS of US$1.19 and revenue of US$418.8 million, both above analyst estimates.
- The scale of the earnings beat relative to consensus highlights how Merit Medical Systems converted its product mix and efficiency programs into stronger profitability.
- We will look at how Merit Medical Systems' sizable Q2 2026 earnings beat fits into the broader investment narrative around margins.
Scan beyond Merit Medical Systems and see how other hand-picked medical and healthcare names with similar earnings momentum stack up using our 29 high quality undervalued stocks
Merit Medical Systems Investment Narrative Recap
To own Merit Medical Systems, you need to be comfortable with a story built around margin work, product mix and disciplined capital use rather than rapid top line expansion. The latest Q2 2026 beat on both adjusted EPS and revenue reflects that the efficiency programs and platform focus can appear in near term profitability.
The key short term swing factor remains whether Merit Medical Systems can sustain this higher margin profile while absorbing known tariff costs and softer regions like China. The biggest risk still lies with product specific and geographic pressures, including WRAPSODY CIE reimbursement and volume based purchasing, which the latest quarter does not fully resolve.
The most relevant datapoint for this earnings report is management’s prior commentary that non GAAP operating margin had already reached 22.6% in Q2 2026, supported by multi year cost and efficiency programs. This quarter’s EPS outperformance is based on that margin work rather than on aggressive revenue assumptions.
For investors, the link to potential catalysts is direct. Merit Medical Systems is targeting approximately 950 basis points of total margin expansion versus 2019, supported by growth in Foundational and Therapeutic platforms and OEM recovery, while tariffs, reimbursement timing and China pricing pressure remain central operational risks to monitor relative to that objective.
Merit Medical Systems' current analyst blueprint points to about US$1.9b in revenue and US$226.5 million in earnings by 2029. That framework is based on 6.3% yearly revenue growth and an earnings increase of roughly US$80.9 million from the US$145.6 million reported today.
Uncover why Merit Medical Systems' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Merit Medical Systems, the alternate, more optimistic story focuses on oncology and endoscopy acting as bigger growth engines than consensus assumes. Before this Q2 surprise, the most bullish analysts were already modeling revenue of about US$1.9b and earnings of roughly US$238.9 million by 2029. That is a meaningfully brighter script than the baseline. You can treat this quarter’s beat as a prompt to compare those competing views and decide which assumptions feel closer to your own.
Explore 2 other Merit Medical Systems fair value estimates, including one that indicates as much as 15% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Merit Medical Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Merit Medical Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Merit Medical Systems' overall financial health at a glance.
Looking for more investment ideas beyond Merit Medical Systems?
Once you have a view on Merit Medical Systems, it can help to widen the lens and compare it with other companies that match your risk tolerance, income needs, and balance sheet preferences using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, review a curated set of opportunities through our 21 high quality undiscovered gems.
- For readers who focus on resilience first and upside second, narrow your watchlist to companies with steadier profiles using the 30 resilient stocks with low risk scores.
- Income focused investors who care about cash payouts as much as share price can scan a collection of established payers through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com