


EN
Is Super Micro Computer (SMCI) Trading At A Discount After Raised Guidance?
Super Micro Computer has delivered a very large 5 year gain of about 8.5x, yet the recent swings in the share price leave a simple question for you as an investor: Is today’s valuation still grounded in the company’s earnings, or has the story moved ahead of the profit it is currently generating?
- Over the past 5 years, Super Micro Computer has returned 846.8%, which puts a lot of weight on whether its earnings can support such a step up in expectations.
- Fresh news on stronger revenue and margin expectations, alongside heavy investment needs and governance questions, can reshape how reliably those earnings translate into future cash generation.
- Your read on Super Micro Computer is one view; the desks covering it have another. See what analysts think Super Micro Computer's shares could be worth.
The issue now is whether Super Micro Computer’s current share price looks aligned with its earnings when you benchmark it against the Fair Ratio.
If you want a second reference point alongside Super Micro Computer, consider using a focused stock screen built around 55 AI infrastructure stocks.
Is Super Micro Computer Still Cheap on Earnings?
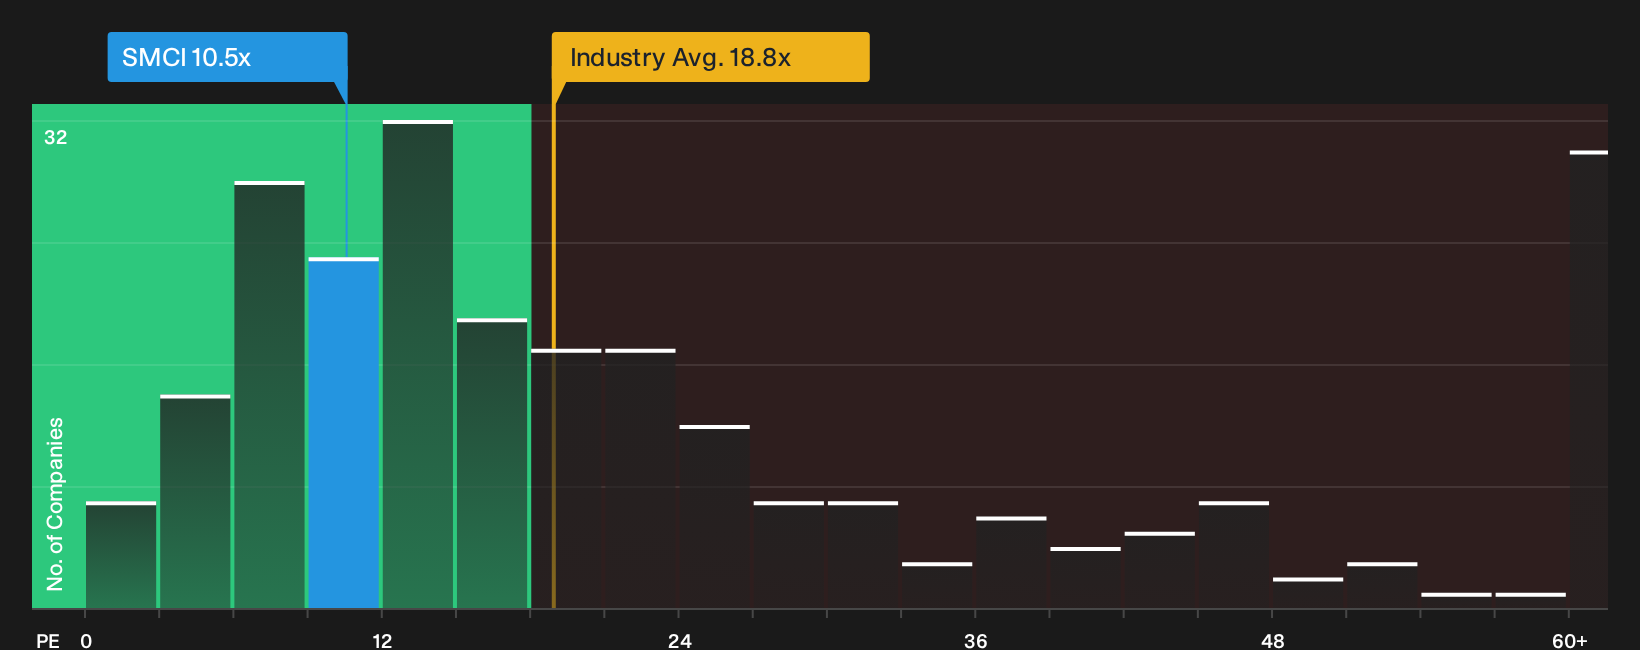
The P/E ratio fits Super Micro Computer because earnings are the key way investors are framing its AI infrastructure story. On this metric, the stock trades at about 10.5x earnings, which is far below the wider Tech sector average of roughly 18.8x and the peer group on about 64.1x. That gap shows the market is pricing Super Micro Computer at a sizeable discount to both its sector and closer AI hardware comparables, even after a very strong share price run.
The Fair Ratio, which reflects what you might expect for this business given its growth profile, margins, size and risks, sits well above the current P/E, so the shares screen as undervalued on this framework. Because fiscal 2027 guidance for sharply higher revenue and better margins has already reset expectations, yet the multiple still trails peer levels, the market seems to be baking in ongoing concerns over cash conversion, export controls and governance. For anyone weighing whether that caution is excessive or justified, the detailed Fair Ratio comparison gives a clearer sense of how much of a discount the current P/E implies. Explore the numbers behind Super Micro Computer's P/E valuation.
The Super Micro Computer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Super Micro Computer pick up where the valuation question above leaves off and explain what growth, margin and earnings paths would need to occur for the stock to be worth materially more or less than today’s price. Instead of a single figure from a ratio or model, Narratives outline the future that number is based on so you can monitor whether Super Micro Computer’s actual progress continues to match that story over time.
Community views on Super Micro Computer are split between those who see an earnings backed AI build out and those who focus on margin strain and legal risk.
Bull case: 19% undervalued
"Expansion into higher margin enterprise, software and services offerings, including management tools bundled into AI factory solutions, together with scaled manufacturing capacity for more than 6,000 racks per month, is designed to shift Super Micro Computer's mix toward recurring and higher value content..."
Discover why this Narrative puts Super Micro Computer at 19% undervalued.
Bear case: 43% overvalued
"One customer represented roughly 63% of Q2 FY2026 revenue."
Explore why this Narrative puts Super Micro Computer at 43% overvalued.
Before acting on Super Micro Computer's valuation, there is one more piece of the puzzle
The next question is how professional forecasters currently map out Super Micro Computer's revenue, profit and margin path over the next few years, and how that picture compares with what the current P/E already reflects. Explore where analysts expect Super Micro Computer to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com