


EN
Hilton (HLT) Stock Slips Despite Strong Q3 Earnings Engine
Hilton Worldwide Holdings came into this Q3 2026 earnings release priced for perfection, trading on a rich 45.6x P/E and following a strong 30 day run. The stock then slipped about 2% on the day, which might suggest a stumble at first glance.
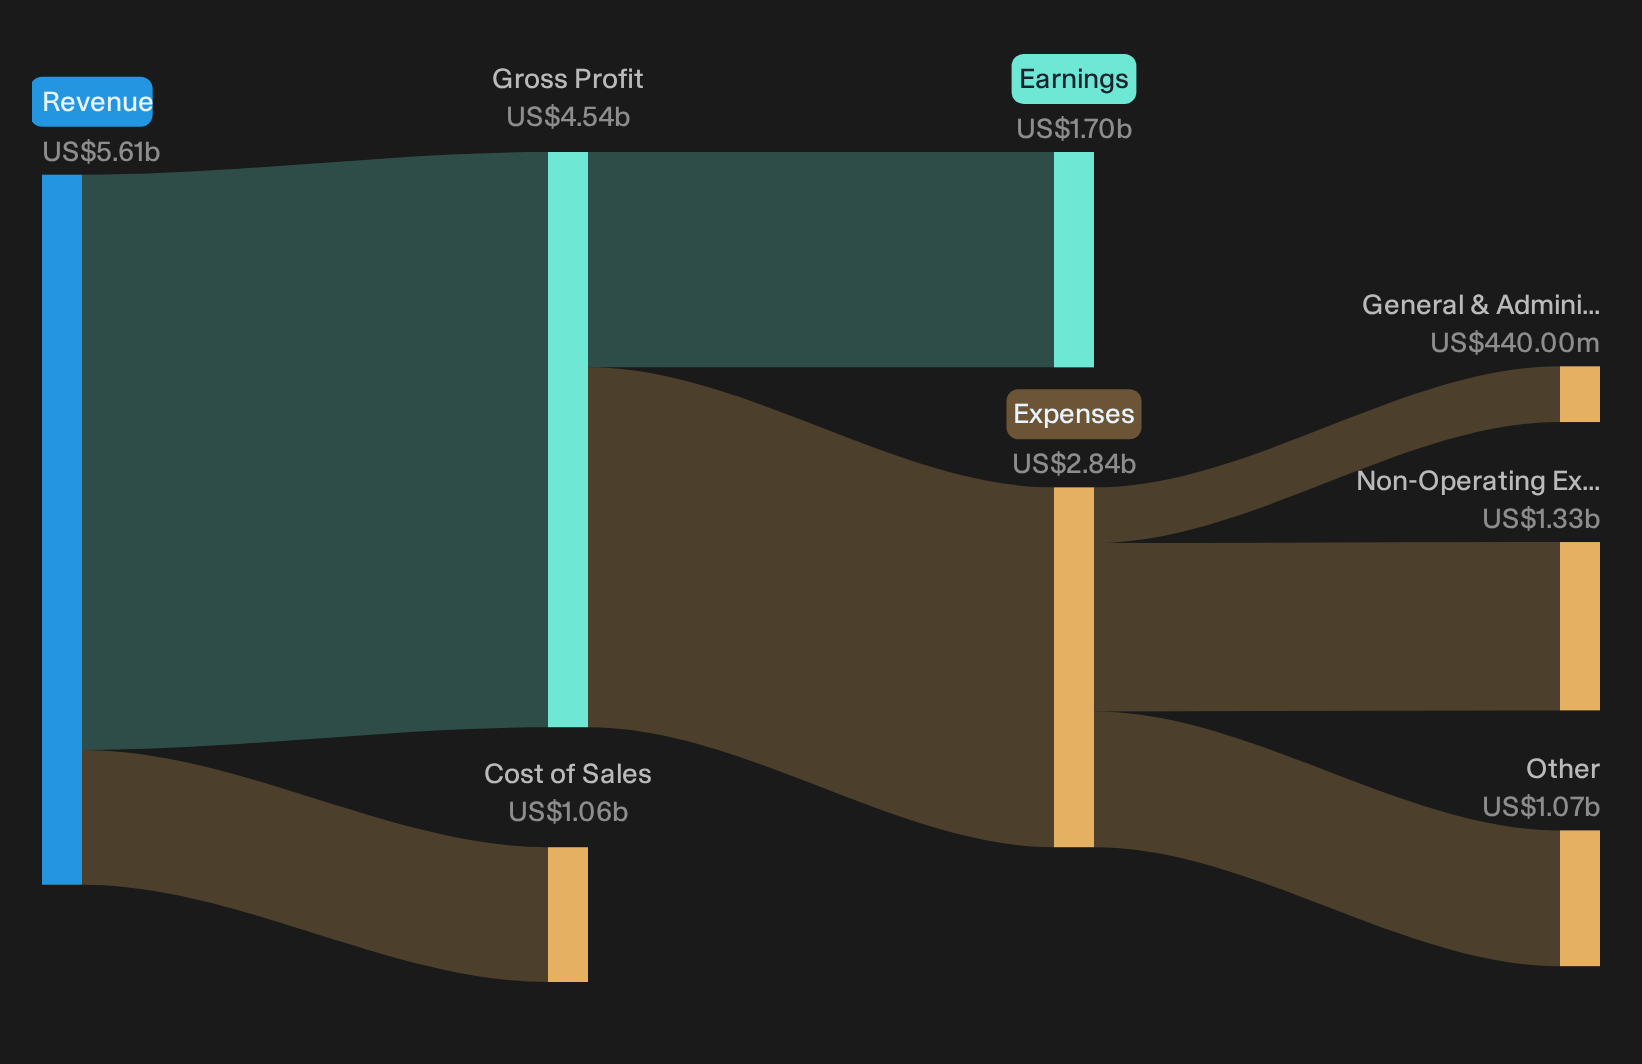
The actual report told a different story. Revenue reached US$3.3b for the quarter and adjusted EBITDA was US$1.06b, with diluted adjusted EPS of US$2.45. For a hotel operator built on fee based, asset light economics, that profit engine is the headline, not the share price wobble.
Love Hilton Worldwide Holdings' asset light fee model but uneasy with a 45.6x P/E that already bakes in a lot of perfection? Check out our screener of high quality businesses with sturdier balance sheets and robust fundamentals in the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$3,325m vs. US$1,283m (very large increase, more than 2.5x year on year)
- Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): US$536m vs. US$420m (up about 27.6%)
- Basic EPS (Q3 2026 vs Q3 2025): US$2.39 vs. US$1.79 (higher by roughly 33.5%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 30.3% vs. 34.2% (margin contracted by about 3.9 percentage points)
Hilton wants to sustain 6%–7% net unit growth for years. Ask Charlie what makes Hilton’s 6%–7% growth target believable.
Hilton’s Growth Engine: Pipeline And Owner Programs On Trial
Hilton Worldwide gets a bullish narrative built on a record pipeline and hotel owner support. The claim is clear around what must work.
"The main thing that has to go right is that Hilton converts its record 541,000 room pipeline, including a high share of lifestyle, extended stay, and collegiate brands, into profitable openings while owner-focused fee reductions and programs like RISE maintain or improve hotel-level margins."
Q3 brought roughly 180 hotel openings and more than 27,000 rooms, with conversions at 37% of additions. Management held to a 6% to 7% multi year net unit growth target and called out RISE and fee reductions as helping owner sentiment, which supports this growth and margin story for now.
Hilton Bear Case: Regional Weakness And Renovation Drag Tested
Bears focus on regional softness and refurbishment risk undercutting Hilton Worldwide’s fee engine.
"Ongoing weakness and modest declines in RevPAR in sensitive regions such as the Middle East and China, where one region saw RevPAR fall about 30% in a recent quarter and full year expectations point to high single to low double digit declines while China is expected to be down low single digits, could offset stronger markets and slow system wide fee growth and revenue."
Q3 showed system wide RevPAR up 5.8% and U.S. RevPAR higher by 7%, yet MENA and China RevPAR both fell mid single digits. Management also flagged US$60m to US$70m of drag from renovations and weaker license fees. The quarter supports that regional and renovation headwinds are real but currently outweighed by broader strength.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
Hilton Worldwide Holdings just showed how a strong fee engine and a small price slip can coexist. The real opportunity is spotting companies that could be undervalued before that mismatch closes.
- Company 1 - 42% below our estimate - expand a solar hardware and software platform into storage and inverter offerings as project pipelines strain suppliers.
- Company 2 - 27% below our estimate - integrate a major test-equipment acquisition so utilities and aerospace customers can upgrade grids and fleets with a single diagnostics partner.
- Company 3 - 15% below our estimate - ride a surge in hyperscale data center builds by wiring projects that traditional contractors struggle to staff and finance.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com