


EN
How Investors May Respond To Aberdeen Group (LSE:ABDN) Platform Inflows Hold Up
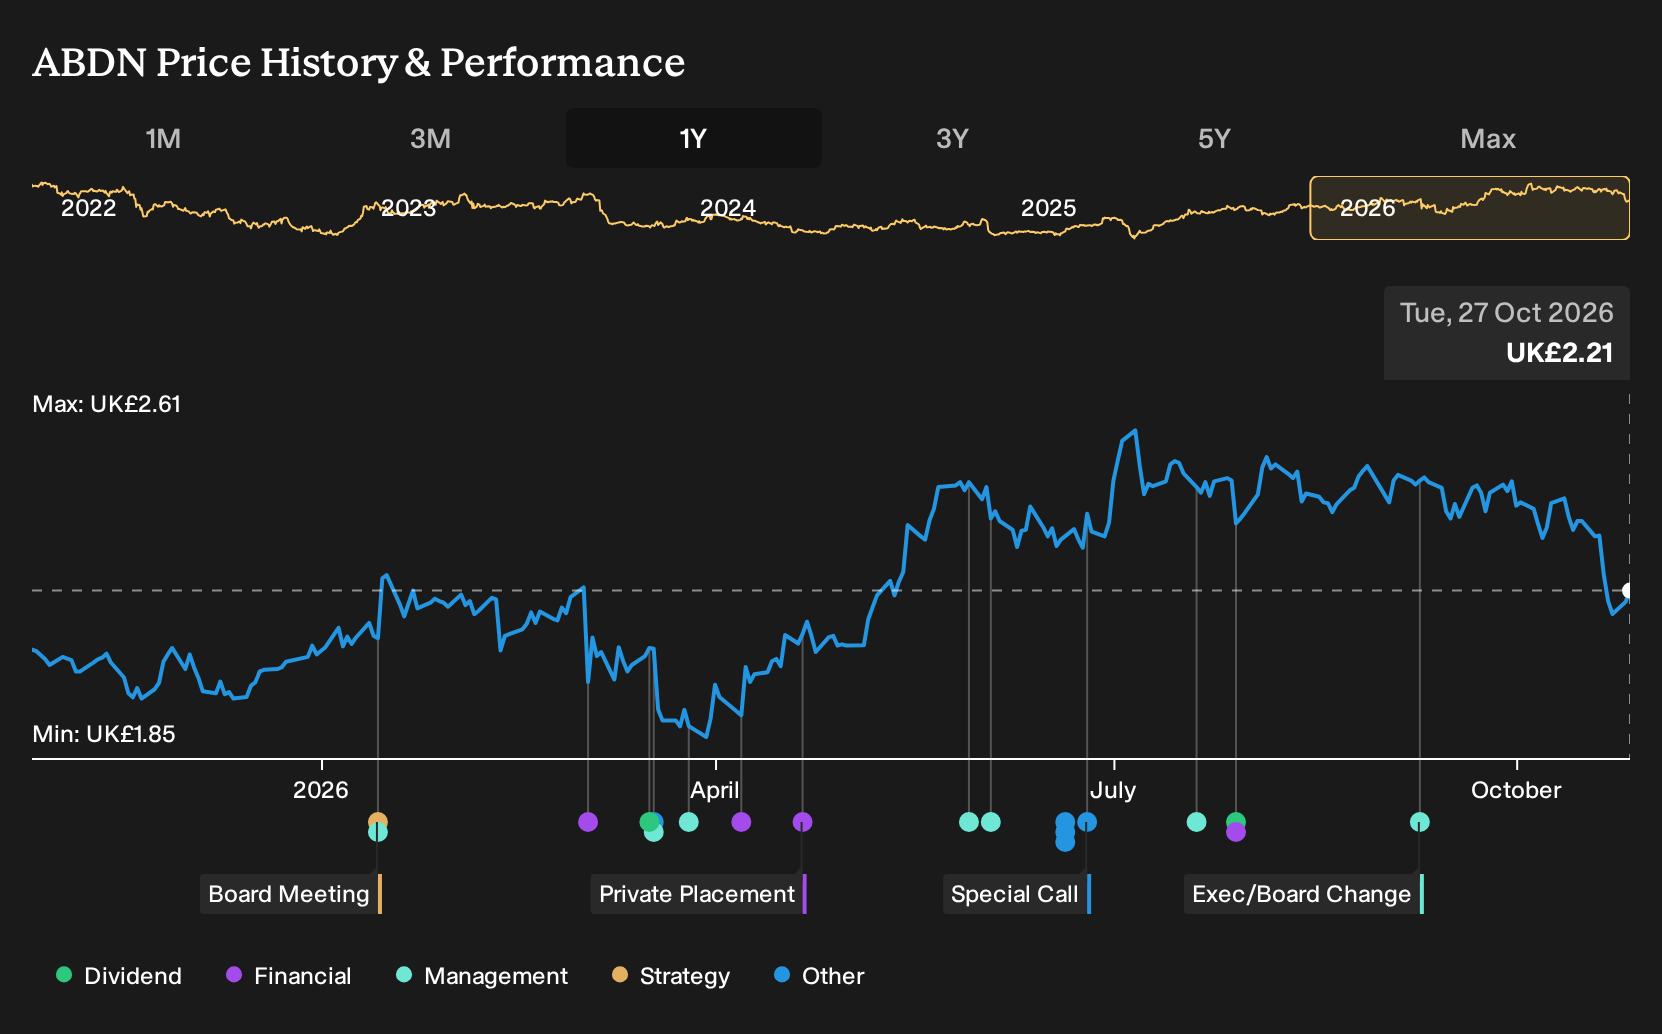
- Aberdeen Group held its Q3 2026 sales and trading statement call on 21 October and has recently reported £579b of assets under management, alongside a planned £210m redemption of Additional Tier 1 debt.
- Higher inflows at the Interactive Investor platform and the decision to redeem hybrid capital highlight how fee based activity and balance sheet actions are working together inside Aberdeen Group.
- We will now look at how Aberdeen Group's investment narrative is affected by the reported £579b of assets under management.
Scan other asset managers showing similar fee based momentum and capital discipline with our hand picked 10 high quality undervalued stocks to see how Aberdeen Group compares on quality and valuation support.
Aberdeen Group Investment Narrative Recap
To own Aberdeen Group, you need to be comfortable with a simple idea. The healthier, fee rich parts of the business, especially Interactive Investor and specialist investment strategies, need to keep doing enough heavy lifting to offset pressure in Adviser and equity funds. The latest £579b assets under management figure and ongoing platform inflows broadly support that operating story rather than changing it.
The short term swing factor still looks like flow momentum and pricing in Adviser and active equities, where persistent outflows or weaker fee yields could drag on earnings. The biggest risk remains that these headwinds persist longer than expected, so even solid capital generation and cost savings struggle to translate into stronger group profits.
The planned £210m redemption of Additional Tier 1 debt is the announcement that most clearly ties this news together. It sits alongside strong regulatory capital coverage and a multi year effort to simplify Aberdeen Group’s funding. For you as a shareholder, the key operational angle is a potential reduction in interest expense and a cleaner balance sheet if execution stays on track.
This capital move does not fix flow pressure in Adviser or equities, but it may give management a bit more room to keep investing in Interactive Investor, technology and product mix without stretching leverage. If flows stabilise and costs remain under control, the combination of a more efficient balance sheet and higher quality earnings mix could be an important catalyst for how the market assesses Aberdeen Group’s earnings power.
Aberdeen Group's analyst narrative points to forecast revenue of £1.4b and expected earnings of £243.6 million by 2029, with earnings today at £382.0 million. This reflects revenue that is assumed to stay fairly flat and an earnings decline of £138.4 million from current levels.
Discover how Aberdeen Group's fair value reflects a 10% potential upside to its current price before the gap closes.
Exploring Other Perspectives
You might look at Aberdeen Group’s £579b of assets under management and AT1 redemption and see momentum, yet the most pessimistic analysts still focus on pressure in Adviser. They were pencilling in 2029 earnings of about £192.7 million on revenue near £1.3b before this update, so their story could shift if today’s trends persist.
Explore 4 other Aberdeen Group fair value estimates, including one that suggests as much as 48% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Aberdeen Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aberdeen Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aberdeen Group's overall financial health at a glance.
Looking for more investment ideas beyond Aberdeen Group?
Once you have a view on Aberdeen Group, it can help to line it up against other opportunities that share similar qualities or appeal to a different risk profile altogether.
- If you want potential growth with tighter risk controls, scan a curated 4 resilient stocks with low risk scores that may better fit a steady, capital preservation mindset.
- For investors who care about resilient finances and clean balance sheets, compare Aberdeen Group with a list of solid balance sheet and fundamentals (10 results) that already meets strict quality filters.
- If you enjoy getting in early on under-followed opportunities, broaden your watchlist with a 5 high quality undiscovered gems that pairs strong fundamentals with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com