


EN
Top 3 Undervalued Stocks To Watch In October 2026
Anthropic’s planned megasized IPO and the wider rush to fund AI infrastructure have thrown massive capital at fast growing stories, while quieter cash machines get less attention. That gap can matter. When money crowds into the headline AI trade, some solid businesses with healthy cash generation can slip to discounted prices. This piece highlights three such stocks where current cash flow potential looks attractive relative to their assessed value.
The three examples below only scratch the surface, as the same cash flow lens currently flags another 461 companies where the gap between discounted price and assessed value is just as compelling.
To see that full universe, head straight into the Undervalued Stocks Based On Cash Flows screener to identify candidates, analyze their cash generation profiles, and focus on the opportunities that best fit your own conviction.
L.D.C (ENXTPA:LOUP)
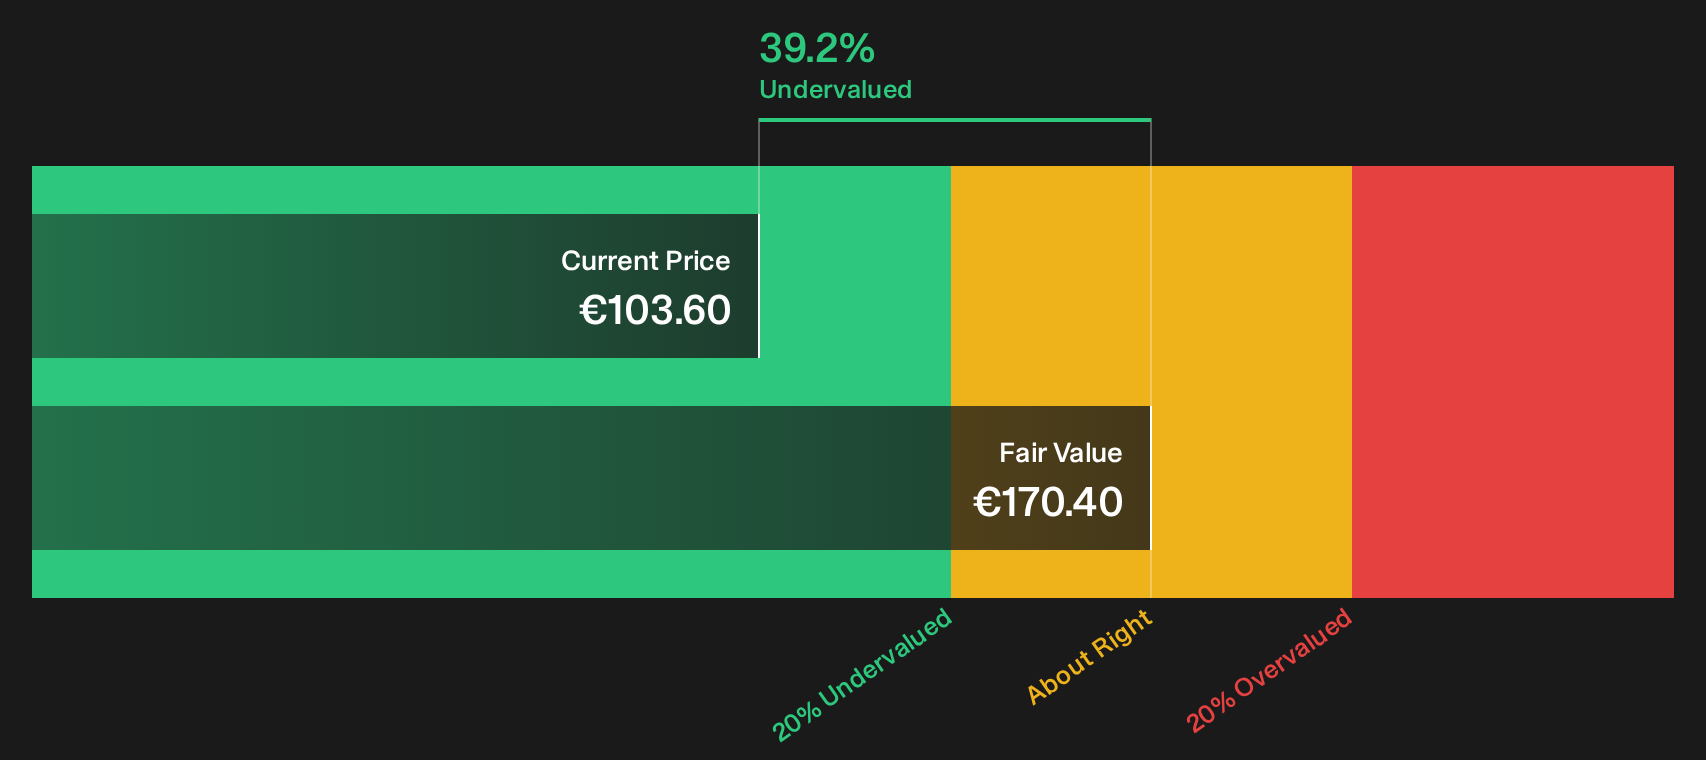
L.D.C is a French poultry and prepared-foods group whose core poultry and ready-meals operations generate the recurring cash flows that link it to the undervalued cash flow screener, with Poultry on €4.8b, Processor on €1.2b, Abroad on €1.4b revenue and a market value near €3.6b.
L.D.C trades on an 11.2x P/E compared with food peers on 17.6x and screens at a 39.2% discount to an SWS DCF fair value estimate. This estimate is grounded in its poultry and ready-meals cash flows rather than blue-sky growth assumptions, though one unseen pressure could yet decide how much of that gap closes.
That unseen pressure makes it even more important to review the 5 key rewards and 1 important warning sign before the valuation gap potentially starts to narrow.
Oracle (ORCL)
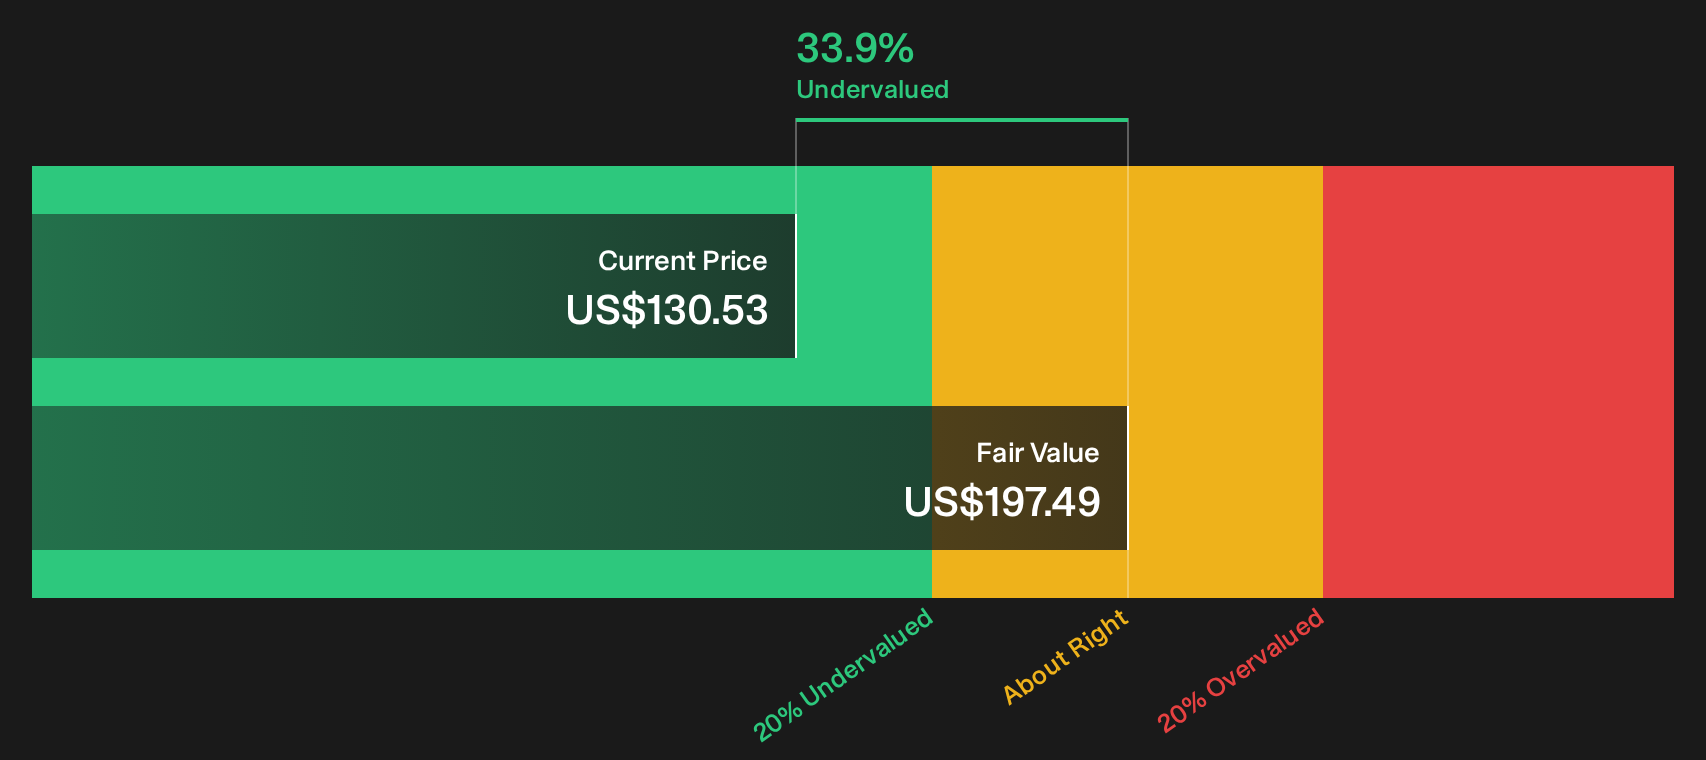
Oracle is best known for its enterprise databases and software, but its Oracle Cloud SaaS and OCI platforms now anchor the recurring, subscription-based cash flows that tie it into this undervalued cash flow screen. The business generated about US$62.8b from cloud and software, US$5.8b from services, and US$3.2b from hardware in its latest period, with a market value around US$382.2b.
For investors focused on cash flow potential, Oracle offers a mix of long-standing software franchises and rapidly scaled cloud subscriptions that feed into discounted cash flow models. That combination makes it a useful case study in how AI infrastructure and recurring contracts can influence perceived mispricing.
"This partnership positioned OCI as a key extension of the Microsoft Azure AI platform."
How far Oracle can translate its huge AI and cloud commitments into durable cash returns may hinge on one unresolved funding constraint.
That funding question is central, and the full narrative for Oracle shows how Oracle’s AI spend, cloud cash flows, and capital needs could be decoupling headline stories from underlying value.
Amazon.com (AMZN)
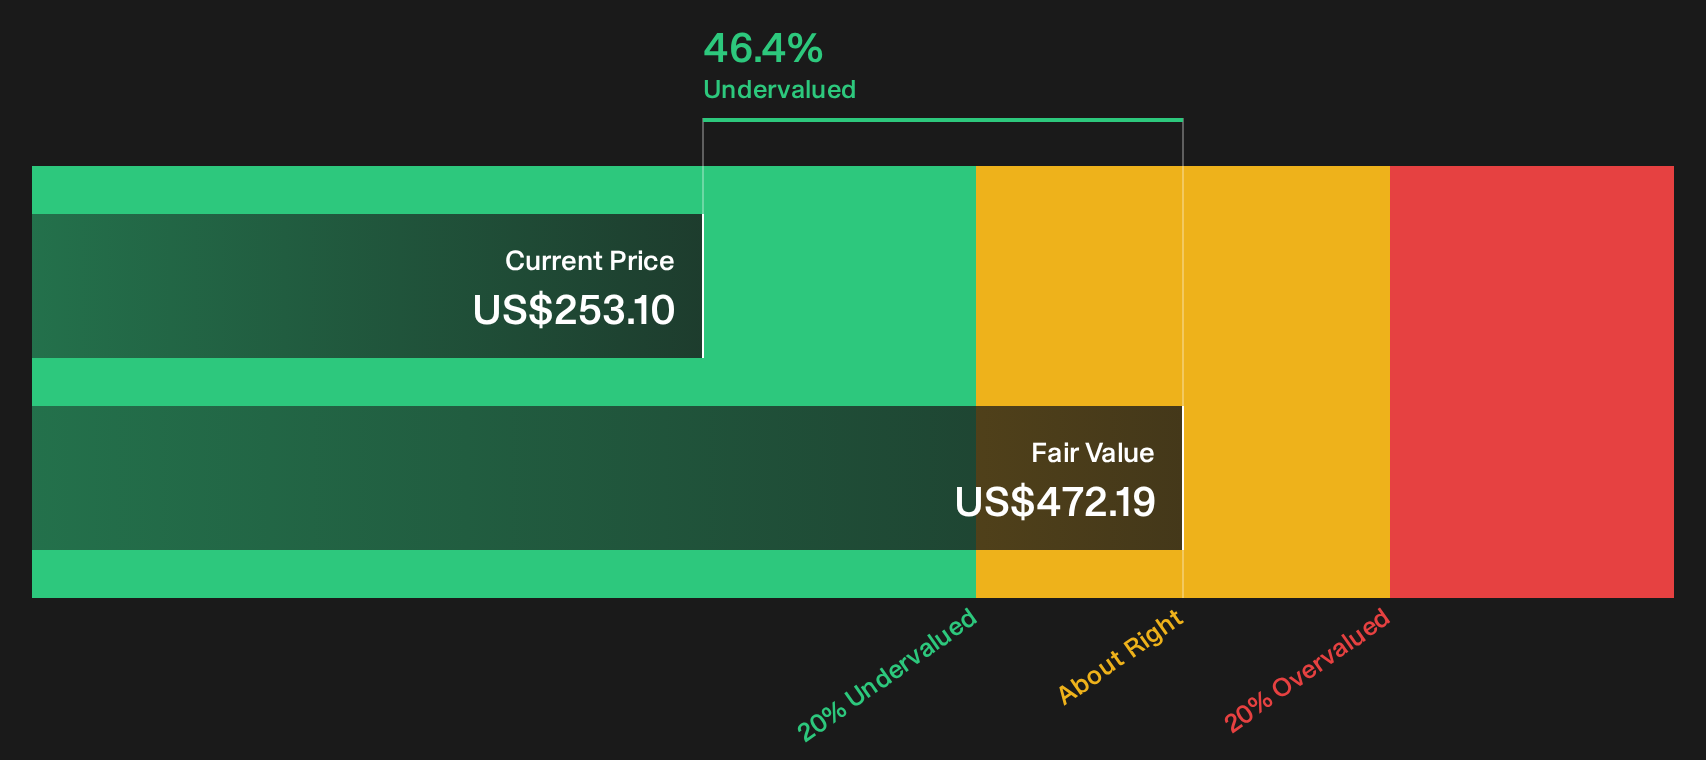
Amazon.com runs a vast online retail and subscription ecosystem, sells devices and media, and operates AWS, whose AI, compute and data services drive the cash-flow story that links it to this screener. North America brought in about US$453.7b, International US$173.6b, and AWS US$148.4b, with a market value near US$2.7t.
For this screen, Amazon.com matters because AWS throws off the kind of scalable, service-based cash flows that can support a discounted cash flow valuation, even while the rest of the group keeps it diversified.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion; this reacceleration is AI-led, not cyclical."
What happens to that valuation gap depends heavily on how one unseen pressure shapes the balance between heavy AI spending and future margins.
If that pressure on spending versus margins interests you, read the full narrative for Amazon.com to see how Amazon.com’s AI cash engine could reshape the long term risk reward picture.
Seeking Alternatives Before Everyone Else?
Fresh ideas move first. Breakout stories can build momentum while they are still under the radar and may only be noticed by many investors once prices have already moved.
- Use the 223 resilient stocks with low risk scores to hunt for resilient cash generators before defensive quality becomes crowded and pricing power changes.
- Use the 224 dividend fortresses to target income streams while yields are elevated and payout strength receives less attention from many investors.
- Use the 42 power grid technology and infrastructure stocks to track potential infrastructure-related opportunities and to research assets that some investors may notice only after the story is more widely covered.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com