


EN
Centene (CNC) Stock Price Drifts As Q3 Results Lift EPS Outlook
Centene just reported Q3 2026 and the market barely flinched. The stock rose about 1% to US$68.71 even as the company posted a small loss on basic earnings per share and modest net income pressure for the quarter. The headline was somewhere else entirely. Management lifted full year adjusted EPS guidance to more than US$5.20, leaning hard into a margin story that now runs straight through Medicare and the health benefit ratio.
That gap between a muted one day price move and a guidance upgrade puts sentiment on trial. Traders reacted as if this was a routine print. The fundamentals, especially around profitability targets, tell a much sharper story that the market now has to decide whether to trust.
Love Centene’s higher EPS guidance but uneasy about a quarter that still shows a basic EPS loss? Screen for companies that pair resilient earnings with cleaner profitability profiles in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$50,647 million vs. US$45,348 million (higher top line year on year)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$71 million vs. loss of US$6,631 million (materially smaller loss year on year)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.14 per share vs. loss of US$13.50 per share (loss per share narrowed sharply)
- Consolidated Health Benefit Ratio, HBR, (Q3 2026 vs. Q3 2025): 92.7% vs. prior year HBR not specified (Q3 ratio tracked better than management’s expectations)
Prefer clean charts instead of another wall of earnings tables and footnotes? See Centene’s full financial picture, including a visual view of its valuation setup, in the company report for Centene.
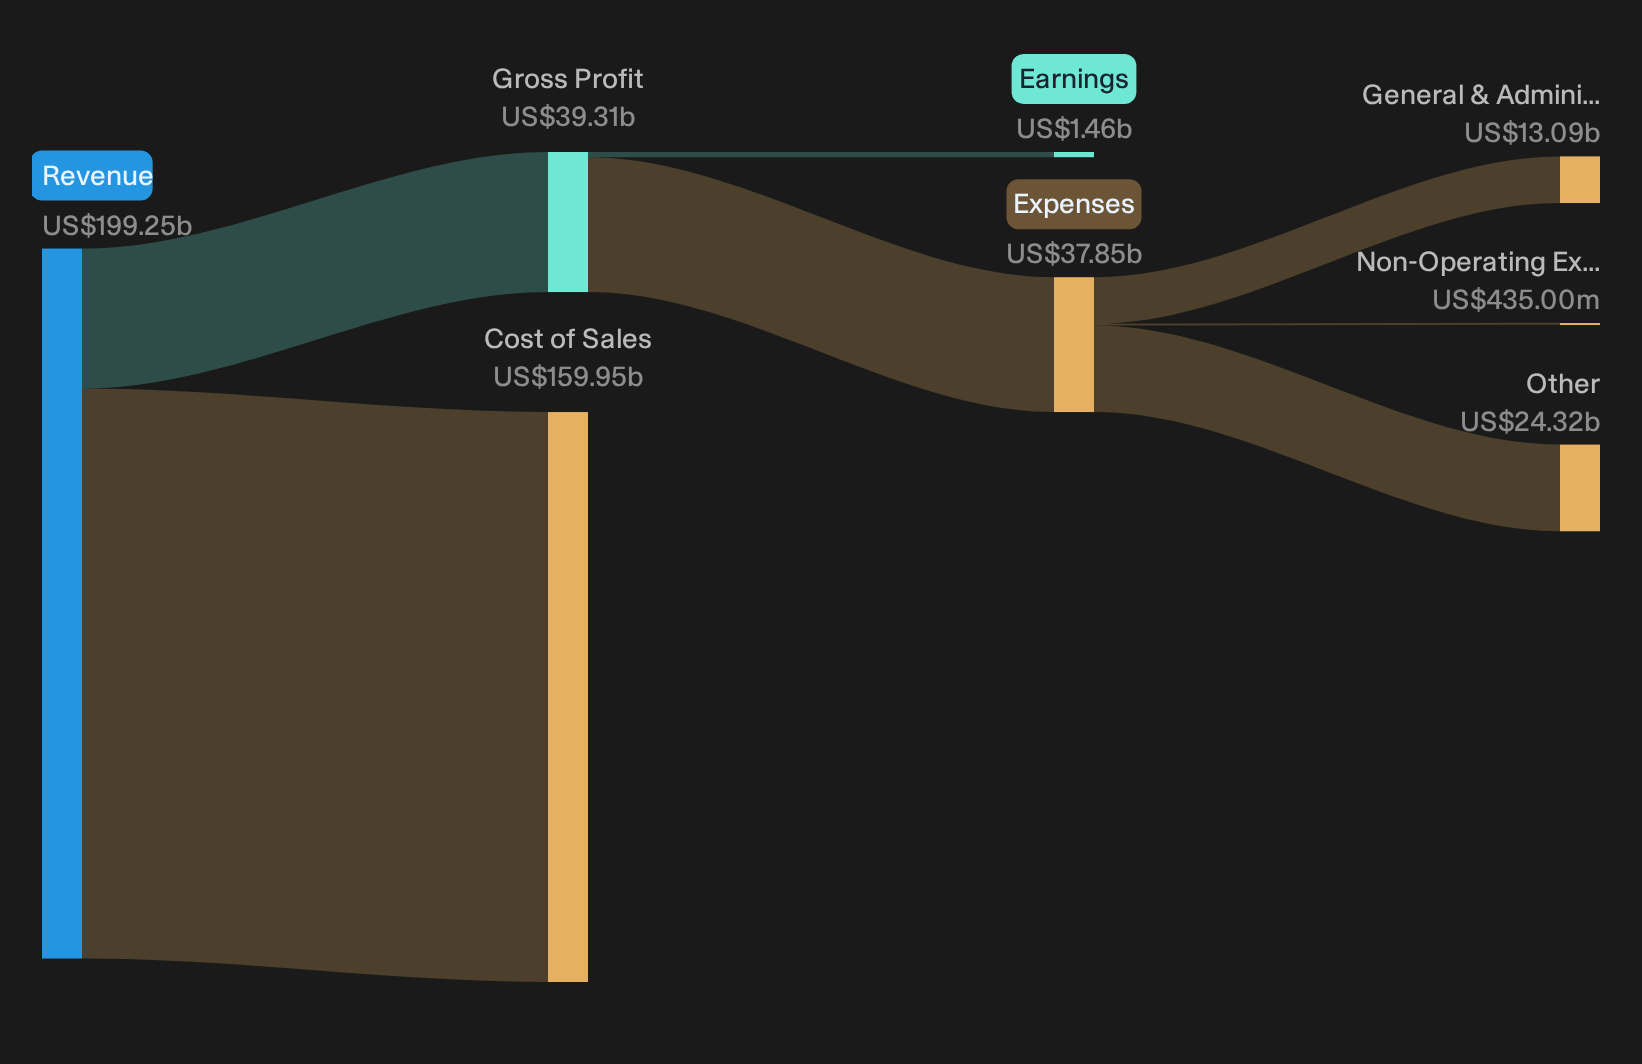
Centene’s Margin Thesis Clears Key Q3 Hurdles
The bullish story says Centene can use product mix and cost discipline to keep restoring earnings power even while Medicaid enrollment falls.
"The main thing that has to go right is that Medicaid rate setting, Marketplace risk adjustment, and Medicare duals and Part D margins continue to offset enrollment pressure and regulatory changes so that margin restoration stays on track."
Q3 results give that claim real proof points. Consolidated HBR of 92.7% and a Medicaid HBR of 93.6% tracked with margin targets despite membership falling. Marketplace is pacing near a 5% pretax margin, at the top of its range. Medicare Advantage moved to expected breakeven in 2026 and Part D pretax margin is now guided to the mid to high 3% range. Together with higher full year adjusted EPS guidance above US$5.20 and lower interest expense from debt reduction, those operational and financial markers show the margin mix thesis hitting key milestones, rather than relying only on future promises.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Centene Bear Case: Membership Shock, Margin Repair
Bearish investors worry Centene’s OB3 driven Medicaid disruption delays real earnings quality, even as guidance climbs.
"While Centene highlights long term opportunities from states moving more fee for service Medicaid lives into managed care, the near term impact of tighter eligibility rules and OB3 preparation is a sharper than previously expected drop in Medicaid membership. Management already links this to muted margin recovery in 2H26 and into 2027, which could cap any uplift in consolidated net margins from this book."
Q3 confirms the enrollment hit, with Medicaid membership down 5% year to date and management flagging an 8% to 9% full year drop. Medicaid HBR at 93.6% sits near target, so profitability is holding for now. However, the step down in lives means the feared volume shock has arrived while the margin repair remains only in line, not ahead, of plan.
Hunt Mispriced Earnings Stories
Centene shows how earnings narratives and share prices can move out of sync. The real opportunity is evaluating stocks that could be undervalued before the market reassesses them.
- Company 1 - 34% below our estimate - expand an advisory platform focused on capital markets and private capital mandates.
- Company 2 - 31% below our estimate - pursue data centre demand built on a proprietary GPU and software stack.
- Company 3 - 15% below our estimate - ride a swelling backlog from hyperscale data centre builds into long dated contracts.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com