


EN
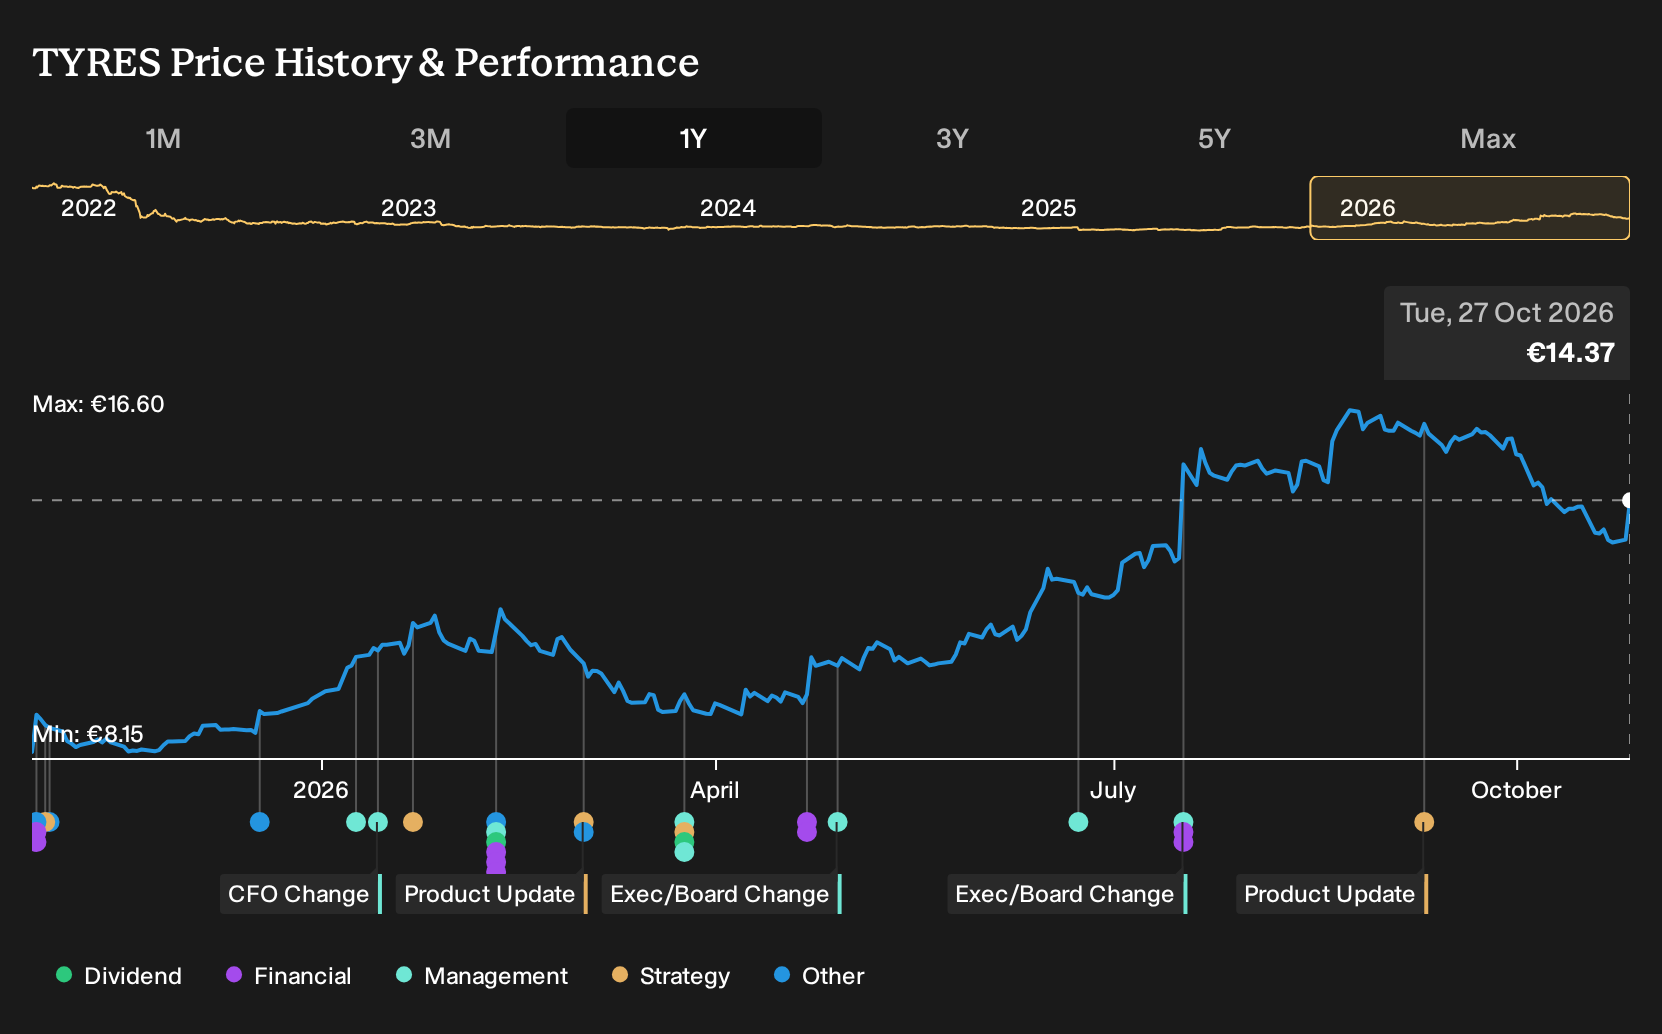
Nokian Tyres Stock What Changed After Its Return To Profit
- Nokian Renkaat Oyj has reported past third quarter 2026 sales of €359.1 million and net income of €23 million, with earnings per share from continuing operations at €0.17, and nine month 2026 sales of €1,018.7 million and net income of €20.4 million.
- The business shifted from a nine month loss in the prior year to a profit in 2026, which highlights how higher sales and improved earnings per share from continuing operations are contributing to the reported turnaround.
- Attention now turns to how this stronger profitability at Nokian Renkaat Oyj could influence the investment narrative that analysts built earlier.
Scan how Nokian Renkaat Oyj's earnings shift compares with other balance-sheet focused opportunities by reviewing our hand picked list of solid balance sheet and fundamentals (207 results).
Nokian Renkaat Oyj Investment Narrative Recap
To own Nokian Renkaat Oyj, you need to believe the tire maker can turn early profitability into something more durable through mix upgrades, cost control and growth in Central Europe and North America. The latest quarter supports that story, with higher net income and positive earnings per share from continuing operations giving the turnaround more credibility.
The short term swing factor is still execution on margins while demand in key markets remains mixed. Interest coverage remains a watchpoint and any setback in price or mix in premium winter and all season products could pressure that progress. The latest figures help sentiment but do not remove these operational risks.
The third quarter 2026 earnings release is the key update here. Sales reached €359.1 million and net income came in at €23 million, with basic earnings per share from continuing operations at €0.17. Over nine months, sales were €1,018.7 million and the business moved from a loss a year ago to a profit of €20.4 million.
This shift back to profit matters for the core catalyst, which is whether Nokian Renkaat Oyj can grow into its long term margin ambitions while funding expansion and servicing debt comfortably. Stronger earnings give management more room to keep investing in higher value tires and distribution. They also slightly ease, but do not eliminate, the concern that interest payments are not yet well covered by earnings.
Nokian Renkaat Oyj's current narrative implies revenue reaching €1.8b and earnings of €150.8 million by 2029, based on analysts' expectations of 7.5% yearly revenue growth and an earnings increase of about €131 million from €19.5 million today.
Uncover why Nokian Renkaat Oyj's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternative story around Nokian Renkaat Oyj focuses on faster margin expansion. The most optimistic analysts were already pencilling in earnings of about €211.0 million and 11.1% profit margins by 2029, compared with consensus closer to €150.8 million. The latest earnings surprise may push some of those projections higher or bring others closer, so it helps to compare several viewpoints before deciding what looks reasonable to you.
Explore 2 other Nokian Renkaat Oyj fair value estimates, including one that suggests as much as 19% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nokian Renkaat Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nokian Renkaat Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nokian Renkaat Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nokian Renkaat Oyj?
If the latest numbers from Nokian Renkaat Oyj have sharpened your appetite for research, use that momentum to compare it with other opportunities that fit different risk and return profiles across the market.
- For investors who want quality on sale, scan a focused set of value opportunities through the 195 high quality undervalued stocks and see which businesses currently trade below their assessed worth.
- If income is your priority, line up reliable cash generators by filtering for higher yielding payouts with the 224 dividend fortresses and check which payouts look better supported by fundamentals.
- For those who care most about resilience, stress test your watchlist against balance sheet strength by starting with the 223 resilient stocks with low risk scores and comparing how each candidate scores on financial durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com