


EN
What PTT Holders Got Right
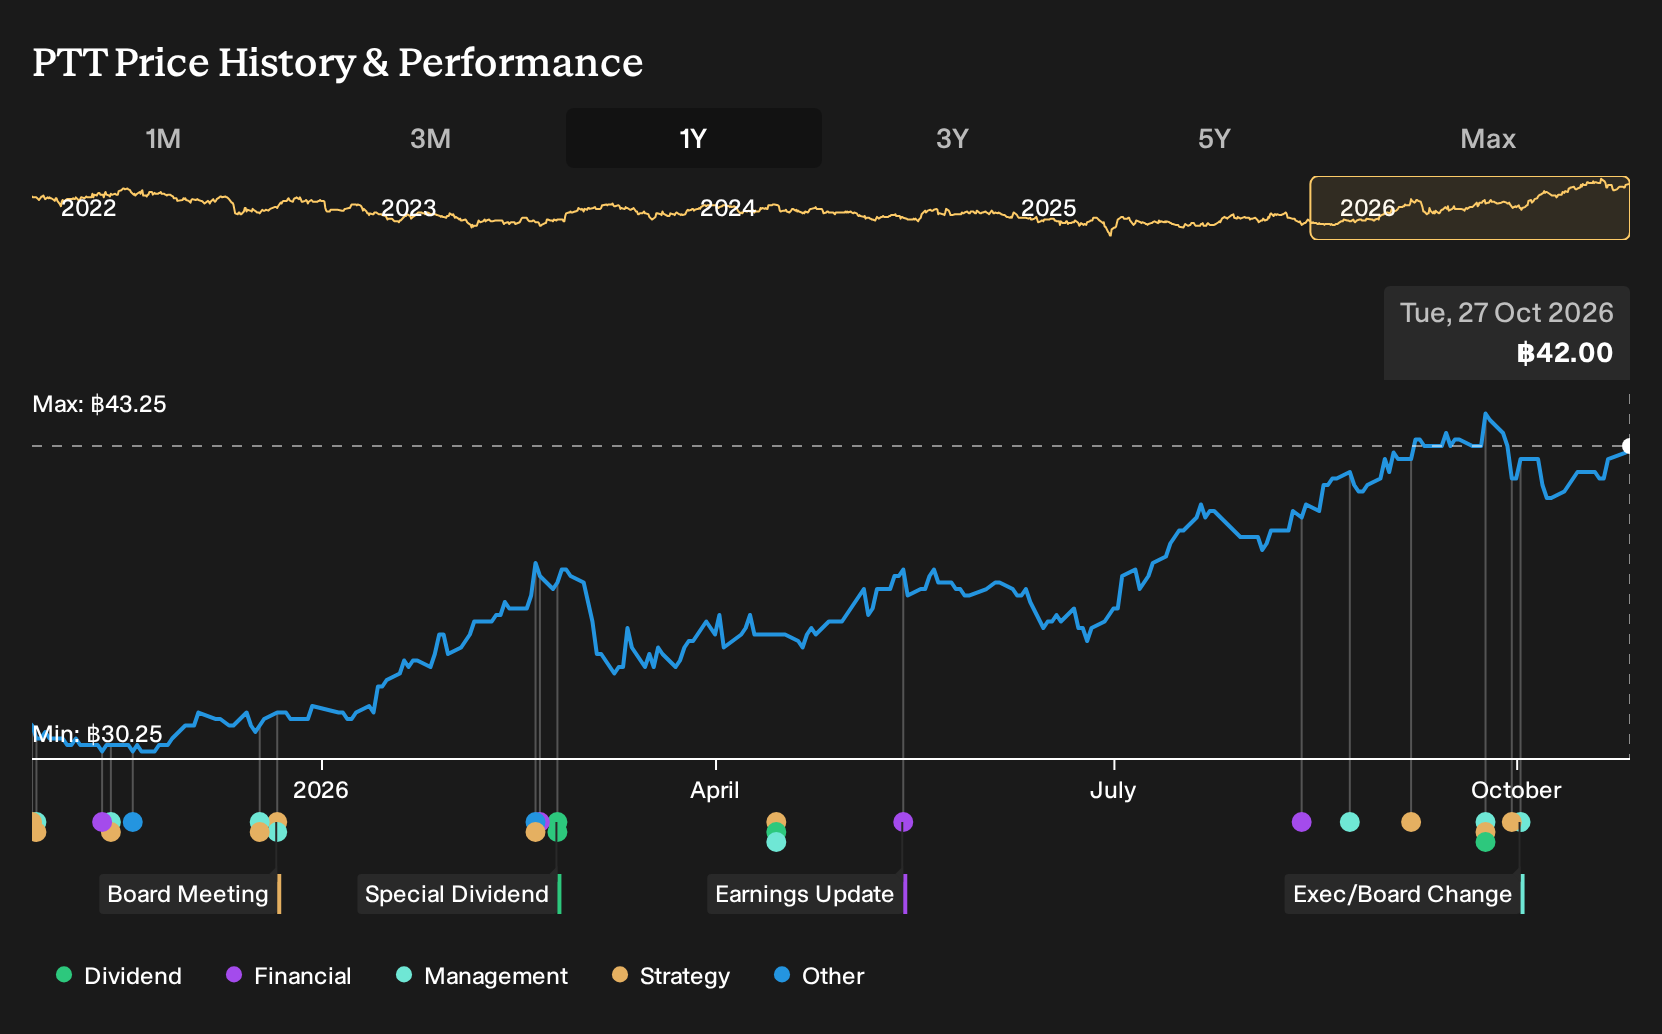
If PTT sat on your watchlist instead of in your account, the move over the past year may feel like a missed call. Investors who held PTT over the past year are up 47.2%, including dividends. That outcome arrived alongside a period where analysts were debating whether LNG expansion, renewables spending and AI-driven efficiency could really support firmer margins. So which assumption about PTT’s future profitability would have helped you spot that risk and reward balance in advance?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
PTT has already moved. See which of 195 high quality undervalued stocks still trade below our estimates.
The Two Stories PTT Investors Had To Weigh
The shares cost THB31.25 at the start of the period, so anyone looking at PTT had to decide which future felt more reasonable.
On the optimistic side, the bull narrative put fair value at THB34.27, about 10% above the start price, and leaned on LNG expansion plus renewable projects to support revenue growth of 0.5% and a future P/E assumption of 12.2x.
The bear view set fair value at THB26 and focused on ESG pressures and oil overcapacity, with an assumption that revenue would decline 2.4% a year even as profit margins were expected to reach 3.1%.
What The PTT Results Actually Tested
The clearest new fact for PTT holders landed with Q2 2026, when total revenue reached THB830,389.289135m and net income came in at THB52,524.591887m. Net margin moved from 3.2% in Q2 2025 to 6.3% in Q2 2026, which leaned toward the optimistic thesis on profitability, although only one period of stronger earnings is visible.
The lesson to carry across is simple. When a story rests on future margin strength, track net margin quarter by quarter and see whether it actually moves toward the assumption on the page.
What PTT’s Recent Run Already Prices In
PTT now trades at THB42 after a 47.2% gain over the past year, while this Narrative’s Fair Value sits below the current price. The Narrative frames the concern less around survival and more around how dependable future earnings really are.
To buy PTT here, an investor would need to judge that LNG, CCS and digital efficiency projects can support durable profits rather than one off gains.
"The current valuation implies the share price already reflects resilient profits around recent levels and meaningful payoff from LNG growth, decarbonization projects and digital profit enhancement, which suggests there may be limited room for disappointment if these plans underdeliver."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
PTT And A Different Kind Of Fuel
Watching PTT, you are already thinking about long lived energy assets. The next question is where dependable output really comes from.
PTT relies on large upstream fields and complex processing. Another producer is also working to keep its equipment running reliably and steadily.
That business is stripping out structural costs and trimming weaker projects. Its aim is a leaner operation that can still support big reservoirs.
Both are wrestling with fossil demand, climate rules and portfolio cleanups. Your decision is whether that second path offers a different balance of resilience and risk.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com