


EN
Agilysys (AGYS) Stock Drops As Q2 Earnings Meet Valuation Reality
Agilysys just reminded investors that the stock chart and the income statement do not always tell the same story. The share price fell 6.2% to US$115.81 after the fiscal Q2 2027 earnings release, even as the hospitality software specialist posted record quarterly revenue of US$93.36m and what management described as record adjusted EBITDA margins. Short term traders focused on the drop. Longer term holders are more likely to focus on rising recurring and subscription income and an elevated P/E of 73.5x that already prices in a meaningful multi year earnings path.
Love Agilysys’ record recurring revenue and richer margins but uneasy about paying a 73.5x P/E for that profile? Compare it with a curated group of premium quality software and service businesses in our 29 high quality undervalued stocks
Q2 2027 Earnings Summary
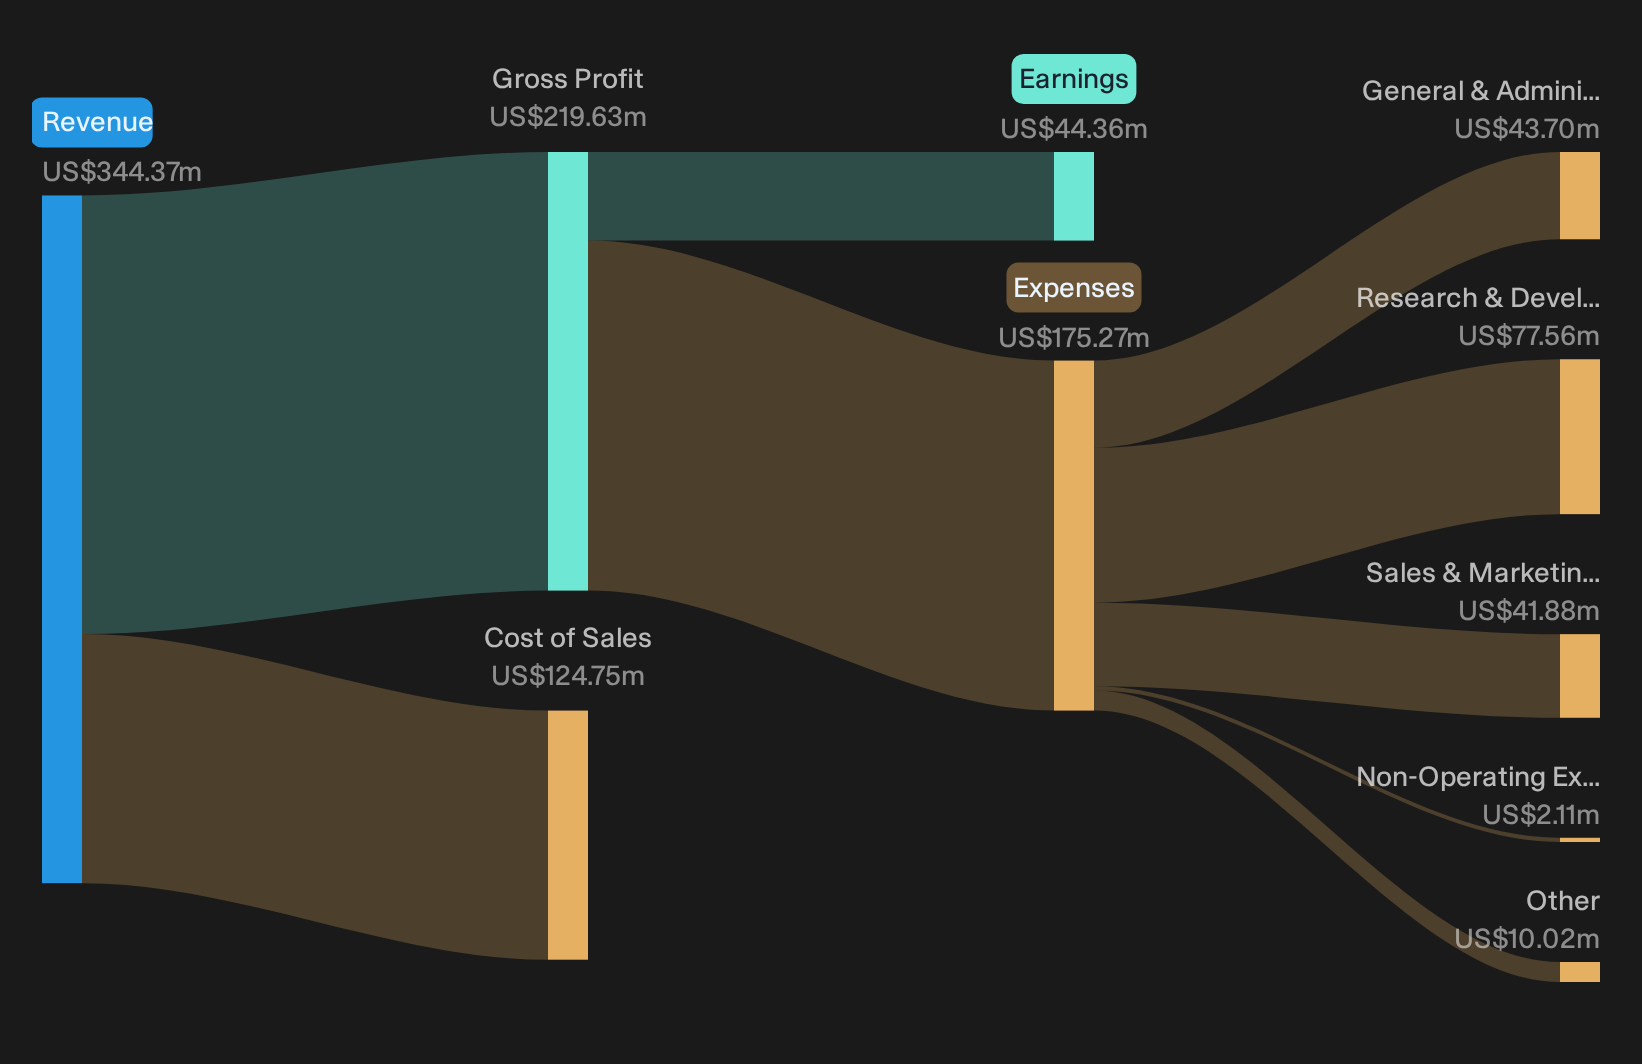
- Revenue (Q2 2027 vs. Q2 2026): US$93.36m vs. US$79.30m (higher year over year)
- Net Income, excluding extra items (Q2 2027 vs. Q2 2026): US$13.18m vs. US$11.71m (higher year over year)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.47 vs. US$0.42 (higher year over year)
- Adjusted EBITDA Margin (Q2 2027): 25.9% of revenue compared with management’s description of a record level in the current quarter
Agilysys just raised subscription growth guidance again after a record quarter. Ask Charlie what’s behind Agilysys’ record subscription growth guidance.
Agilysys Bull Case: Efficiency And AI Milestones Land
The bullish story rests on Agilysys turning multi module wins plus AI and leaner delivery into structurally higher profitability rather than just bigger deals.
"In addition, the company would need to use AI and improved implementation efficiency to support higher margins without major headcount expansion."
Q2 results move that hypothesis from theory into evidence. Record subscription revenue at 71% of recurring revenue, services gross margin above 30% for a third straight quarter and adjusted EBITDA at 25.9% with raised full year margin guidance all point to better revenue per services dollar. Management reiterates that existing sales, services and R&D capacity can support larger contracts, which directly supports the efficiency claim.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Agilysys Bear Case: Cost Gravity Not Gone Yet
Bears argue Agilysys will have to keep spending heavily just to stay competitive, which would blunt operating leverage even as subscriptions climb.
"If Agilysys must reinvest heavily in infrastructure and R&D to keep pace, the additional spend could offset efficiency gains and reduce the uplift to net margins that many investors expect."
Q2 margins look healthy, with gross margin at 64.6% and adjusted EBITDA at 25.9%, and full year guidance nudged higher. That said, management also discussed accelerating AI work and expansion into foodservice management and APAC, both of which require ongoing deployment and support spend. As a result, the long term cost ceiling is not settled yet.
Hunt For Mispriced Compounding Stories
Agilysys just showed how a strong report and a jumpy share price can move differently. The real opportunity is spotting stocks that could be undervalued before the market closes the gap.
- Company 1 - 41% below our estimate - expand a fresh manufacturing and supply chain build so higher margin film and installation programs can scale faster.
- Company 2 - 18% below our estimate - shift added capacity toward AI driven data center optics and higher value photonics packaging for communications and industrial customers.
- Company 3 - 42% below our estimate - extend a leading coconut based drinks category into private label and international channels while managing packaging, energy and freight costs.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com