


EN
Novartis (SWX:NOVN) Q3 Results Reveal A Sharp Margin Crunch
Novartis went into its Q3 2026 report with a solid recent run, up about 7.5% over the past month and roughly flat over three months, and a stock price of CHF128.78 that already reflected high expectations. The headline was not growth at the top line. It was a sharp squeeze in profitability, with quarterly basic earnings per share of about US$0.63 and net income of roughly US$1.2b, far below the run rate implied by earlier quarters. For a pharma giant long viewed as a steady earnings compounder, that gap hits sentiment fast.
Like the stability of a giant such as Novartis but uneasy when earnings suddenly compress this hard in a single quarter? Check out the 223 resilient stocks with low risk scores as a benchmark for stocks that pair resilience with smoother profit trends.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$15,029m vs. US$14,358m (up about 4.7%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$1,202m vs. US$3,928m (down about 69.4%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.63 vs. US$2.04 (down about 69.0%)
- Trailing 12-Month Net Profit Margin (FY to Q3 2026 vs FY to Q3 2025): 17.5% vs. 25.5% (margin compression of about 8 percentage points)
Ask Charlie what Novartis margin slide means for investors.
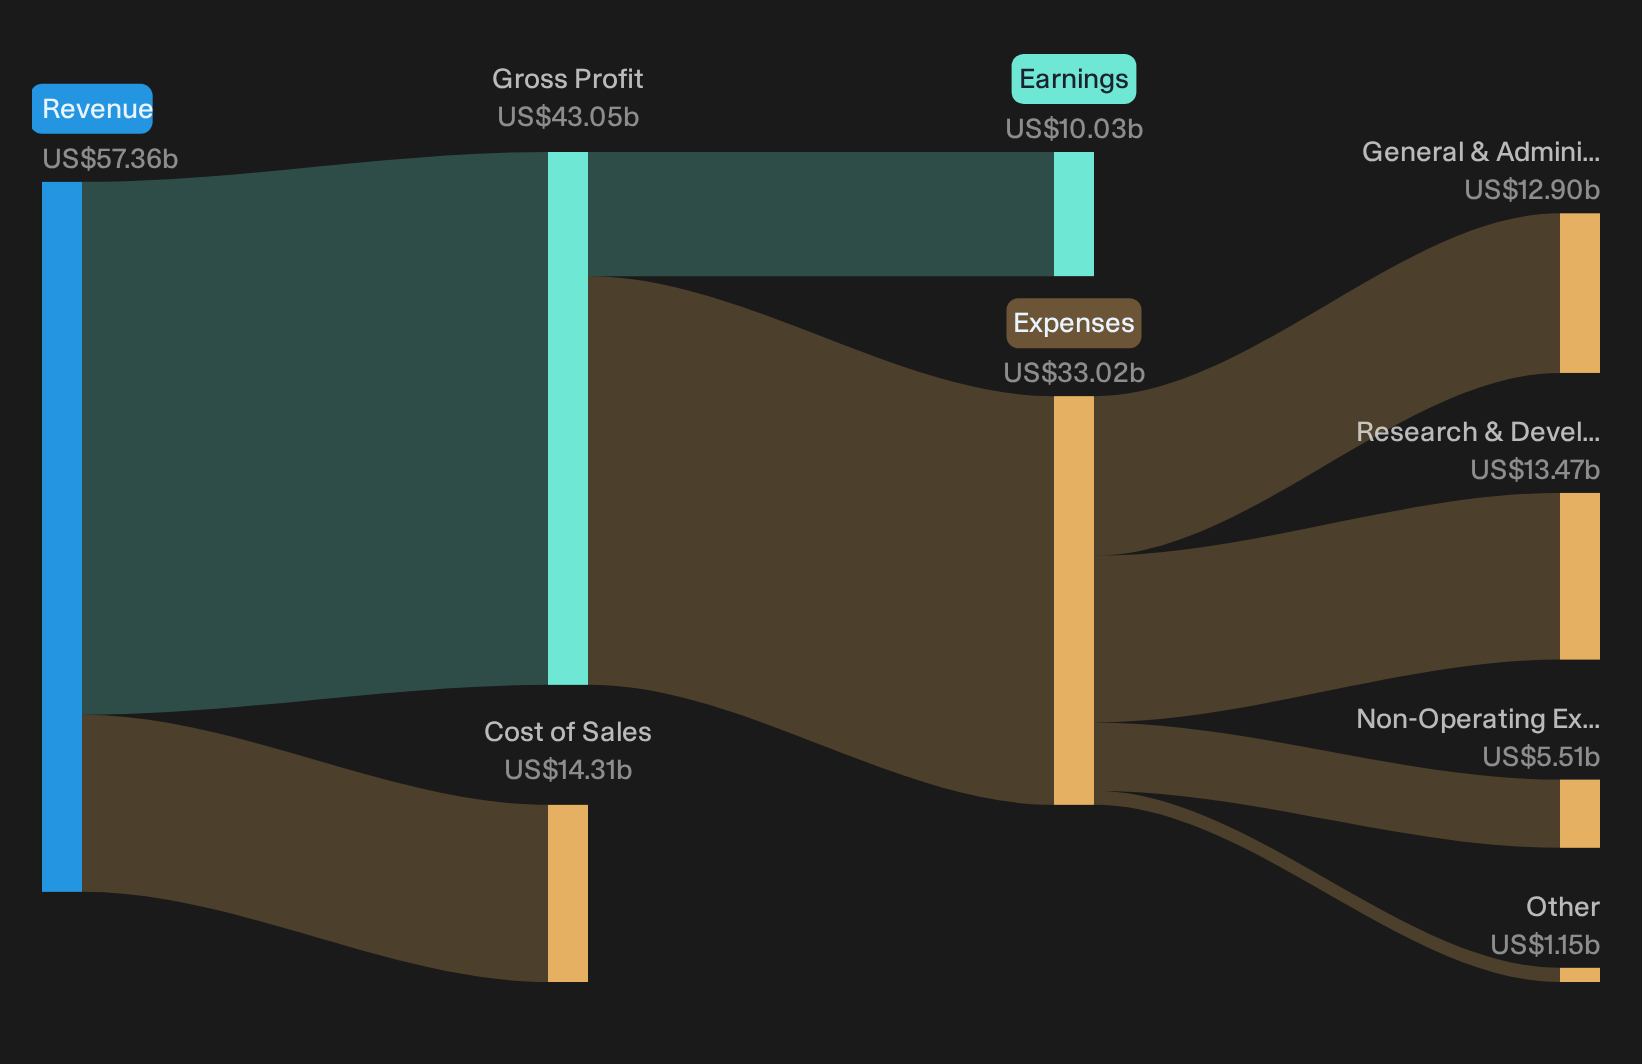
Novartis pipeline story meets a tougher margin reality
The bullish case hangs on newer therapies scaling fast enough to support richer earnings. That ambition is clear.
"A group of high growth, patent protected brands such as Kisqali, Kesimpta, Pluvicto, Cosentyx, Scemblix and Leqvio is gaining scale across multiple geographies. This supports sustained volume driven revenue growth and a mix that can support higher group earnings over time."
Q3 shows the first half of that equation working. Revenue grew about 4.7% year on year, helped by those franchises and radioligand strength. The second half fell short. Net income excluding extra items dropped about 69% and the trailing 12 month profit margin compressed from 25.5% to 17.5%. As a result, product mix is not yet cushioning earnings as the thesis implies.
One Narrative disagrees with today's price. → See where this Narrative says Novartis should trade.
Novartis margins strain under heavy pipeline spend
Bearish investors have argued that Novartis would struggle to keep profitability intact while funding overlapping late stage projects and deals. That concern is spelled out clearly.
"Incremental R&D spending from multiple late stage programs and recent acquisitions already reduces core operating margins by about three percentage points in early 2026. If these added pipelines do not convert into sizeable new products, the combination of an elevated cost base and ongoing share buybacks and dividends may constrain free cash flow and limit future earnings resilience."
The Q3 print shows this pressure directly. Revenue rose about 4.7%, yet net income excluding extra items fell roughly 69% and the trailing 12 month net margin moved from 25.5% to 17.5%. That is a clear milestone missed on earnings resilience.
Hunt For Mispriced Earnings Power
Novartis shows how investor expectations can change quickly when margins shift and profitability is questioned. The real opportunity is in stocks that could be undervalued before earnings power is fully reflected in valuations.
- Company 1 - 35% below our estimate - uses a digital farming platform and higher margin specialty products to deepen grower relationships and stabilize earnings.
- Company 2 - 43% below our estimate - scales mortgage and insurance marketplaces so historically loss making units transition toward transaction-driven and software-based economics.
- Company 3 - 23% below our estimate - builds long cycle defense programs and autonomous systems that convert a growing backlog into higher manufacturing volumes and service activity.
Those are three of them. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com