


EN
Summit Therapeutics (SMMT) Stock Jumped, What Is Driving Attention Today?
Summit Therapeutics (SMMT) has moved back into focus after a run of fresh ivonescimab updates, including a new AI pathology collaboration, another late stage biliary tract cancer trial, and a kidney cancer Phase II study.
Against that backdrop, Summit Therapeutics’ share price has been volatile, with a 5.72% one day share price return and a 19.77% 90 day share price return. At the same time, the year to date share price return is down 12.5% and the 1 year total shareholder return has declined 20.28%, while the 3 year total shareholder return of around 7x and the 5 year total shareholder return of 186.54% point to momentum that has cooled recently but remains very strong over a longer window.
Scan beyond Summit Therapeutics by reviewing a curated set of late stage healthcare and biotech plays in the 34 healthcare AI stocks that could receive similar attention for AI driven clinical pipelines.
After Summit Therapeutics’ sharp swing and a share price of US$15.33 that sits well below a roughly US$30 analyst target and a much deeper intrinsic estimate gap, an important question is where a reasonable fair value range really lands next.
Most Popular Narrative: 49% Undervalued
On the most followed view, Summit Therapeutics’ fair value sits around $30 per share, roughly double the last close of $15.33. This view places significant importance on ivonescimab delivering on its late stage program.
The breadth of ivonescimab clinical activity across at least 15 Phase III trials and more than 4,000 treated patients positions Summit to participate in the long term shift toward combination immuno oncology and anti angiogenic regimens in multiple tumor types, which is most relevant for potential future revenue growth.
See why 5 investors see Summit Therapeutics as 49% undervalued.
Result: Fair Value of $30.07 (UNDERVALUED)
Still, this depends on ivonescimab clearing tough regulatory hurdles and on Summit Therapeutics managing heavy R&D spend without revenue, both of which could quickly flip the story.
Find out about the key risks to this Summit Therapeutics narrative.
Another View: What Multiples Say About Summit Therapeutics
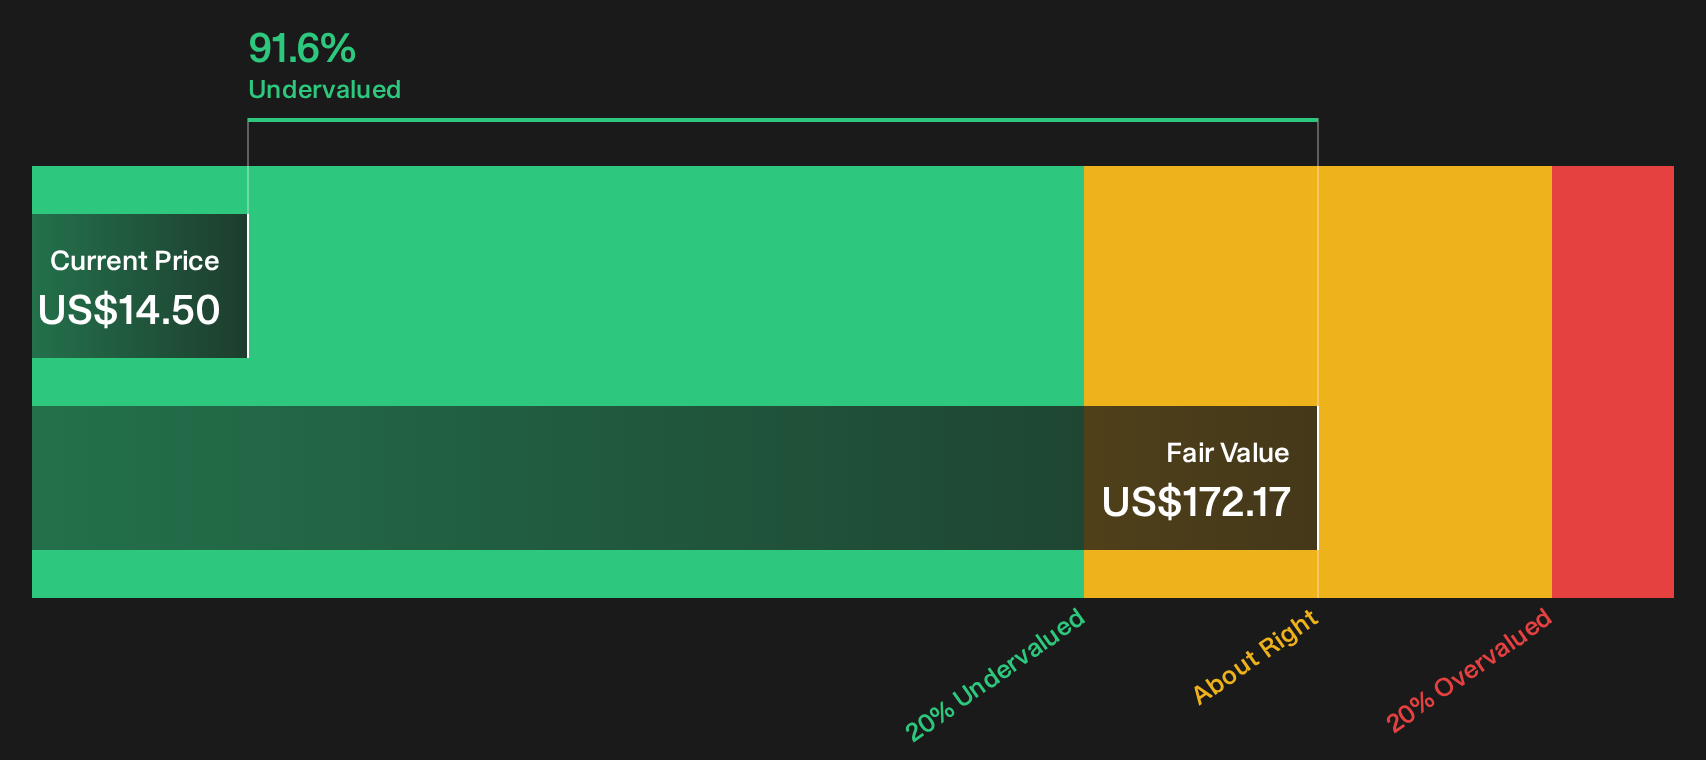
The SWS DCF model presents Summit Therapeutics as deeply undervalued, with an estimate of future cash flow value around $172.14 per share versus the current $15.33. That is a very large gap for any biotech that is still loss making. It raises a simple question for investors: Is the cash flow model too optimistic, or is the market heavily discounting the trial and execution risks around ivonescimab?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or early inflection point: either way the Summit Therapeutics story now hinges on data that you can review directly and weigh for yourself, so move quickly and size up the balance of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Summit Therapeutics?
If Summit Therapeutics has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted stock ideas that match how you like to invest.
- Target potential bargains by scanning a focused set of quality companies trading below their estimated worth through the 29 high quality undervalued stocks.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that highlights businesses with more defensive profiles and lower risk scores.
- Hunt for overlooked potential by checking a 21 high quality undiscovered gems that surfaces under the radar stocks with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com