


EN
Barrick Mining (B) Could Be 13% Above Fair Value Following Mixed Valuation Signals
With no single headline event driving attention to Barrick Mining (NYSE:B), recent share performance is doing the talking. The stock closed at $39.26, with returns mixed across different time frames.
The recent 1 day share price gain of 2.67% to US$39.26 comes after a 30 day share price return that is down 8.44%, even as the 1 year total shareholder return of 25.88% and 3 year total shareholder return above 160% point to momentum that has built over a longer horizon.
Scan beyond Barrick Mining and identify other producers with similar momentum shifts using the curated 35 elite gold producer stocks as your starting universe.
The market has shifted Barrick Mining to US$39.26, while analyst targets and intrinsic estimates point to different anchors for fair value. How wide is that gap once the valuation work is stripped back to the basics?
Price-to-Earnings of 9.9x: Is it justified for Barrick Mining?
On simple earnings terms, Barrick Mining screens as inexpensive. The stock trades on a P/E of 9.9x while sitting at $39.26, and the valuation screens as low compared to both peers and an estimated fair P/E level for the business.
The P/E ratio compares what you pay for each dollar of profit to what the company is currently earning. For a miner with established operations across assets such as Carlin, Cortez and Pueblo Viejo, this lens helps you see how the market is treating current earnings from a mature portfolio rather than paying for aggressive growth hopes.
Barrick Mining’s P/E of 9.9x is well below the US Metals and Mining industry average of 16.5x and also below the peer group average of 16.8x. The stock is also flagged as good value against an estimated fair P/E of 20.4x, which is more than double the current multiple and sets a higher bar the market could move toward if sentiment shifted closer to that fair ratio.
Explore the SWS fair ratio for Barrick Mining.
Result: Price-to-Earnings of 9.9x (UNDERVALUED)
Still, the Barrick Mining story can break if earnings come under pressure from project disruptions or if gold and copper prices retreat sharply.
Find out about the key risks to this Barrick Mining narrative.
Another view on Barrick Mining’s value
The low 9.9x P/E suggests Barrick Mining looks inexpensive, yet the SWS DCF model points the other way. On that cash flow view, the shares at $39.26 sit above an estimated value of $34.84, which implies the stock screens as overvalued on this method.
Investors weighing these conflicting signals might treat the P/E gap as potential upside and the DCF result as a reminder that cash flow assumptions can limit that optimism. The key question is which compass you rely on more in your own process.
Look into how the SWS DCF model arrives at its fair value.
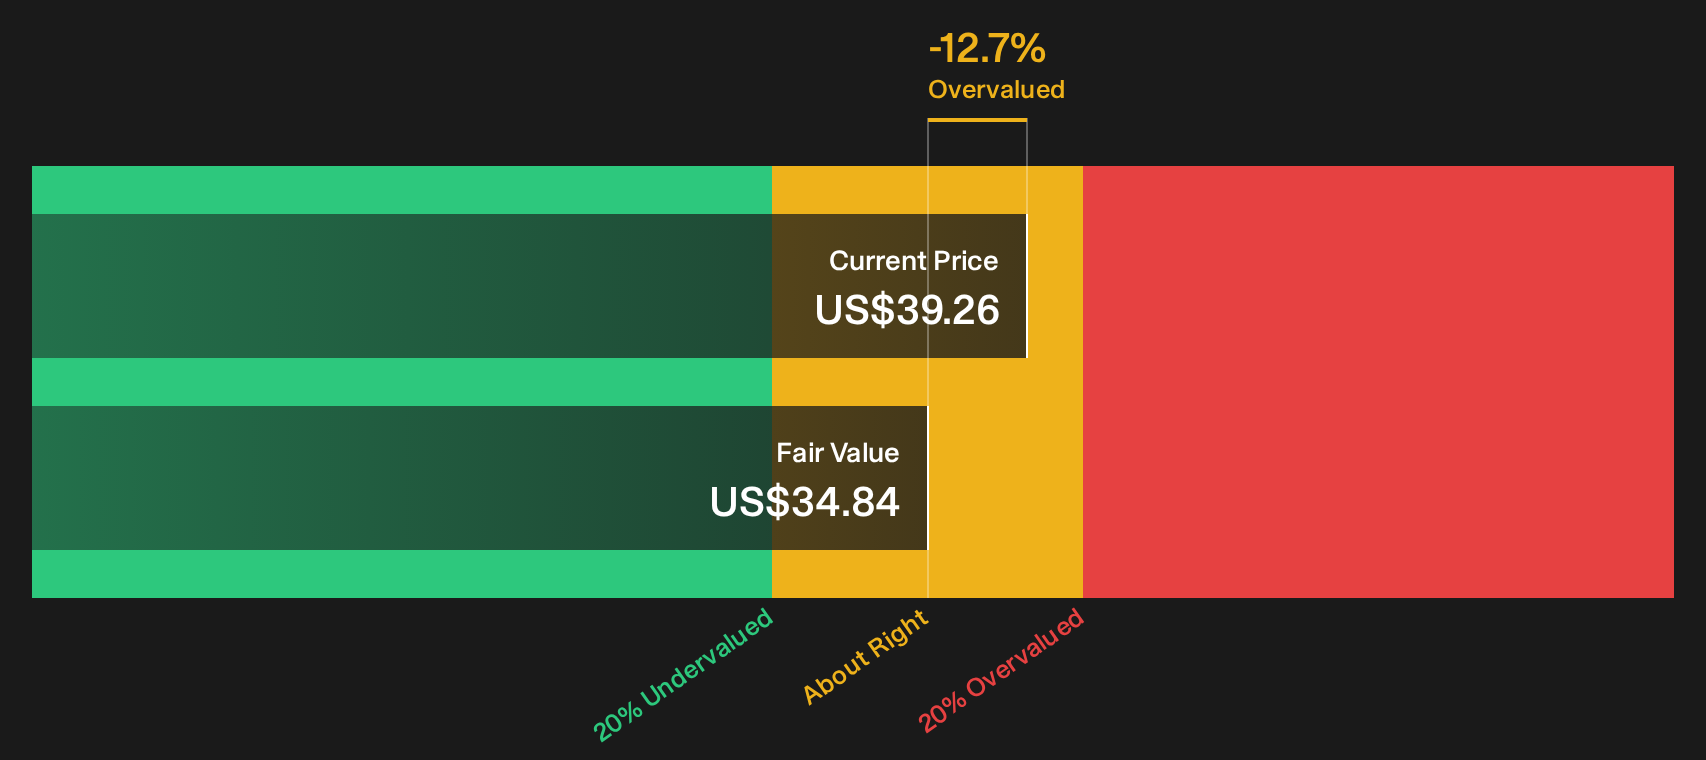
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Barrick Mining so far. If you want to move quickly and form your own view, consider both sides of the story in the 4 key rewards and 2 important warning signs
Looking for more Barrick Mining style investment ideas?
If you stop with Barrick Mining, you miss a wider set of opportunities that match different risk levels, income needs and valuation preferences across the market.
Use the Simply Wall Street Screener to move quickly from this single stock to a curated set of ideas that match how you like to invest.
- Target potential mispricing by scanning a focused group of quality companies that screen as cheap on fundamentals through the 29 high quality undervalued stocks.
- Build resilient income by reviewing a curated set of higher yielding payers using the 5 dividend fortresses.
- Dial down risk by concentrating on businesses with stronger financial footing via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com