


EN
Missed Nabors Industries' Run? Here's What Early Buyers Saw
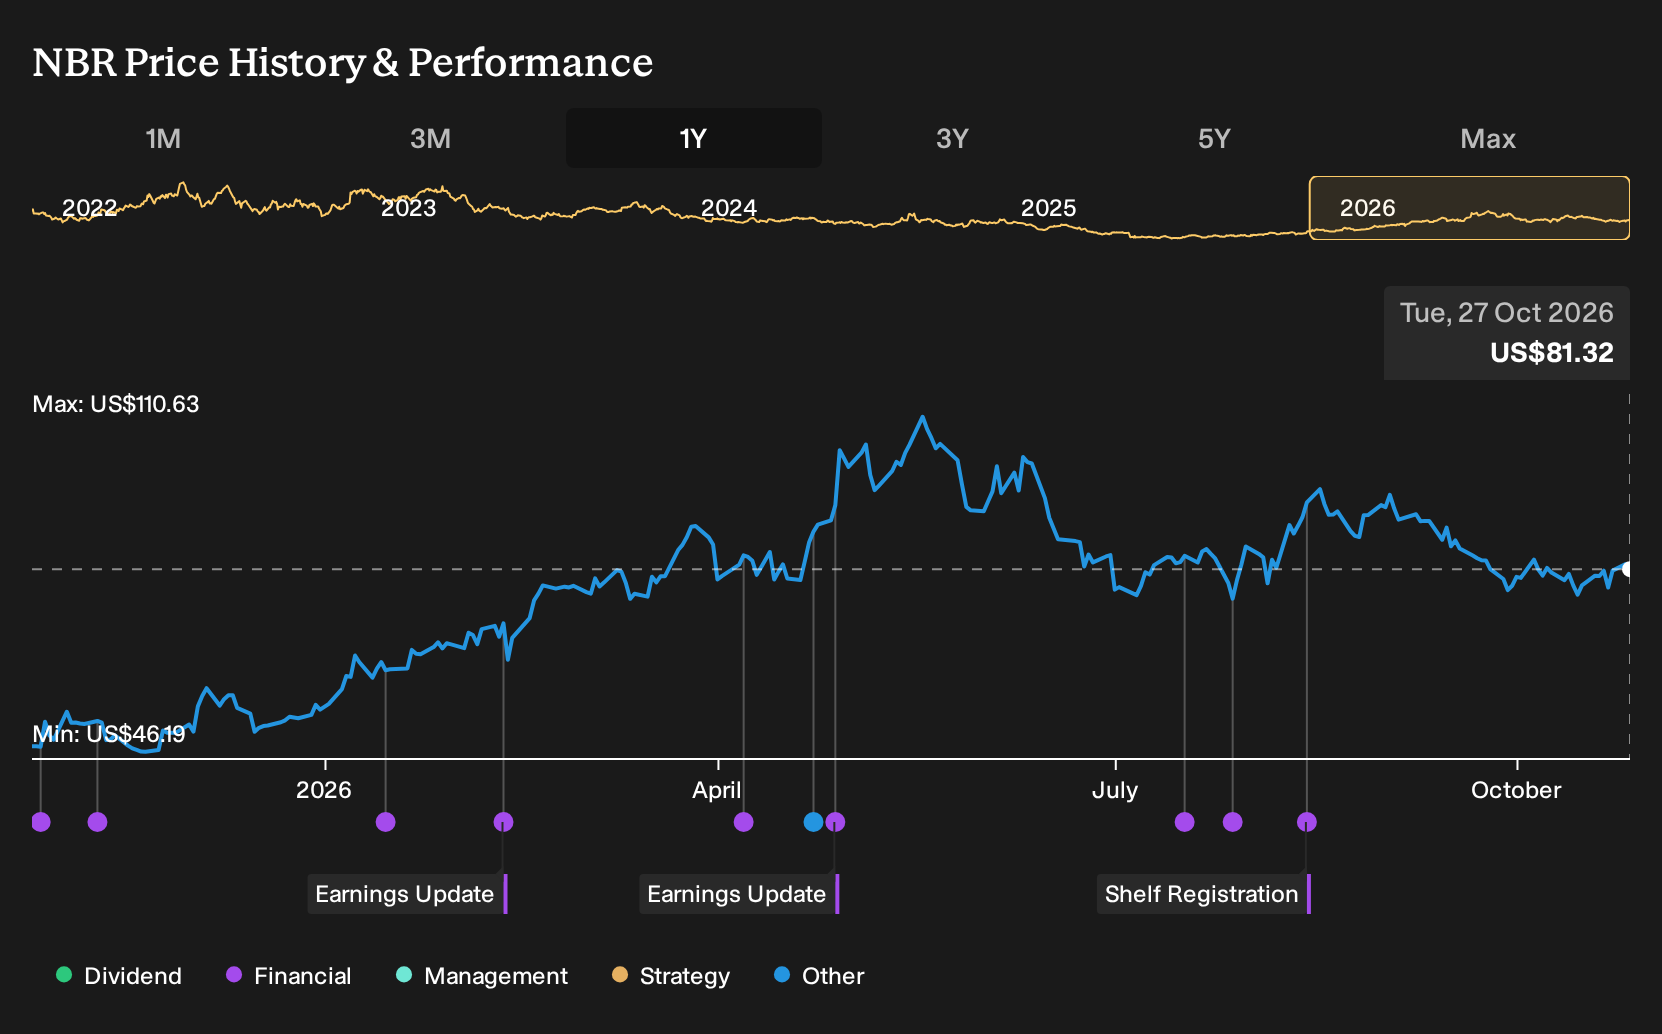
If you had put fresh money to work in Nabors Industries on 27 October 2025, the result looks very different today from the debate you would have faced back then. Holding Nabors Industries over the past year would have returned 72.4%, including dividends. Early buyers had to weigh upbeat arguments about modular rigs, drilling automation and long-term Aramco contracts against warnings on high debt, aging assets and rig margin pressure. Which of those forces looked more convincing at the start?
If the move has made Nabors Industries harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Nabors Industries Stories Investors Were Arguing About
The shares cost US$47.25 at the start of the period, and Nabors Industries sat between two sharply different but credible stories.
On the bullish side, one camp argued that advanced modular rigs and drilling automation could ride firm energy demand. Their assumptions pointed to a Fair Value of US$50, a notional price based on revenue rising 6.9% a year and margins eventually reaching 7.0%.
The more cautious view leaned on balance sheet strain and sector headwinds, with a Fair Value of US$37.44 and concern that high debt and heavy capital needs could weigh on future earnings power.
What The Results Changed For Nabors Industries
The key development for Nabors Industries was a Q2 2026 result where revenue moved to US$814.8 million while the loss narrowed to US$29.1 million and net margin improved to -3.6%. That shift in profitability backed parts of the bullish thesis on operational progress, yet the business still reported a loss so the profitability promise remained unproven.
The lesson is simple. When a story leans on future earnings power, track whether losses shrink and net margin trends toward the target level, not just whether sales move.
What Nabors Industries' 72% Run Still Leaves On The Table
Nabors Industries now trades at US$81.32 after a 72.4% gain over the past year, and the selected Narrative’s Fair Value sits above that level. Its argument leans on contract quality, higher spec rigs and drilling software steadily reshaping earnings mix and cash generation.
On this view, a buyer today must judge whether international rig margins, Nabors Drilling Solutions growth and the SANAD program eventually translate into durable, higher margin free cash flow than the price implies.
"The main factor that needs to work in the company’s favor is that Nabors Industries continues to convert its growing international rig footprint and NDS technology suite into sustained high-margin EBITDA and free cash flow, while managing the heavy SANAD capital program and associated geopolitical risks."
The price and this Narrative do not agree. → Uncover what this Narrative says Nabors Industries is actually worth
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 31% below our estimate - turn shorter brownfield tieback timelines into recurring subsea equipment and services work.
- Company 2 - 38% below our estimate - tackle complex AI safety and regulatory problems beyond the capabilities of routine consultants.
- Company 3 - 46% below our estimate - convert mechanical and electrical backlog into long duration data center infrastructure projects.
Three companies from the same screener. Open the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com