


EN
3 Australian Penny Stocks With Revenue Over A$71 Million
High inflation is expected to stick around globally into next year, and that keeps pressure on borrowing costs and everyday budgets. Australian investors who want growth potential without taking on fragile balance sheets are starting to look more closely at lower priced shares backed by healthier finances. This article breaks down three financially stronger Australian penny stocks from our screener that could be worth adding to your research list.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with healthier balance sheets. However, if you want the standouts, these 23 elite penny stocks are the most outstanding.
IGO (ASX:IGO)
IGO is a Perth based battery minerals group focused on lithium, nickel, copper and other metals. Its lithium business closely ties it to the Financially Fit Penny Stocks theme through supply into electric vehicle and battery chains. Most operating income comes from the Nova Operation, which generated about A$449 million, with A$14 million from interest, supporting a market value of roughly A$3.9b.
IGO gives you exposure to lithium and other battery metals with the added comfort of recent profitability, A$463 million in sales and a balance sheet that screens as healthier than many early stage miners, although the next move in cash flow from its core projects will matter a lot.
That next swing in cash generation is exactly what the DCF valuation analysis for IGO is built to stress test, so you can see how assumptions shift IGO’s risk reward profile.
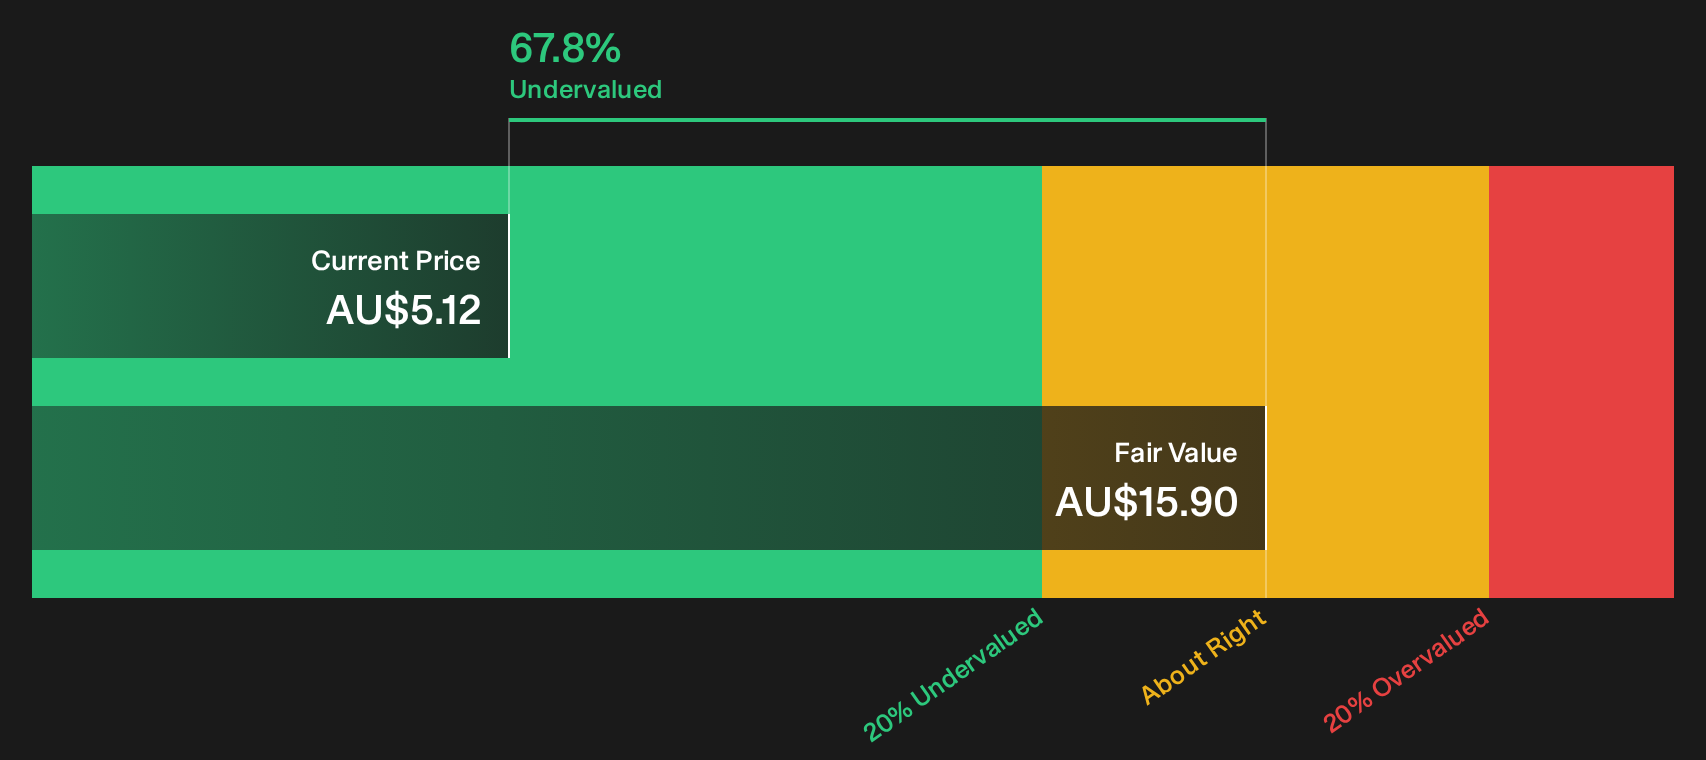
Macmahon Holdings (ASX:MAH)
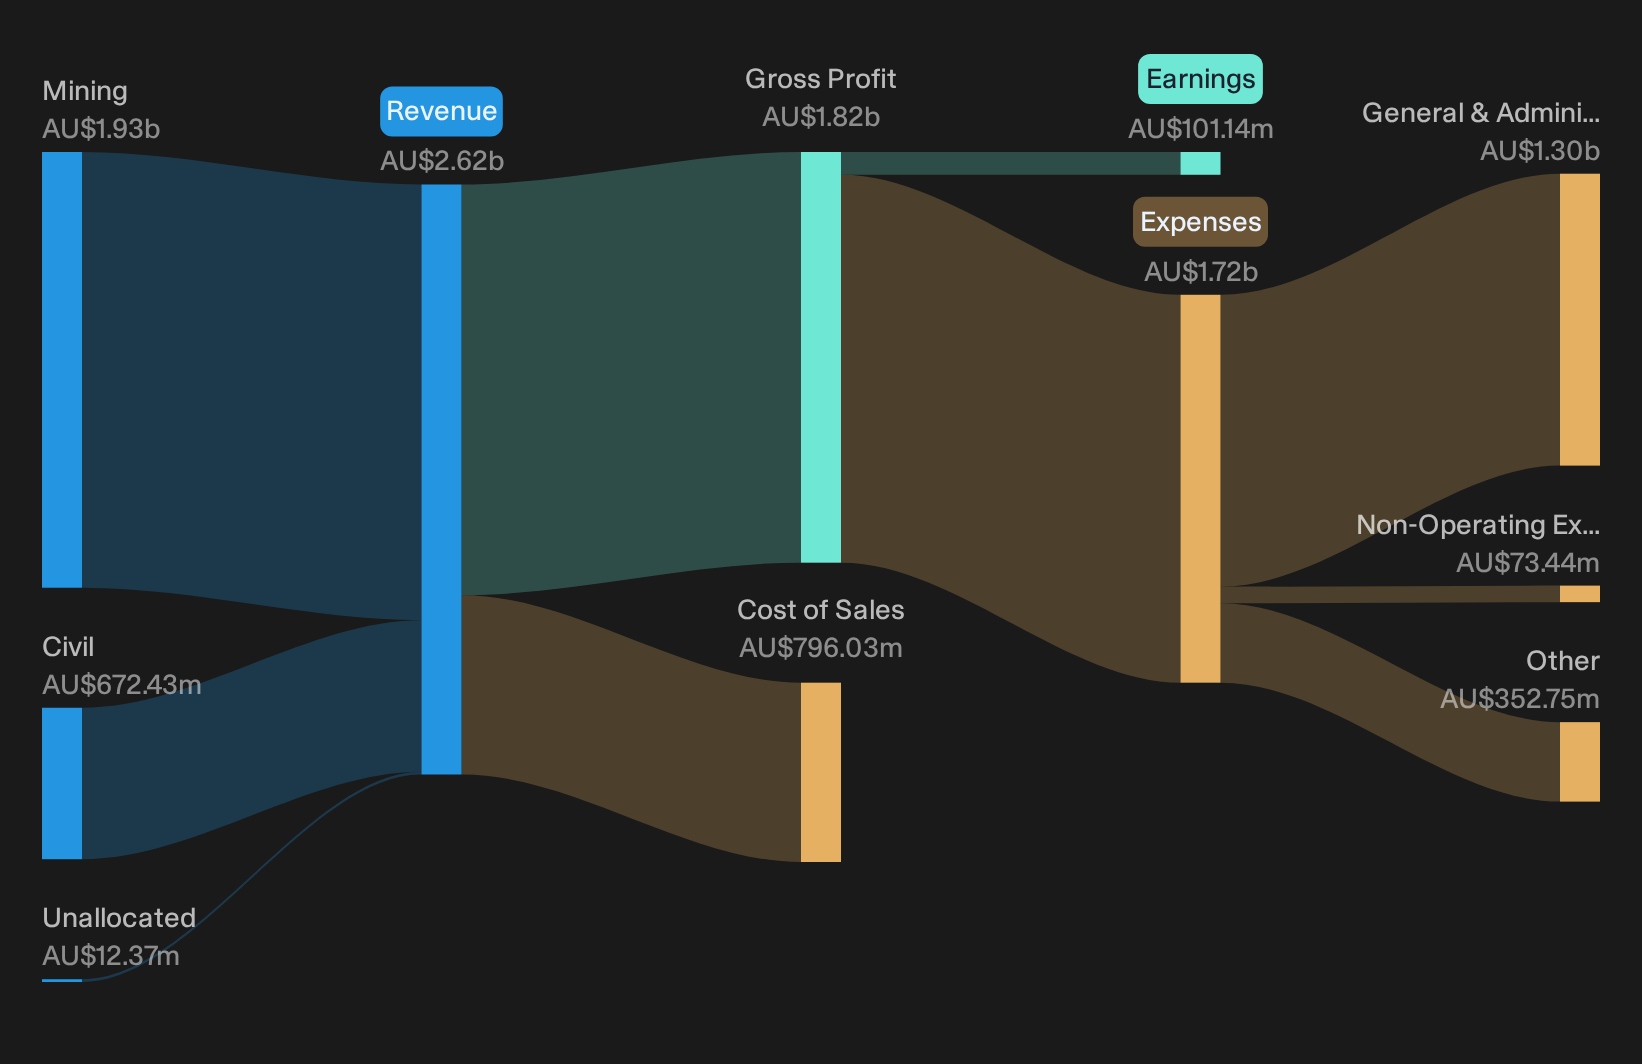
Macmahon Holdings is a Perth based contractor that earns most of its income from mining services, with about A$1.93b from mining and A$672 million from civil work, and a market value near A$2.1b. This places it in the Financially Fit Penny Stocks theme.
Macmahon Holdings taps directly into the screener’s focus through its contract mining work, where long term surface and underground services can translate healthy order books into steadier cash generation if projects are executed cleanly.
"Although Macmahon Holdings reports improved safety metrics with a lower total recordable injury frequency rate, the unresolved workplace fatality at Fosterville risks tighter regulatory oversight and higher compliance costs that could pressure operating margins and constrain earnings."
What happens to those improving margins and future cash flow hinges on how one less visible pressure on Macmahon’s contract portfolio ultimately plays out.
If that pressure point has your attention, read the full narrative for Macmahon Holdings to see how contract strength, capital discipline and future projects could reshape Macmahon Holdings’ risk profile.
BKI Investment (ASX:BKI)
BKI Investment is a Sydney based fund manager that runs a listed portfolio of mainly dividend paying, well managed Australian shares, which fits a screener focused on financially solid, lower risk stocks. It generated about A$71 million from securities industry income in Australia and carries a market value near A$1.4b.
For investors looking for financially healthier penny stocks, BKI Investment offers a listed portfolio of dividend focused Australian shares, high net margins near 91.1% and a fully franked dividend stream, although the yield is not fully backed by earnings, which means the outcome could depend on what happens if payout discipline is significantly tested.
That payout question is exactly why the analysis report for BKI Investment could be worth a look, with BKI Investment’s dividend engine laid out before stress really bites.

Seeking Fresh Alternatives Before They Fly
New ideas move first and fast. Breakout stories gain momentum while slow money is still watching. Scan fresh candidates under the radar for now and get in early.
- Spot income ideas with cash backing by scanning the curated 4 dividend fortresses before yields get caught dropping as prices move.
- Hunt for early compounding potential in a hand picked 6 resilient stocks with low risk scores and stay focused on resilience while prices still look reasonable.
- Target businesses behind the hype by filtering a curated 16 cryptocurrency and blockchain stocks before blockchain momentum stories move away from preferred entry levels.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com