


EN
Will Low Cost Production Change Evolution Mining's (ASX:EVN) Narrative
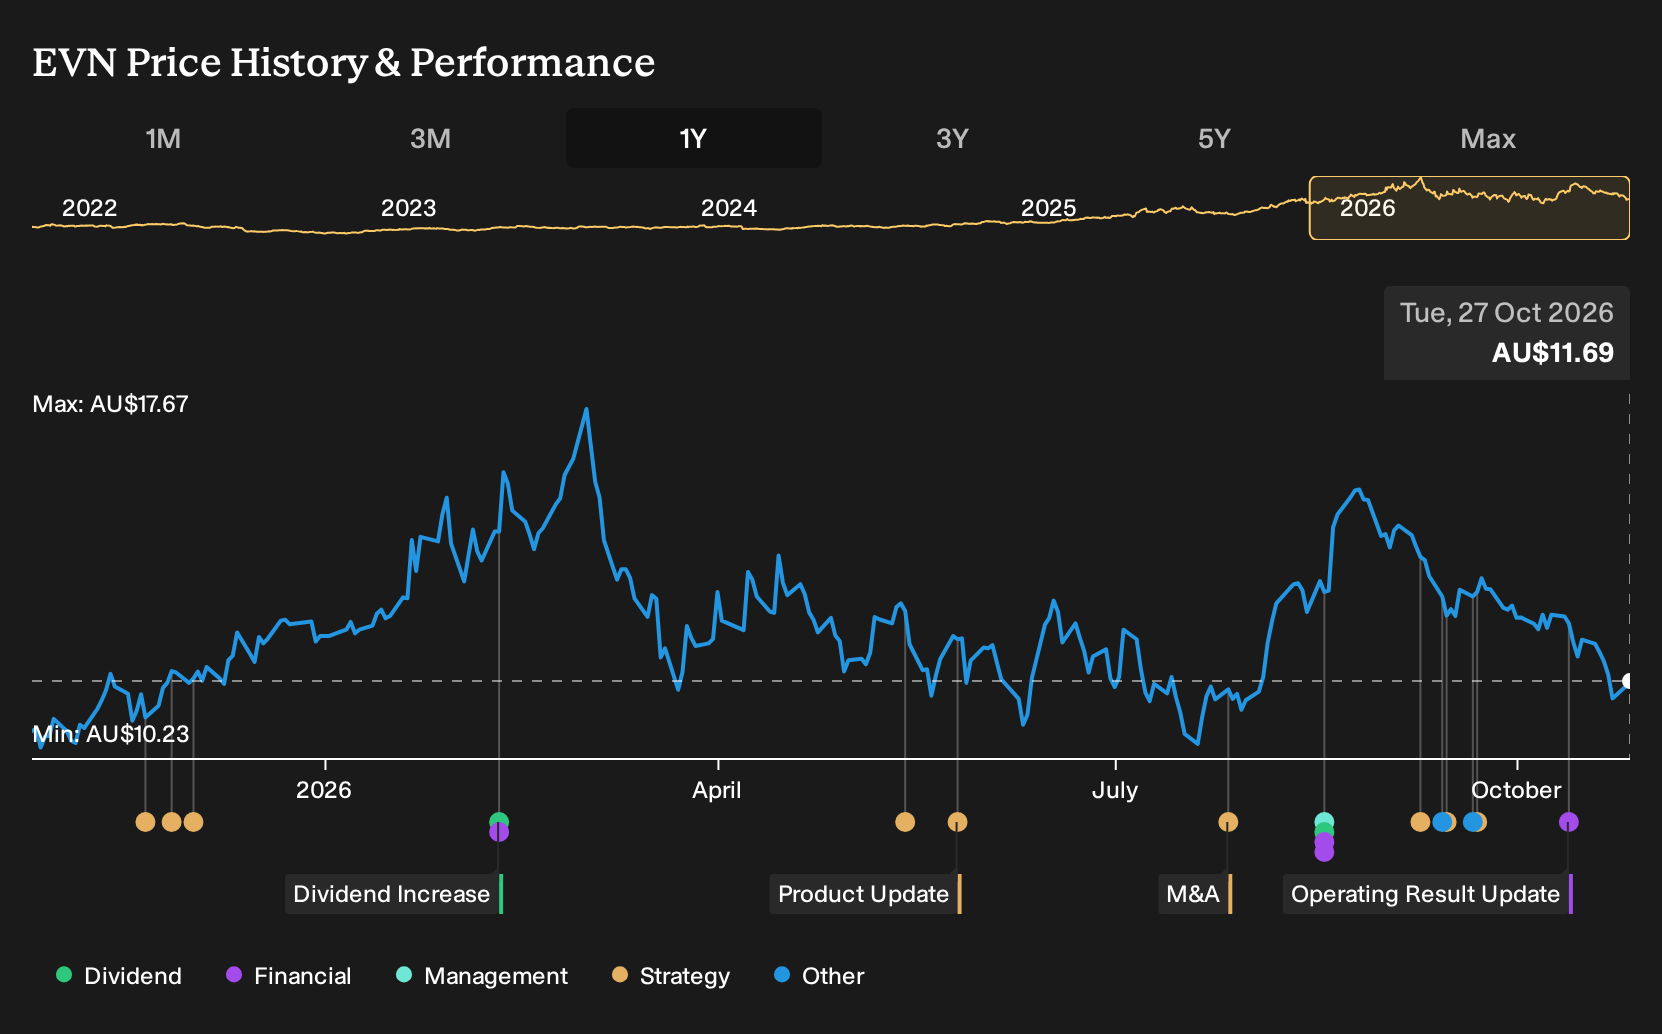
- Evolution Mining reported September quarter output of 154,000 ounces of gold and 18,000 tonnes of copper, with an all in sustaining cost of A$1,653 per ounce, and confirmed a move of its registered office to central Sydney from October 22, 2026.
- The combination of sizeable gold and copper volumes at a relatively low AISC signals tight cost control at Evolution Mining and suggests current assets are being run with an eye on cash generation rather than simply chasing headline production tonnage.
- We will explore how Evolution Mining's relatively low all in sustaining cost in the latest quarter ties into the broader investment narrative.
Scan how Evolution Mining's latest cost performance compares with peers by reviewing our hand picked list of 35 elite gold producer stocks positioned for disciplined production and capital allocation.
Evolution Mining Investment Narrative Recap
To own Evolution Mining, you need to be comfortable with a gold and copper producer that leans hard on disciplined costs and long life assets to support cash generation. The September quarter AISC of A$1,653 per ounce sits in the middle of that story. It helps in the near term as inflation and higher sustaining capital start to bite, although a single quarter does not remove those risks.
The key short term swing factor remains how consistently Evolution Mining can hold unit costs while funding an extra A$50 million to A$60 million a year of sustaining capital without squeezing margins. Grid power reliability at Mungari and Red Lake and underground labour availability in Western Australia still appear to be the main operational threats if conditions tighten further.
The September 2026 operating results are the most relevant update here. Output of 154,000 ounces of gold and 18,000 tonnes of copper at that AISC level provides a snapshot of how the portfolio is running before the next phase of growth projects at Northparkes, Ernest Henry and Cowal absorbs more capital and management attention.
For catalysts, this quarter effectively acts as a reference point for whether future copper weighted growth, such as Greater Duchess and the Northparkes upgrades, is being built on a stable operational base. If cost pressure accelerates or power and labour issues become more acute, the benefit of higher copper exposure and recovery projects could be partly offset, so consistency from this level of performance is important.
Analyst Outlook For Evolution Mining
Analyst forecasts sketch a clear hurdle rate for Evolution Mining. Consensus assumes revenue grows by 5.9% a year over the next three years while profit margins shift from 26.5% today to 33.4% by 2029. As a result, the current operations and growth projects are being measured against a richer earnings mix rather than just volume.
On earnings, the analyst group expects profit to reach A$2.2 billion by 2029, compared with A$1.5 billion today. That implies an increase of about A$700 million over the period, even though there is wide dispersion between the most optimistic estimate of A$3.1 billion and the most cautious view at A$1.6 billion.
Valuation work in these reports ties that profit profile to a P/E of 16.1x on the 2029 earnings assumption. This is lower than the 17.3x multiple cited today and higher than the 11.4x applied to the broader AU Metals and Mining industry. The forecasts also assume the share count is broadly flat and use a discount rate around 8.7% to bring those future numbers back to today.
Evolution Mining's narrative projects A$6.6 billion revenue and A$2.2 billion earnings by 2029. This requires 5.9% yearly revenue growth and an earnings increase of about A$700 million from A$1.5 billion today.
Uncover why Evolution Mining's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Evolution Mining, the bearish twist is all about copper underperformance. The lowest analysts worried that flooding at Ernest Henry and underused mill capacity could keep 2029 earnings closer to A$1.6 billion on about A$5.1 billion revenue. Those forecasts were set before this quarter and the office move, so investors may see opinions shift as fresh data emerges and can explore several viewpoints before forming their own view on the stock.
Explore 4 other Evolution Mining fair value estimates, including one that suggests there could be as much as 34% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Evolution Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Evolution Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evolution Mining's overall financial health at a glance.
Looking for more investment ideas beyond Evolution Mining?
If Evolution Mining has helped sharpen your thinking on costs, capital and risk, you can apply that same lens across the wider market. The Simply Wall St Screener can help you quickly focus on other stocks that fit different objectives, whether you care more about steady balance sheets, potential mispricing, or identifying strong businesses that are still under the radar.
- For investors who want potential upside paired with disciplined fundamentals, you can scan our hand picked 2 high quality undervalued stocks that seek to combine earnings quality with pricing that may not fully reflect it.
- If capital preservation sits near the top of your checklist, you can narrow your search to companies on the 6 resilient stocks with low risk scores that combine resilient operations with lower risk scores.
- When you are looking for fresh ideas that may not be the focus of the broader market, you can cast a wider net with the 15 high quality undiscovered gems and see which smaller, higher quality businesses meet your filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com