


EN
Private Credit Deal Could Be A Big Test For Allianz Stock (XTRA:ALV)
- Allianz Global Investors acted as lead buyer and structurer in KKR’s first private credit continuation vehicle. The vehicle closed with more than €460 million in commitments and gives existing investors the choice between liquidity or rolling into the new fund.
- The deal underlines Allianz’s push deeper into private credit, expanding its role as a capital provider and reinforcing ties with a large alternative asset manager at a time when investor interest in private credit structures is growing.
- Now the focus shifts to how Allianz’s expanding role in private credit with KKR could influence the broader investment narrative and risk profile.
Scan how Allianz is leaning into private credit, and then widen your radar with a curated set of resilient capital providers in our 223 resilient stocks with low risk scores.
Allianz Investment Narrative Recap
To own Allianz, you need to believe its mix of property and casualty, life and health, and asset management can keep generating solid earnings while absorbing FX volatility, inflation in large claims and pressure on retail affordability. The near term story leans on execution in digital and AI driven efficiency, as well as keeping the Solvency II ratio strong as capital gets redeployed.
The KKR private credit continuation vehicle is directionally aligned with that belief but does not change the main near term swing factors. It adds fee and interest income potential, yet underwriting quality, claim severity trends and premium volume in sensitive retail lines still look like the biggest operational risks to monitor.
The AllianzGI role in KKR’s €460m private credit continuation vehicle is the clearest recent operational development tied to this thesis. Allianz is not just allocating capital. It is structuring and leading a complex transaction that can deepen its asset management capabilities across private markets and support more diversified fee streams alongside the €84b of third party net inflows reported for the first half of 2026.
For catalysts, that matters most if Allianz can repeat and scale similar structures without letting risk creep undermine its solvency strength or increase earnings volatility. The opportunity is a broader private credit and alternatives platform sitting next to life and health and retirement offerings. The trade off is higher complexity, tighter risk controls and more scrutiny of how these vehicles behave through claim cycles and FX swings.
Allianz earnings assumptions behind the private credit push
For Allianz, the private credit build out with KKR now sits on top of a fairly detailed analyst earnings framework that runs out to 2029. Revenue is modelled to rise by 17.6% a year for the next three years, while profit margins are expected to move from 9.7% today to 6.7% over that same period. This means top line expansion is being balanced against thinner profitability assumptions.
Consensus forecasts point to group earnings of €13.0b by around October 2029, compared with €11.6b today. That implies an earnings increase of about €1.4b, even as analysts also factor in a gradual 0.6% yearly decline in the share count, and it sets the baseline against which moves like the KKR continuation vehicle are being judged.
On valuation, the current analyst framework assumes Allianz will be trading on a P/E of 14.9x those 2029 earnings, up from 13.4x today and above the GB Insurance sector on 12.0x. For that view to hold, the business would need to reach forecast revenues of €194.5b and earnings of €13.0b in 2029, supported by the mix of fee income, underwriting and capital strength that the private credit expansion is intended to complement rather than replace.
Allianz's narrative projects €194.5b revenue and €13.0b earnings by 2029. This requires 17.6% yearly revenue growth and an earnings increase of about €1.4b from €11.6b today.
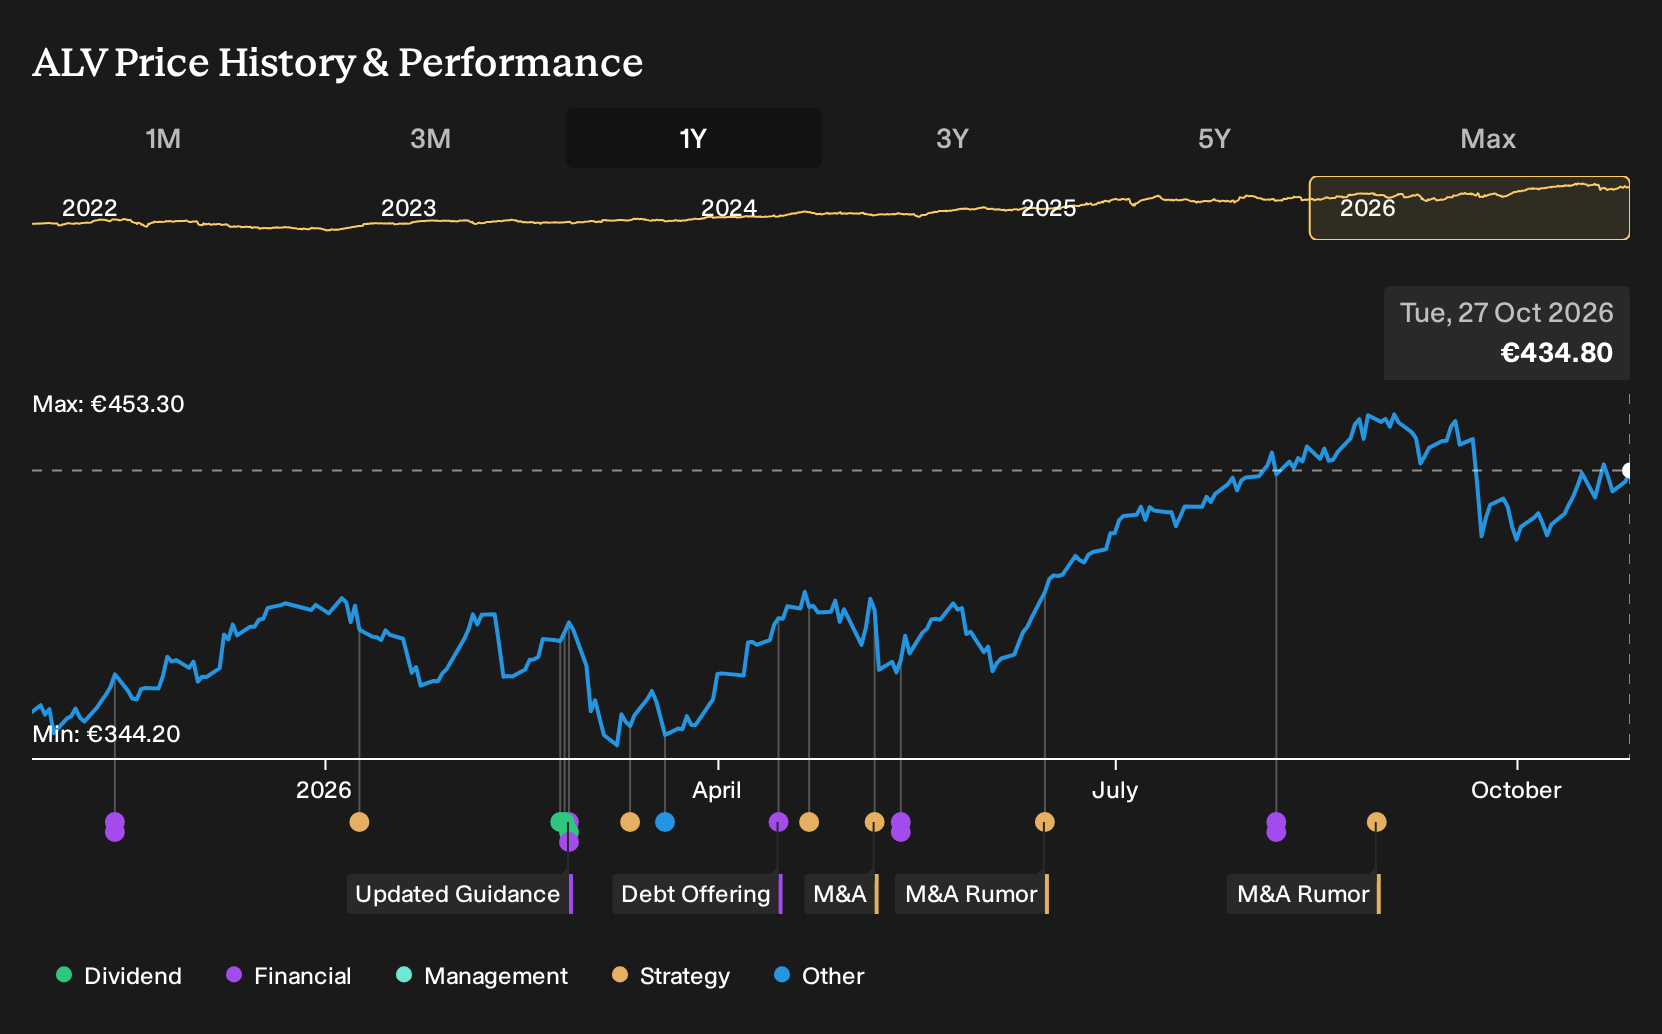
Uncover why Allianz's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You might frame this KKR private credit step as a fresh growth catalyst, yet the lowest Allianz analysts focus on execution risk instead. They were pencilling in €181.6b of 2029 revenue and €10.5b of earnings, which is well below consensus. That more cautious story could shift if this new structure meaningfully reshapes fee and profit expectations.
Explore 4 other Allianz fair value estimates, including one that suggests it could be worth just €447.27.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Allianz research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Allianz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allianz's overall financial health at a glance.
Looking for more investment ideas beyond Allianz?
If Allianz is just one piece of the portfolio puzzle you are building, it can help to scan a wider set of high quality businesses that match the risk and return profile you want.
- For investors who care most about downside protection and capital resilience, start with a curated 223 resilient stocks with low risk scores that keeps overall risk scores front and center.
- If reliable income is the goal, check out companies offering strong yields and robust payout support with our hand picked 224 dividend fortresses.
- For those hunting for underfollowed opportunities with solid fundamentals, the 610 high quality undiscovered gems can surface lesser known stocks that still meet a high quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com