


EN
CMS Energy (CMS) Q3 Earnings Leave Funding And Cash Flow Questions
CMS Energy slipped 0.9% to about US$69 in regular trading after posting its Q3 2026 earnings, a muted move for a regulated utility that just put some big numbers on the table. The quarter showed US$2.18b in revenue and US$0.39 in basic earnings per share, which matters less on a single three month snapshot and more for what it suggests about the profit path into 2027.
Short term traders focused on the small price dip. Longer term investors are weighing that softer reaction against a multi year earnings plan that still leans heavily on regulated growth and cash flow repair.
Appreciate the regulated earnings visibility at CMS Energy but worried this quarter highlights how fragile cash flow repair can feel in a rate sensitive utility? Line this up against peers using our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,183 million vs. US$2,021 million (up about 8%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$121 million vs. US$275 million (down about 56%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.39 vs. US$0.92 (declined about 58%)
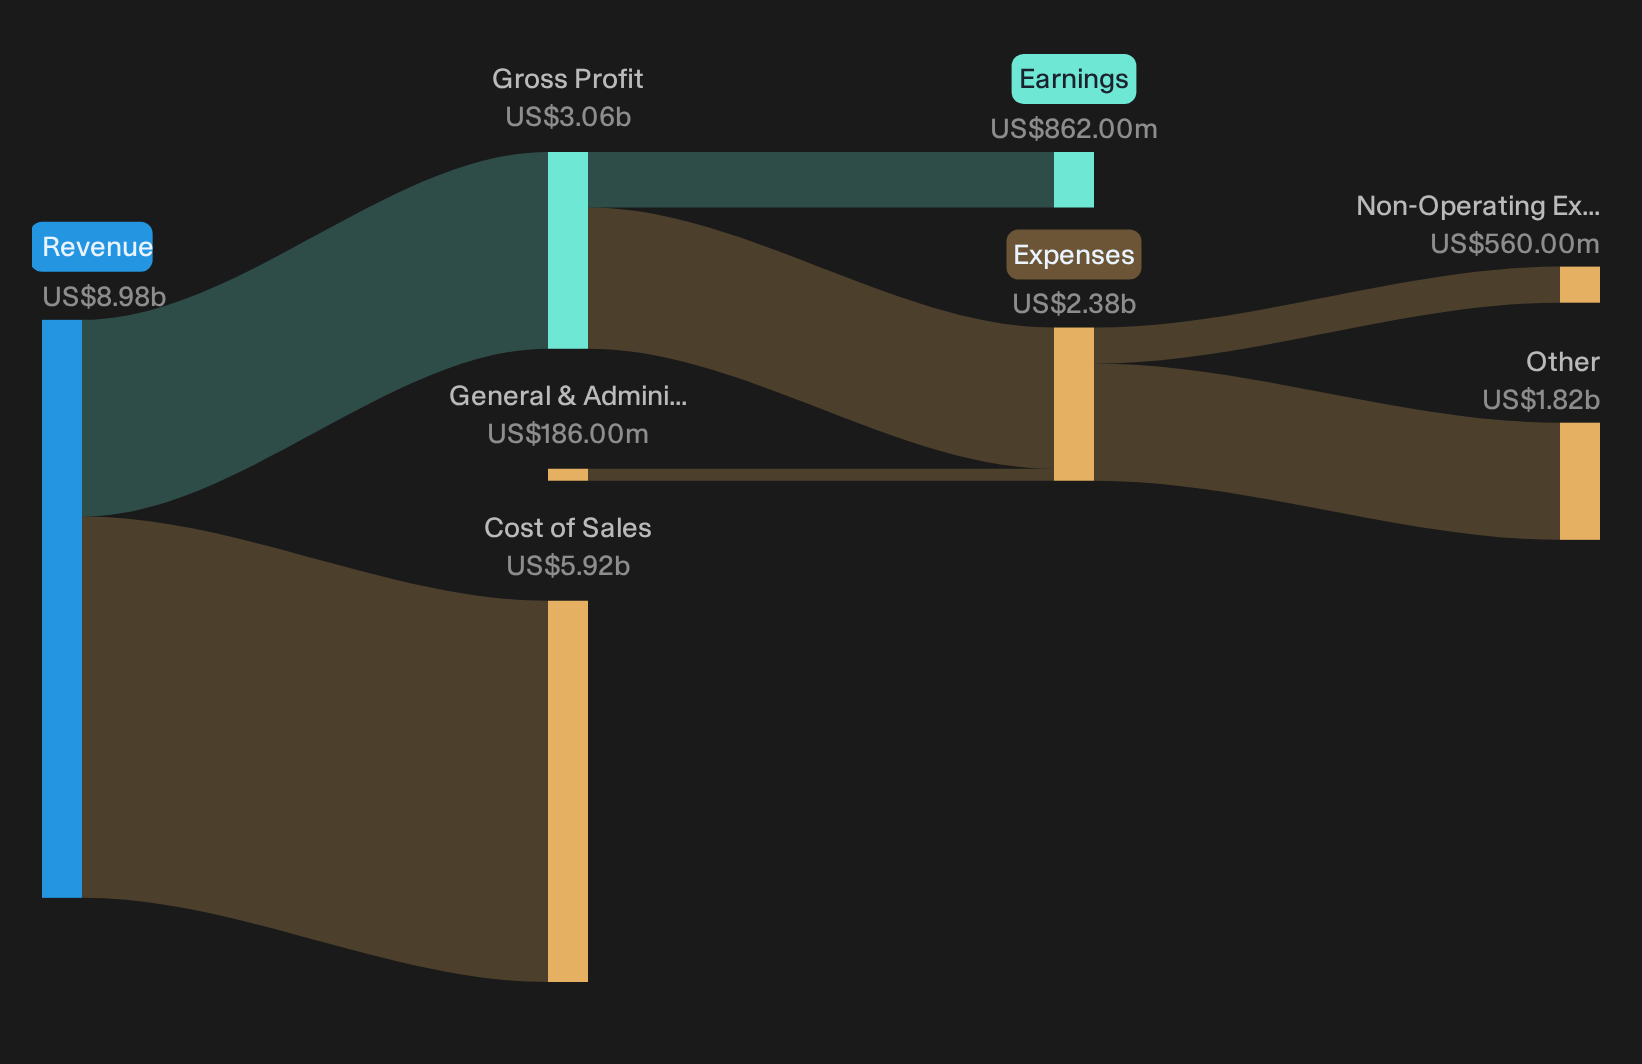
- Trailing 12 Month Revenue (Q3 2026 vs. Q3 2025): US$8.98b vs. US$8.30b (up about 8%)
CMS Energy just tied a $27 billion buildout to its new IRP. Ask Charlie what CMS Energy left out of its 2040 plan.
CMS Energy Bull Story Meets Mixed Execution Markers
The long term bull pitch for CMS Energy hinges on a cleaner, more regulated profile that should support steadier earnings over time.
"The exit from nonutility renewable development and redeployment of roughly $1.7b of planned capital into Michigan rate-base projects is expected to concentrate CMS Energy earnings on regulated assets that typically carry defined returns. This structure could support more predictable EPS and cash flow."
Guidance reaffirmation for 2026 and 2027, with management leaning to the high end, fits that predictability goal. Yet quarterly net income excluding extra items declined versus last year, and basic EPS fell from US$0.92 to US$0.39. The transition is progressing, although near term profitability looks choppy.
Testing CMS Energy Bear Concerns On Funding And Weather
On the risk side, skeptics focus on whether heavy capital plans, storms, and funding needs will erode the EPS path.
"CMS Energy is still relying on very heavy grid, clean power, storage, and gas infrastructure spending. If this requires more external funding than planned, it could mean higher interest costs or additional equity issuance, which would weigh on net margins and earnings."
Q3 actions show this pressure in real time. The group raised US$900m of utility first mortgage bonds and US$495m of parent equity, while net income excluding extra items fell sharply year on year. Storm related O&M also pulled on earnings despite some deferral approvals, so the concern around funding and volatility remains live.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt Dislocated Earnings Stories
CMS Energy shows that an active capital plan can still produce uneven quarterly profit. The real opportunity is finding stocks that may be undervalued as steady execution becomes clearer.
- Company 1 - 31% below our estimate - sells tightly integrated compute platforms that combine advanced chips with specialized software for demanding workloads.
- Company 2 - 15% below our estimate - builds power and communications infrastructure projects that support hyperscale data centers while maintaining a balance sheet without long term debt.
- Company 3 - 27% below our estimate - supplies custom chips and connectivity hardware that link key digital infrastructure for large customers on recurring contracts.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com